Tag: employee retirement benefits

  • How Can Canadian Businesses Structure Employer Matching Contributions While Managing Long-Term Costs?

    How Can Canadian Businesses Structure Employer Matching Contributions While Managing Long-Term Costs?

    Employer matching contributions can be a valuable part of a workplace retirement plan, but the strongest contribution strategy is not necessarily the one with the highest percentage.

    Canadian employers may use a percentage of employee pay, a contribution tied to employee savings, a fixed-dollar formula, or another structure permitted under the applicable retirement plan.

    The more important question is whether the contribution formula is clear to employees, aligned with the purpose of the plan, financially sustainable, and administratively workable.

    A well-designed approach to employer matching contributions should therefore balance employee participation with budget capacity, payroll administration, plan structure, eligibility rules, communication, and ongoing governance.

    Quick Answer: How Should Employers Structure Matching Contributions?

    Canadian businesses can structure employer matching contributions by first defining the purpose of the retirement plan, modelling employer costs under different participation scenarios, choosing an appropriate plan structure, keeping the formula easy to understand, coordinating payroll and administration, communicating requirements clearly, and reviewing the arrangement periodically.

    The goal should be a clear and sustainable contribution structure—not simply the highest possible employer match.

    Why Employer Matching Contributions Require Careful Planning

    Employer contributions represent a real compensation and plan cost.

    Before introducing or changing a formula, employers may need to consider:

    • The purpose of the retirement plan
    • Budget and cash-flow capacity
    • Workforce characteristics
    • Eligibility rules
    • Payroll requirements
    • Contribution timing
    • Applicable tax rules
    • Plan type
    • Employee participation
    • Contribution caps
    • Administrative complexity
    • Future workforce growth

    The source file specifically recommends considering different participation scenarios because an arrangement that appears affordable at today’s participation level may cost substantially more if more employees begin contributing or payroll grows.

    There is no single formula that works for every Canadian employer.

    8 Smart Ways to Structure Employer Matching Contributions

    1. Define the Purpose of the Employer Contribution

    Start by deciding what the contribution structure is intended to support.

    The objective may include:

    • Encouraging retirement saving
    • Supporting employee participation
    • Strengthening total compensation
    • Supporting a profit-sharing philosophy
    • Providing a structured workplace savings benefit
    • Supporting another clearly documented plan objective

    This matters because employer matching contributions should be designed around the purpose of the plan—not added simply because another employer offers a particular percentage.

    A documented purpose also helps future governance reviews.

    2. Build a Sustainable Employer Budget

    Before finalizing a formula, model the potential cost using actual payroll information.

    Consider several scenarios:

    • Current participation
    • Higher employee participation
    • Workforce growth
    • Higher average compensation
    • Changes in eligibility
    • Different contribution caps
    • Different matching formulas

    For example, a formula that is manageable when 40% of eligible employees participate may produce a very different employer cost if participation rises to 75%.

    The objective is not to predict employee behaviour.

    It is to understand the range of possible costs before committing to employer matching contributions.

    3. Choose the Right Retirement Plan Structure

    Employer contributions can work differently depending on the type of retirement arrangement.

    For example, a Group RRSP and a DPSP are not interchangeable.

    The source file notes that employer-made Group RRSP contributions may have specific payroll and tax treatment, while a DPSP has its own rules and only participating employers contribute to it.

    Depending on the organization, a structure might involve:

    • Group RRSP
    • DPSP
    • Registered pension plan
    • PRPP
    • Another permitted group retirement arrangement

    The appropriate structure depends on plan objectives, payroll, tax treatment, legal requirements, and administration.

    4. Keep the Matching Formula Easy to Understand

    Employees should be able to understand the employer contribution without needing to decode a complicated formula.

    Communication should explain:

    • What percentage or dollar amount applies
    • Whether an employee contribution is required
    • The maximum employer contribution
    • Eligibility requirements
    • Waiting periods
    • Contribution timing
    • Any applicable limits

    A simple employer matching contributions formula can be easier for employees to understand and easier for HR and payroll teams to administer.

    Complexity should only be added when there is a clear plan reason for it.

    5. Explain Exactly What Employees Need to Do

    Employees should know what actions are required to receive the employer contribution.

    A clear explanation might answer:

    • Do I need to contribute first?
    • What percentage do I need to contribute?
    • What is the maximum employer contribution?
    • When does matching begin?
    • When are contributions deposited?
    • Is there a waiting period?
    • Can the formula change?
    • Where are the official plan terms?

    Clear communication reduces uncertainty around employer matching contributions and prevents employees from relying on assumptions.

    6. Coordinate Payroll and Administration Before Launch

    Contribution design and payroll administration need to match.

    Employers should confirm:

    • Payroll coding
    • Contribution calculations
    • Eligibility dates
    • Provider requirements
    • Contribution timing
    • Reporting
    • Reconciliation
    • Employee records
    • Plan administration responsibilities

    Even a strong matching formula can create problems if payroll and provider processes are not aligned.

    This is why contribution design should connect with broader retirement plan governance rather than being treated only as an HR benefit decision.

    For example, when an employee becomes eligible, there should be a clear process showing:

    1. When eligibility begins
    2. When payroll deductions start
    3. How the employer match is calculated
    4. When funds are transmitted
    5. How errors are identified and corrected

    Clear administration helps ensure employer matching contributions operate as described to employees.

    7. Review the Contribution Structure Regularly

    A contribution formula should not automatically remain unchanged forever.

    The employer should periodically consider whether the arrangement still fits:

    • Plan objectives
    • Financial capacity
    • Workforce size
    • Payroll levels
    • Employee participation
    • Compensation strategy
    • Plan structure
    • Administrative requirements

    A formula that worked for a business with 25 employees may need a different review when that organization grows to 100 employees.

    Similarly, changing salaries or eligibility rules may alter employer costs even when the matching percentage stays the same.

    Regular review helps keep employer matching contributions aligned with both the retirement plan and the organization’s financial capacity.


    How Can Employers Balance Participation and Cost?

    This is where the strategy becomes particularly important.

    An employer may want employees to understand and use the benefit while also avoiding an unpredictable long-term cost commitment.

    The answer is not necessarily to reduce the benefit.

    Instead, employers can improve the quality of the design through:

    • Clearly defined contribution limits
    • Sustainable caps
    • Eligibility rules
    • Accurate cost modelling
    • Clear employee communication
    • Payroll controls
    • Periodic review

    The employer can model several participation levels before implementation.

    For example:

    Current Participation → Higher Participation → Workforce Growth → Higher Payroll

    The key question is:

    Can the organization continue funding the contribution formula if more eligible employees actually use the benefit?

    That is a healthier question than designing the plan around today’s lowest-cost scenario.


    Cost Modelling Should Include More Than Today’s Payroll

    A common planning mistake is to calculate employer cost using current payroll and current participation only.

    That provides only one snapshot.

    A stronger analysis should consider how employer matching contributions may change when:

    Employee Participation Increases

    More eligible employees may decide to participate after improved education or communication.

    Compensation Increases

    If the employer contribution is tied to salary, cost may increase as compensation increases.

    The Workforce Expands

    Hiring can increase the number of eligible plan members.

    Eligibility Changes

    Expanding eligibility may affect the number of employees receiving employer contributions.

    Contribution Caps Change

    A higher maximum employer contribution can materially affect future cost.

    Scenario modelling helps management understand the range of potential commitments before changing the plan.


    How Should Employer Matching Be Explained to Employees?

    Employee communication should answer practical questions quickly.

    How Much Does the Employer Contribute?

    Explain the formula clearly using the plan’s actual terms.

    What Must the Employee Do?

    If the employee must contribute to receive the match, say so clearly.

    Is There a Maximum?

    Employees should understand applicable contribution caps.

    When Do Contributions Begin?

    Clearly explain eligibility dates and waiting periods.

    Can the Formula Change?

    Where appropriate, explain that the contribution structure is governed by plan documents and may be subject to permitted amendments.

    Where Can Employees Get Help?

    Provide a clear member-support contact and access to official plan documents.

    Clear communication makes the employer contribution easier to value.


    Why Education Should Continue After Enrolment

    Employees may first hear about the retirement plan during onboarding—when they are also processing payroll information, workplace policies, training, benefits, technology, and job expectations.

    That is a lot of information at once.

    Employers can reinforce employer matching contributions later through:

    • Annual benefit communication
    • Plan reminders
    • Member education sessions
    • Digital plan materials
    • Portal resources
    • Financial-wellness education
    • Communications when plan features change

    CAPSA’s guidance emphasizes ongoing member education rather than treating enrolment as the only communication event.

    Repeated education gives employees another opportunity to understand the employer-funded portion of their retirement plan.


    How Can Employers Keep Contribution Information Accurate and Reliable?

    The communication process should always be grounded in current information.

    Employers should:

    • Use current official plan documents
    • Confirm contribution formulas with the provider
    • Verify payroll treatment
    • Avoid unsupported promises
    • Update materials after plan changes
    • Document decisions
    • Review employee-facing explanations
    • Provide a clear contact point for questions

    If a plain-language summary conflicts with the official plan document, the plan document should govern.

    This authenticity layer is especially important when contribution formulas are adjusted over time.


    How Employer Matching Fits With Retirement Plan Governance

    Employer matching contributions should be part of the broader retirement plan governance process.

    Employers should document:

    • Why the contribution formula was selected
    • What cost scenarios were considered
    • Who approved the arrangement
    • How payroll implementation was reviewed
    • How employees were informed
    • When the structure will be reviewed again

    This creates accountability and makes future plan reviews easier.

    It also reduces reliance on institutional memory when HR, finance, management, or provider contacts change.


    Employer Matching and Inclusive Retirement Benefits

    Employers should also consider how employees across different career stages and income levels understand the matching formula.

    This does not mean recommending different personal contribution amounts.

    Instead, an inclusive retirement benefits approach can ensure employees receive:

    • Clear eligibility information
    • Plain-language matching explanations
    • Accessible education
    • Multiple learning formats
    • Ongoing support

    Employees should be able to understand how the benefit works even if they make different personal contribution decisions.


    Employer Matching and Retirement Income Education

    The employer contribution can also be explained within the employee’s broader retirement income education.

    For example, employees can learn that retirement income may come from several sources, including:

    • Government programs
    • Workplace retirement benefits
    • Personal savings
    • Investments

    The employer matching contribution is one component within that broader picture.

    Employers should explain the workplace plan clearly without estimating an employee’s future retirement income or promising a particular outcome.

    Employer matching contributions for Canadian businesses with clear plan design, employee participation, payroll coordination, and sustainable long-term costs.

    What Employers Should Avoid

    When designing or communicating employer matching contributions, employers should avoid:

    • Selecting a formula without modelling future cost
    • Making the formula unnecessarily complicated
    • Treating different retirement structures as interchangeable
    • Promising that the match will never change when plan terms permit changes
    • Guaranteeing increased participation
    • Guaranteeing improved retention
    • Recommending a personal contribution level
    • Allowing payroll and plan documents to conflict
    • Relying only on onboarding for employee education

    The strongest approach is clear, documented, administratively workable, and financially sustainable.


    Why This Matters to Business Owners

    Employer contributions are both a retirement-plan feature and a compensation cost.

    That means decisions about employer matching contributions should be considered alongside:

    • Cash flow
    • Compensation strategy
    • Workforce growth
    • Payroll
    • Employee communication
    • Plan administration
    • Long-term business planning

    The objective should not be to maximize the percentage simply because a higher number appears more attractive.

    A more useful objective is:

    Create a contribution arrangement employees can understand and the business can sustain.

    That is a stronger foundation for long-term plan management.


    Important Implementation Boundaries

    Employer contribution arrangements can involve:

    • Tax
    • Payroll
    • Pension
    • Employment requirements
    • Plan documents
    • Contribution limits
    • Governance
    • Communication

    Treatment can differ materially depending on whether the arrangement involves a:

    • Group RRSP
    • DPSP
    • Registered pension plan
    • Pooled registered pension plan
    • Other retirement-savings structure

    Employers should obtain appropriately qualified retirement-plan, legal, tax, payroll, pension, and compliance advice before introducing or materially changing employer matching contributions.

    This includes changes to eligibility, contribution caps, payroll treatment, plan combinations, or material employee communication.

    Employees who require individualized financial or tax advice should be directed to qualified professionals.


    Need Help Structuring Employer Contributions More Clearly?

    A well-designed employer contribution arrangement should align the workplace retirement plan with the organization’s objectives, administration, employee communication, and financial capacity.

    Open Access Limited may support employers with the retirement-plan component of this process, including:

    • Reviewing available group retirement structures
    • Establishing plan-specific eligibility and contribution provisions
    • Documenting employer matching rules
    • Coordinating plan administration
    • Preparing enrolment and member materials
    • Supporting ongoing employee education
    • Providing member support

    Open Access Limited materials also describe employer contributions that may be structured as a percentage of salary or a fixed-dollar amount, depending on plan design.

    Employers remain responsible for determining the financial commitment appropriate for their organization and obtaining tax, payroll, legal, and other professional advice where required.

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6, Canada

    Toll-Free: 1-866-625-4777
    General: 416-364-8877
    Fax: 416-955-4878
    Email: inquiry@OpenAccessLtd.com
    Website: www.OpenAccessLtd.com

    Employer matching contributions cost modelling for Canadian businesses across employee participation, payroll growth, workforce expansion, eligibility changes, and contribution caps.

    Frequently Asked Questions About Employer Matching Contributions

    Are Employer Matching Contributions Required to Be the Same for Every Business?

    No. There is no single contribution formula that is appropriate for every organization. Plan type, workforce characteristics, compensation, financial resources, and organizational objectives may all affect the design.

    Should Employers Offer the Highest Match They Can Afford Today?

    Not necessarily. Employers should also consider how the cost could change with increased participation, higher salaries, workforce growth, or changes in eligibility.

    Can an Employer Matching Formula Change?

    That depends on the governing plan terms and applicable requirements. Employers should avoid describing a reviewable or amendable contribution as permanently guaranteed.

    Can Employers Recommend How Much Employees Should Contribute?

    Employers can explain the plan and matching formula, but personalized contribution recommendations should be handled by appropriately qualified professionals.

    Are Group RRSPs and DPSPs the Same?

    No. They operate differently and may have different contribution, tax, payroll, eligibility, and administrative requirements.

    How Often Should Employer Contributions Be Reviewed?

    Employers should periodically reassess the contribution arrangement as payroll, participation, workforce composition, plan objectives, and financial circumstances change.


    Final Thoughts

    Employer matching contributions can add meaningful value to a workplace retirement plan when they are designed with both employees and the business in mind.

    The strongest contribution strategy is not necessarily the largest.

    It is one that is:

    Clear to employees. Sustainable for the employer. Accurate in payroll. Consistent with the plan. Reviewed over time.

    By defining the purpose, modelling long-term costs, selecting an appropriate plan structure, communicating clearly, coordinating administration, and reviewing the arrangement regularly, Canadian businesses can create a more durable employer contribution strategy without making promises about employee behaviour or business outcomes.

    Employer matching contributions explained to Canadian employees with clear eligibility rules, contribution limits, payroll timing, enrolment information, and retirement plan support.

    REFERENCES

    1. Canadian Association of Pension Supervisory Authorities — Guideline No. 3: Guideline for Capital Accumulation Plans
    2. Canada Revenue Agency — Contributions to Savings and Pension Plans
    3. Canada Revenue Agency — Register a Deferred Profit Sharing Plan
    4. Canada Revenue Agency — RRSPs and Other Registered Plans for Retirement
    5. Open Access Limited — Group Retirement Plans in Canada
    6. Open Access Limited — Setting Up a Group Retirement Plan for Your Business in Canada

  • How Can Canadian Businesses Explain Retirement Plan Fees Clearly and Help Employees Understand What They Pay For?

    How Can Canadian Businesses Explain Retirement Plan Fees Clearly and Help Employees Understand What They Pay For?

    Retirement plan fees can be difficult for employees to understand, even when the information is already available in plan documents or account statements.

    A workplace retirement plan may involve investment-management fees, fund operating expenses, recordkeeping costs, service-provider fees, account charges, or transaction-related costs. The challenge is that employees may see these numbers without understanding what they cover, who pays them, or how they may affect long-term savings.

    For Canadian employers, the goal should not be to describe a plan simply as “low cost” or “high value.” A stronger approach is to explain retirement plan fees clearly, connect applicable costs to the services employees receive, show where current fee information can be found, and help employees understand that fees are one factor among several when evaluating retirement-plan investments.Employers can strengthen this process by incorporating fee reviews into their broader retirement plan governance framework, including provider oversight, documentation, communication, and periodic review.

    Quick Answer: What Should Employees Know About Retirement Plan Fees?

    Canadian employers can explain retirement plan fees more clearly by identifying the fees that apply, explaining who pays them, connecting costs to the services provided, showing how fees may affect savings over time, and directing employees to current plan-specific information.

    Employers should use plain language, avoid unsupported “lowest cost” or “best value” claims, and provide access to qualified support when employees have individual investment or retirement questions.

    What Types of Retirement Plan Fees May Employees See?

    Not every workplace retirement arrangement has the same fee structure.

    Depending on the plan and available investment options, employees may encounter:

    • Investment-management fees
    • Fund operating expenses
    • Account fees
    • Trustee or custody fees
    • Recordkeeping fees
    • Service-provider expenses
    • Transfer or transaction charges
    • Fees for certain optional services, tools, or advice

    Employers should therefore avoid using a generic fee list as though it applies identically to every employee.

    Current plan documents and provider materials should determine which retirement plan fees actually apply.

    This distinction matters because transparency is not simply about providing more numbers. It is about helping employees understand the numbers that are relevant to their own workplace plan.

    7 Smart Ways to Explain Retirement Plan Fees Clearly

    1. Use Plain Language Instead of Fee Jargon

    Retirement-plan terminology can become technical very quickly.

    Employees may see terms such as:

    • Investment-management fee
    • Operating expense
    • Asset-based fee
    • Service-provider fee
    • Management Expense Ratio (MER)
    • Recordkeeping cost

    Employers can make retirement plan fees easier to understand by defining terms in short, plain-language explanations.

    Instead of simply listing a technical fee, explain what the fee represents and where the employee can find the current amount.

    Formal plan documents should remain authoritative, but plain-language education can help employees navigate those documents more confidently.

    A simple rule works well:

    Name the fee. Explain what it means. Show where to verify it.

    2. Explain Who Actually Pays Each Cost

    Employees may assume that every plan-related expense comes directly from their account.

    That may not be the case.

    Depending on the arrangement, some costs may be:

    • Paid by the employer
    • Charged directly to employee accounts
    • Reflected through investment expenses
    • Shared in another way under the plan structure

    A strong explanation of retirement plan fees should therefore answer a practical employee question:

    “Am I paying this, is my employer paying it, or is it reflected somewhere else in the plan?”

    Employees should also be shown where they can review the current fee amounts.

    This provides greater clarity about how plan costs are allocated without oversimplifying the arrangement.

    3. Connect Fees to the Services They Support

    A fee is easier to understand when employees know what is associated with it.

    Depending on the workplace plan, applicable fees may support services such as:

    • Investment management
    • Plan administration
    • Recordkeeping
    • Account statements
    • Online account access
    • Employee education
    • Decision-making tools
    • Member support
    • Governance-related services
    • Other plan features

    CAPSA specifically recommends that fee information include descriptions of the services provided for applicable fees and expenses.

    This is an important distinction.

    The question should not be only:

    “How much does this cost?”

    Employees may also reasonably want to understand:

    “What am I receiving in connection with that cost?”

    Connecting retirement plan fees with services can create a more complete picture of the workplace retirement arrangement.

    4. Explain the Potential Long-Term Impact of Fees

    Fees and expenses reduce investment returns and may affect account balances over time.

    That does not mean employers should create fear around fees or suggest that the lowest-fee investment must automatically be the best choice.

    Instead, employees can be shown that fees are one consideration alongside:

    • Investment objectives
    • Risk
    • Diversification
    • Expected return
    • Investment strategy
    • Available services
    • Individual circumstances

    Where appropriate, employers may use approved illustrations or tools to demonstrate how retirement plan fees can affect long-term account balances.

    Any illustration should make clear that projected outcomes are not guaranteed.

    The purpose is education—not investment recommendation.

    5. Make Fee Information Easy to Find More Than Once

    Fee disclosure should not disappear after enrolment.

    Employees may receive information when joining the plan, but many will not remember every detail months or years later.

    Fee information can be reinforced through:

    • Plan booklets
    • Member portals
    • Annual statements
    • Benefit reviews
    • Employee education
    • Provider materials
    • Significant plan-change communication
    • Financial-wellness resources

    CAPSA’s guidance recommends providing fee and expense information when a capital accumulation plan is introduced, when material changes occur, and at least annually thereafter.

    Ongoing communication makes retirement plan fees easier to revisit when an employee actually needs the information.

    6. Avoid Unsupported “Cheapest” or “Best Value” Claims

    This is one of the most important communication safeguards.

    Employers should be cautious with statements such as:

    • “This is the cheapest plan.”
    • “Lower fees mean better investment results.”
    • “This plan gives you better value than other plans.”
    • “These fees will produce better retirement outcomes.”

    The Q&A source specifically warns against these types of statements unless they can be appropriately substantiated and accurately communicated in context.

    A safer and more useful approach is:

    Explain what employees pay, what services are associated with those costs, and where current information can be reviewed.

    Lower fees can be important, but cost alone does not necessarily determine whether a retirement arrangement provides appropriate value.

    7. Provide a Contact Point and Review Fees Regularly

    Employees should know where to go when they have questions about:

    • Fees
    • Statements
    • Investment options
    • Plan documents
    • Account information

    Employers should also review member-borne fees, provider arrangements, investment options, and associated services periodically as part of broader retirement plan governance.

    The employer review and employee communication processes should reinforce each other.

    If employees repeatedly ask the same fee question, that may indicate that communication needs improvement.

    If a provider arrangement changes, employee information may also need updating.

    Clear retirement plan fees communication should therefore be treated as an ongoing process rather than a one-time disclosure exercise.

    Why “Low Cost” Is Not the Same as “Good Value”

    Cost matters.

    But cost is not the only consideration.

    A retirement plan may also provide:

    • Investment choices
    • Administration
    • Digital tools
    • Member education
    • Account support
    • Recordkeeping
    • Financial-wellness resources
    • Other services

    CAPSA recommends that plan sponsors periodically consider whether member-borne fees are reasonable and competitive and whether they provide value to members, including factors such as net investment return and services.

    This means employees benefit from seeing cost and service together.

    A more balanced question is therefore:

    “What does the plan cost, what services are included, and how do those costs fit within the overall retirement arrangement?”

    That is more useful than reducing the conversation to “cheap” versus “expensive.”

    How Can Employers Keep Fee Information Accurate and Reliable?

    Fee communication should be grounded in current information.

    Employers can strengthen accuracy by:

    • Using current plan documents
    • Using current provider materials
    • Verifying fee terminology before publishing
    • Avoiding unsupported comparisons
    • Updating information when plan arrangements change
    • Distinguishing facts from promotional language
    • Making formal plan documents easy to locate
    • Providing a clear contact for follow-up questions

    For federally regulated defined contribution pension plans, OSFI also emphasizes that disclosure should be timely, understandable, and accurate and specifically identifies investment-management, account, and service-provider fees among information that should be disclosed to members.

    Requirements can differ by plan structure and jurisdiction, so employers should not assume that the same disclosure rules apply identically to every workplace retirement arrangement.

    What Questions Should Employees Be Able to Answer?

    After reading fee information, an employee should ideally be able to answer:

    What fees apply to my plan?

    The employee should know where the current plan-specific fee information is located.

    Which costs come from my account?

    Communication should distinguish employee-borne fees from costs paid by the employer or handled through other parts of the arrangement.

    What services are associated with the fees?

    Employees should be able to understand whether fees relate to investment management, administration, recordkeeping, member education, tools, or other services.

    Can fees affect my retirement savings?

    Yes. Fees reduce investment returns and may affect long-term balances, although fees should be considered alongside risk, diversification, investment objectives, return expectations, and available services.

    Who can answer my questions?

    Every communication should provide a clear contact point for questions about fees, investment options, statements, and plan documentation.

    Why Clear Fee Communication Matters to Employers

    Better fee communication may help employees understand how their workplace retirement plan operates and how costs interact with investments.

    It can also support stronger employer governance by creating a reason to periodically review:

    • Member-borne fees
    • Services
    • Providers
    • Investment options
    • Communication materials

    However, clearer retirement plan fees communication should not be presented as guaranteeing higher participation, better investment performance, greater employee trust, increased engagement, or improved retirement outcomes.

    Employee responses can differ based on financial circumstances, plan design, financial literacy, investment choices, and other factors.

    Transparency is valuable because it improves access to information—not because it guarantees a specific result.

    How Can Employees Compare Cost and Value More Thoughtfully?

    Employees should not necessarily make investment decisions based on one number.

    For example, a fee may need to be considered together with:

    • Fund objective
    • Risk level
    • Diversification
    • Investment management
    • Services
    • Net return
    • Available support

    The Financial Consumer Agency of Canada also notes that management fees reduce investment returns and that even relatively small fee differences can affect investment value over time.

    A workplace education program can explain these relationships without telling an individual employee which option to select.

    This keeps retirement plan fees education informative without crossing into personalized investment advice.

    Important Boundaries for Employers

    Fee-disclosure requirements may vary depending on:

    • Type of retirement arrangement
    • Province or jurisdiction
    • Federal or provincial regulation
    • Investment products
    • Provider contracts
    • Pension requirements
    • Securities requirements
    • Insurance requirements
    • Tax considerations

    Employers should rely on current plan and provider materials and obtain appropriate retirement-plan, legal, investment, tax, or compliance guidance where necessary.

    Employees who need advice about whether a particular fee structure, investment option, or retirement strategy is appropriate for them should be directed to appropriately qualified professionals.

    Need Help Making Retirement Plan Fees Easier to Understand?

    Clear retirement-plan communication can help employees understand what they pay, what services are associated with those costs, and where they can find current information.

    Open Access Limited may support employers with plan-specific fee information, enrolment resources, member materials, financial-wellness education, and support channels relating to eligible group retirement-plan members.

    Because fee structures and plan terms may differ, current plan-specific materials should always govern rather than broad statements about fees.

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6, Canada

    Toll-Free: 1-866-625-4777
    General: 416-364-8877
    Fax: 416-955-4878
    Email: inquiry@OpenAccessLtd.com
    Website: www.OpenAccessLtd.com

    
Retirement plan fees explained clearly for Canadian employees, including investment fees, administration, recordkeeping, services, and long-term savings impact.

    Frequently Asked Questions About Retirement Plan Fees

    Are Retirement Plan Fees Always the Same?

    No. Fee structures can vary depending on the plan, investment options, providers, services, and applicable arrangements.

    Do Lower Retirement Plan Fees Always Mean Better Results?

    No. Lower fees do not guarantee better investment or retirement outcomes. Fees should be considered alongside investment objectives, risk, diversification, expected returns, and available services.

    How Often Should Employees Receive Fee Information?

    For capital accumulation plans, CAPSA recommends fee and expense information at plan introduction, when material changes occur, and at least annually thereafter.

    Should Employers Compare Their Plan With Competitors?

    Employers should avoid unsupported claims such as being the “cheapest” or providing “better value.” Comparisons should be appropriately supported and communicated in context.

    Where Should Employees Look for Current Fee Information?

    Employees should use current plan-specific documents, statements, member portals, and approved provider information.

    Canadian employees reviewing retirement plan costs, investment management, administration, recordkeeping, education, and member support services.

    Final Thoughts

    Retirement plan fees should not feel like unexplained numbers buried inside an account statement.

    Employers can make fee information more useful by explaining what costs apply, who pays them, what services they support, how they may affect long-term savings, and where employees can find current information.

    The strongest approach is straightforward:

    Explain clearly. Show the services. Avoid unsupported claims. Keep information current. Provide human support.

    That creates a more transparent retirement-plan experience while keeping education separate from individualized financial advice.

    : Canadian employers comparing retirement plan fees with investment options, services, net returns, education, and employee support.

    References

    1. Canadian Association of Pension Supervisory Authorities — Guideline No. 3: Guideline for Capital Accumulation Plans
    2. Office of the Superintendent of Financial Institutions — Disclosure Requirements for Defined Contribution Pension Plans
    3. Office of the Superintendent of Financial Institutions — InfoPensions, Issue 34
    4. Financial Consumer Agency of Canada — Employer Pension Plans
    5. Open Access Limited — Current Group Retirement Plan and Plan-Specific Member Materials

  • How Can Businesses Use AI in Retirement Benefits Communication Responsibly?

    How Can Businesses Use AI in Retirement Benefits Communication Responsibly?

    Artificial intelligence is rapidly changing how organizations prepare, organize, and deliver information. For employers, AI in retirement benefits may create opportunities to make general employee communication clearer, faster, more accessible, and easier to maintain.

    AI-assisted tools may help draft plain-language explanations, frequently asked questions, enrolment reminders, educational summaries, or preliminary translations. They may also help HR teams identify recurring communication themes and prepare different versions of educational material for employees with different levels of financial literacy.

    But speed alone is not a retirement-plan communication strategy.

    Employee retirement benefits can involve personal financial information, plan rules, tax considerations, investment decisions, beneficiary information, contribution calculations, and long-term financial choices. An inaccurate AI-generated answer can therefore create more than a communication problem—it may create confusion, privacy concerns, employee mistrust, or governance risk.

    The strongest approach to AI in retirement benefits is not automation without limits. It is controlled assistance: AI supports a defined communication process while official plan documents, qualified professionals, privacy safeguards, and human judgment remain in control.

    Why AI in Retirement Benefits Requires Strong Governance

    Retirement-benefit communication is different from ordinary workplace content.

    An AI tool might produce a polished explanation that sounds authoritative even when the underlying information is incomplete, outdated, or inconsistent with the employer’s actual plan.

    Employees may also assume that a personalized-sounding response is financial advice when it is only general educational information.

    The risks become greater when sensitive employee information is entered into an AI system without appropriate approval.

    A responsible framework for AI in retirement benefits should therefore address four questions before a tool is used:

    • What is AI permitted to do?
    • What information may it access?
    • Who verifies its output?
    • When must an employee be directed to a human professional?

    Answering these questions before implementation creates a clearer boundary between useful automation and inappropriate reliance on AI.

    8 Essential Safeguards for AI in Retirement Benefits Communication

    1. Define Approved AI Use Cases Before Employees See the Content

    Employers should document where AI may—and may not—be used.

    Appropriate uses may include preparing first drafts of:

    • General retirement-plan FAQs
    • Enrolment reminders
    • Contribution education
    • Plain-language summaries
    • Employee newsletters
    • Educational follow-ups
    • Draft translations
    • General financial-wellness content

    The objective is to create a defined role for AI in retirement benefits, rather than allowing individual employees or departments to experiment with different tools without oversight.

    Employers should also document prohibited uses.

    For example, a general AI tool should not independently determine employee eligibility, calculate individual entitlements, select investments, or resolve disputed plan matters.

    A written acceptable-use framework can reduce inconsistent practices across HR, payroll, communications, and management teams.

    2. Approve AI Tools and Vendors Before They Are Used

    Not every AI platform handles information in the same way.

    Before approving a system, employers should understand:

    • Privacy terms
    • Security controls
    • Data-retention practices
    • Whether submitted information may be used for model training
    • Subcontractor arrangements
    • Data-storage locations
    • Access controls
    • Incident-notification procedures
    • Contractual responsibilities
    • Data-deletion options

    This review is especially important when AI in retirement benefits may interact with documents or information connected to employee financial programs.

    A free public AI account and an enterprise system with contractual privacy protections should not automatically be treated as equivalent.

    Vendor approval should form part of the organization’s broader technology, privacy, cybersecurity, and procurement process.

    3. Keep Personal Employee Information Out of Unapproved AI Systems

    One of the most important safeguards is data minimization.

    Unless a system has specifically been approved for handling the information involved, employees should not enter identifiable retirement-plan information into an AI tool.

    Examples may include:

    • Employee names
    • Social Insurance Numbers
    • Payroll information
    • Account balances
    • Contribution histories
    • Beneficiary details
    • Health information
    • Personal addresses
    • Individual investment selections
    • Individual financial circumstances

    Using AI in retirement benefits does not require exposing personal data simply to generate general educational communication.

    Where possible, employers should work with generalized, anonymized, aggregated, or de-identified information and approved source documents.

    This reduces privacy risk while still allowing AI to support communication workflows.

    4. Ground Every AI Draft in Authoritative Plan Information

    AI-generated retirement information should never become its own source of truth.

    The source of truth should remain:

    • Current plan documents
    • Approved provider materials
    • Official employer policies
    • Current enrolment materials
    • Applicable regulatory guidance
    • Approved employee communications

    When using AI in retirement benefits, employers should provide or reference authoritative materials whenever the approved system allows it and then verify the resulting draft against those sources.

    If an AI-generated explanation conflicts with an official plan document, the official document must govern.

    This principle is particularly important because generative AI can produce statements that are confident, readable, and incorrect at the same time.

    Accuracy should therefore be validated—not assumed.

    5. Require Qualified Human Review Before Distribution

    Human review is not an optional final glance.

    Someone with appropriate retirement-plan knowledge should review AI-assisted communication for:

    • Accuracy
    • Completeness
    • Tone
    • Accessibility
    • Consistency
    • Plan-specific terminology
    • Regulatory sensitivity
    • Potential misunderstanding

    Translated materials should also receive appropriate language review.

    A well-designed process for AI in retirement benefits should clearly identify who has authority to approve employee-facing material.

    For example, HR may prepare the draft, a retirement-plan specialist may verify plan information, and communications staff may review readability before publication.

    The final version should have a clear human owner.

    AI can assist with production. Accountability should remain human.

    6. Preserve Employee Choice and Access to Human Support

    AI-assisted communication should make retirement information easier to understand—not harder to question.

    Every employee-facing AI-assisted resource should provide a clear pathway to human support.

    Employees should know:

    • Where to ask plan-specific questions
    • Who can explain plan rules
    • Where official plan documents are located
    • How to obtain individual assistance
    • When professional advice may be appropriate

    Employers using AI in retirement benefits should also explain that general educational material is not individualized financial, investment, tax, or legal advice.

    A chatbot, summary, or AI-generated FAQ should never create the impression that an employee has received a personalized recommendation simply because the language sounds conversational.

    Human recourse is part of responsible communication.

    7. Keep AI Away From High-Risk Individual Decisions

    There is an important difference between explaining information and making decisions.

    A general-purpose AI system should not be treated as the final authority for questions such as:

    • Is this employee eligible?
    • What contribution should this employee make?
    • Which investment should this person select?
    • What is this employee’s risk profile?
    • Should this employee retire now?
    • What are the individual’s tax consequences?
    • How should beneficiary or estate issues be handled?
    • How should a disputed plan matter be resolved?

    These issues may require the plan provider or qualified legal, tax, investment, privacy, employment, cybersecurity, or retirement professionals.

    The value of AI in retirement benefits is greatest when the technology helps explain approved information—not when it replaces professional judgment.

    This boundary should be clearly documented and communicated internally.

    8. Monitor, Document, and Improve AI-Assisted Communication

    Responsible AI use is not a one-time approval exercise.

    Employers should maintain records of:

    • Approved AI tools
    • Approved use cases
    • Source documents
    • Draft versions
    • Final approvals
    • Employee questions
    • Recurring errors
    • Corrections
    • Complaints
    • Privacy incidents
    • Review dates

    Regular monitoring of AI in retirement benefits can reveal whether employees are actually understanding the material.

    For example, if the same question repeatedly reaches HR after an AI-assisted FAQ is published, the issue may not be employee engagement. The communication itself may be unclear.

    Employers should use these patterns to improve future education and determine where human support is more valuable than additional automation.

    Where AI Can Add Real Value to Retirement Communication

    Used appropriately, AI can help employers scale communication without making every message generic.

    Potential applications include:

    Plain-Language Education

    Complex plan information can be converted into an initial plain-language draft that is subsequently reviewed against official documents.

    Frequently Asked Questions

    Recurring employee questions can help HR identify topics that deserve clearer education.

    Enrolment and Contribution Reminders

    AI may assist in drafting timely reminders while approved HR and provider information remains authoritative.

    Translation Support

    AI may prepare preliminary translations, provided qualified language review occurs before employee distribution.

    Financial-Literacy Adaptation

    The same approved concept can be drafted at different reading levels to help employees with varying financial knowledge.

    Accessibility Support

    AI-assisted workflows may help create alternative formats, subject to final accessibility and accuracy review.

    The strongest use of AI in retirement benefits is therefore not replacing people. It is helping people communicate approved information more clearly and consistently.

    Where AI Should Never Be the Final Authority

    Employers should draw a visible line between educational assistance and individual decision-making.

    AI should not independently determine:

    • Plan eligibility
    • Contribution calculations
    • Employer matching
    • Vesting
    • Locking-in requirements
    • Investment suitability
    • Risk tolerance
    • Individual tax outcomes
    • Beneficiary decisions
    • Withdrawal strategies
    • Retirement dates
    • Legal interpretations
    • Complaint resolution

    This distinction protects both employees and employers.

    The more consequential a decision becomes, the stronger the need for authoritative plan information and qualified human involvement.

    A Practical AI-Assisted Retirement Communication Workflow

    Businesses can make the process easier to manage by establishing a repeatable workflow.

    Step 1: Start With an Approved Communication Need

    Identify the employee question or educational objective.

    Step 2: Select Authoritative Source Material

    Use current plan documents, provider resources, approved policies, and appropriate regulatory guidance.

    Step 3: Use Only an Approved AI Tool

    Do not upload sensitive employee information unless the tool and use case have specifically been approved.

    Step 4: Generate the Draft

    Ask the AI system to simplify, organize, summarize, translate, or restructure the approved information.

    Step 5: Conduct Qualified Human Review

    Check every substantive statement against the source documents.

    Step 6: Review Privacy, Tone, and Accessibility

    Confirm that the communication does not expose personal information or imply personalized advice.

    Step 7: Approve and Publish

    Maintain a record of the approved final version.

    Step 8: Provide Human Support

    Give employees a clear contact point for questions.

    This workflow turns AI in retirement benefits from an informal productivity experiment into a controlled communication process.

    What Employers Should Tell Employees About AI-Assisted Content

    Transparency can strengthen trust.

    Employers do not necessarily need to make every communication about the technology itself, but employees should understand the limits of the information they receive.

    A practical disclosure might explain that:

    AI-assisted tools may support the preparation of general educational content, but official plan documents and approved provider information remain authoritative. Employees should contact the appropriate plan-support channel for questions about their individual circumstances.

    The goal is not to create fear around AI.

    The goal is to ensure employees understand the difference between general education and individualized guidance.

    Why Responsible AI Matters to Business Owners

    AI can make communication faster, but speed without governance can create new administrative problems.

    A structured approach to AI in retirement benefits may help employers:

    • Create more consistent communication
    • Reduce repetitive drafting work
    • Identify recurring employee questions
    • Improve accessibility
    • Support financial education
    • Maintain stronger documentation
    • Reduce uncontrolled AI use
    • Strengthen privacy awareness
    • Preserve human accountability

    It may also help HR teams spend less time repeatedly answering basic questions and more time assisting employees whose circumstances require human attention.

    However, AI should not be assumed to improve employee confidence automatically.

    The quality of the outcome depends on the quality of the source material, the approved technology, human review, workforce needs, and access to qualified assistance.

    Important Privacy, Cybersecurity, and Governance Boundaries

    Using AI in retirement benefits may create considerations involving:

    • Privacy
    • Cybersecurity
    • Accessibility
    • Employment practices
    • Procurement
    • Intellectual property
    • Record retention
    • Contracts
    • Data location
    • Legal requirements
    • Regulatory obligations

    Employers should establish written internal rules addressing approved tools, permitted uses, prohibited information, human-review requirements, incident escalation, recordkeeping, and employee-facing transparency.

    Policies should also be reviewed as AI systems and organizational practices change.

    General AI frameworks can provide useful retirement plan governance principles, but they should not be treated as a substitute for professional advice on the employer’s specific legal obligations.

    How Open Access Limited May Support Retirement-Plan Communication

    Open Access Limited may support the retirement-plan information underlying an employer’s communication process through official plan information, plan-specific education resources, enrolment materials, and member-support channels.

    When employers use AI in retirement benefits to prepare general communication, drafts should be checked against current plan documents and approved provider information before employees receive them.

    Employees with plan-specific questions should be directed to the appropriate human support channel.

    Questions involving individual legal, tax, investment, employment, privacy, or other professional circumstances should be referred to appropriately qualified professionals.

    This approach allows AI-assisted drafting to complement authoritative plan information without positioning technology as the final decision-maker.

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6
    Canada

    Toll-Free: 1-866-625-4777
    General: 416-364-8877
    Fax: 416-955-4878
    Email: inquiry@OpenAccessLtd.com
    Website: www.OpenAccessLtd.com

    Canadian HR and retirement professionals reviewing AI-assisted employee retirement communication for accuracy, privacy, accessibility, governance, and human support.

    Frequently Asked Questions About AI in Retirement Benefits

    Can employers use AI to explain retirement benefits?

    Yes. AI may assist with drafting general explanations, FAQs, reminders, summaries, and educational content when appropriate safeguards, authoritative sources, and qualified human review are used.

    Can employees enter their account information into an AI chatbot?

    Employees should not enter identifiable financial or personal information into an AI tool unless that specific system and use have been approved for handling the information.

    Can AI recommend an investment option to an employee?

    A general-purpose AI tool should not be treated as the final authority for individualized investment recommendations, risk-profile decisions, or retirement strategies.

    Should AI-generated retirement communication be reviewed?

    Yes. Qualified human review should confirm accuracy, completeness, tone, accessibility, and consistency with current official plan information before distribution.

    Final Thoughts

    The future of employee communication will almost certainly include more artificial intelligence.

    But responsible AI in retirement benefits should make retirement communication more reliable—not merely faster.

    The most effective employers will combine technology with authoritative information, privacy protection, qualified human review, transparent boundaries, documentation, and accessible human support.

    AI can draft.

    AI can organize.

    AI can simplify.

    But responsibility for AI retirement-benefit communication should remain with people.

    
AI in retirement benefits communication with privacy safeguards, authoritative plan information, human review, governance, and employee support.

    REFERENCES

    1.Office of the Privacy Commissioner of Canada — AI, Privacy, and Your Business

    2.Canadian Federal, Provincial and Territorial Privacy Regulators — Principles for Responsible, Trustworthy and Privacy-Protective Generative AI Technologies

    3. Canadian Centre for Cyber Security — Generative Artificial Intelligence: Risks and Mitigation Considerations

    4. National Institute of Standards and Technology — Artificial Intelligence Risk Management Framework: Generative AI Profile

    5.Treasury Board of Canada Secretariat — Guide on the Use of Generative Artificial Intelligence

    6. CAPSA — Guideline No. 3: Guideline for Capital Accumulation Plans

    7. Open Access Limited — Financial Wellness Resources, Plan-Specific Enrolment Resources and Member Support

  • How Can Businesses Protect Employee Retirement Plan Data from Cyber and Privacy Risks

    How Can Businesses Protect Employee Retirement Plan Data from Cyber and Privacy Risks

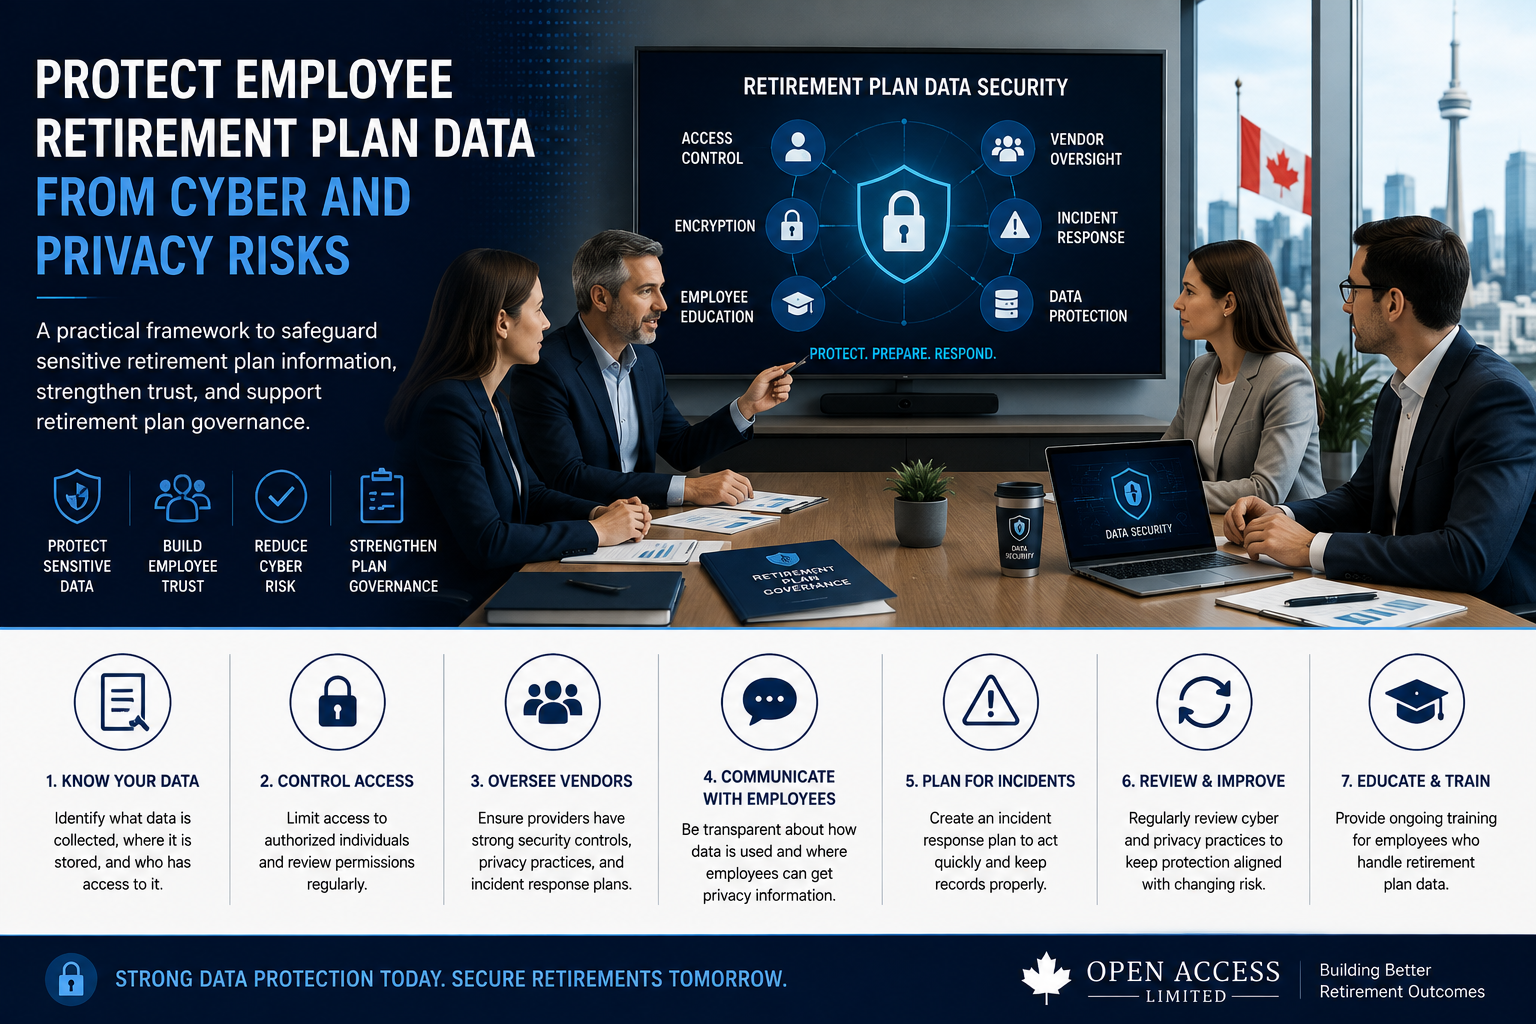
    Retirement plan data security is becoming a critical part of workplace retirement-plan management.

    Retirement plans contain highly sensitive employee information, including identity details, employment records, contribution history, beneficiary information, account values, contact details, and financial decision data.

    As retirement-plan administration becomes more digital, employers increasingly rely on payroll systems, recordkeepers, advisers, administrators, investment providers, and technology platforms. Each connection may create additional data-handling responsibilities and operational risk.

    For business owners, cyber and privacy risk is not only an IT concern. It is also a governance, employee trust, vendor oversight, business continuity, and reputational issue.

    A practical retirement plan data security strategy should focus on preventing avoidable problems, preparing for incidents, assigning clear responsibilities, and communicating responsibly when employee information is involved.

    Why Does Retirement Plan Data Security Matter

    Employees trust their employers and retirement-plan partners with highly personal financial information.

    If this information is lost, misused, exposed, or accessed without authorization, the consequences may include:

    • Loss of employee trust
    • Operational disruption
    • Regulatory concern
    • Reputational harm
    • Additional administrative cost
    • Financial loss
    • Identity-related risks
    • Delays in retirement-plan administration

    Strong retirement plan data security also supports better plan governance.

    It helps employers ask more informed questions of service providers, document responsibilities, control access, prepare for incidents, and demonstrate that retirement-plan information is being managed with care.

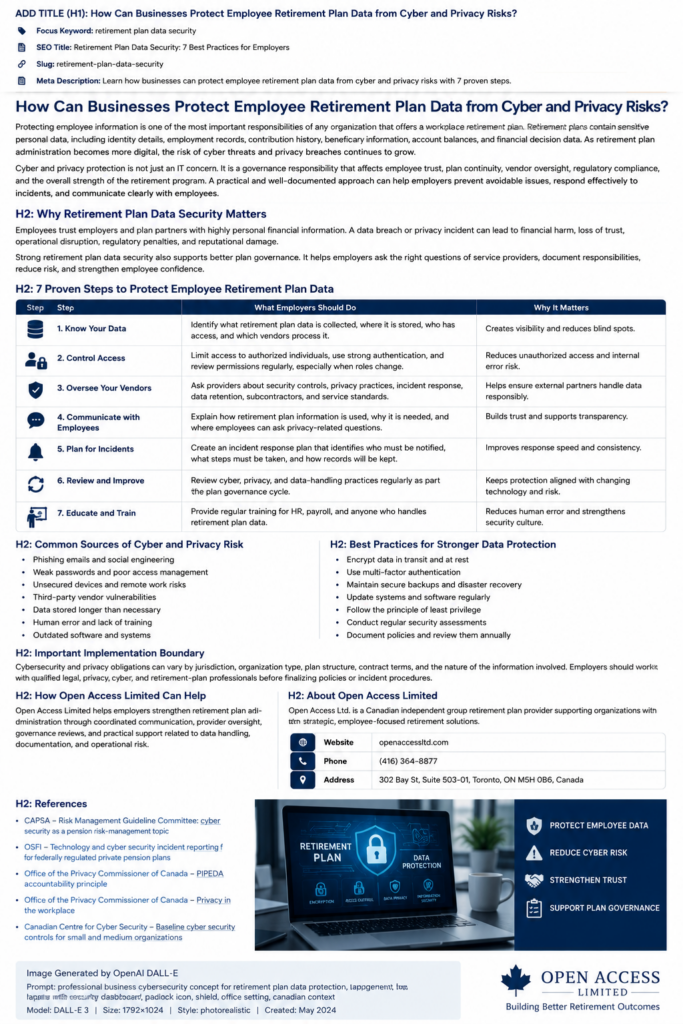
    7 Proven Steps to Strengthen Retirement Plan Data Security

    1.Create a Complete Retirement Data Inventory

    Employers should begin by identifying what retirement-plan information is collected, where it is stored, who can access it, and which external providers process it.

    The inventory may include:

    • Employee identification information
    • Payroll records
    • Contribution history
    • Beneficiary details
    • Account balances
    • Contact information
    • Investment selections
    • Plan-enrolment records
    • Retirement-related forms
    • Employee communication history

    A clear data inventory creates visibility and reduces blind spots.

    Without this information, employers may not know where sensitive records are stored or which parties are responsible for protecting them.

    2. Limit Access to Authorized Individuals

    Access to retirement-plan data should be limited to employees and providers who require it for legitimate business purposes.

    Employers should review access permissions regularly, especially when employees change roles, leave the organization, or no longer require access.

    Practical access controls may include:

    • Unique user accounts
    • Strong passwords
    • Multi-factor authentication
    • Role-based permissions
    • Regular access reviews
    • Prompt removal of inactive accounts
    • Secure remote-access procedures
    • Documented approval for elevated access

    Limiting access reduces unauthorized use, internal errors, and unnecessary exposure of employee information.

    3. Strengthen Retirement-Plan Vendor Oversight

    Retirement plans may involve several outside organizations, including recordkeepers, payroll providers, advisers, investment platforms, administrators, and technology companies.

    Employers should ask providers about:

    • Security controls
    • Privacy policies
    • Data-storage locations
    • Incident-response procedures
    • Subcontractors
    • Data-retention practices
    • Service standards
    • Business-continuity plans
    • Employee access controls
    • Breach-notification procedures

    Vendor oversight is a core part of retirement plan data security because outside providers may process or store sensitive employee information.

    Employers should also understand who is responsible for responding when a provider experiences a security incident.

    4. Communicate Clearly With Employees

    Employees should understand how their retirement-plan information is collected, why it is needed, how it is used, and where they can ask privacy-related questions.

    Clear communication can explain:

    • What information is collected
    • Why the information is required
    • Which providers may process it
    • How employees can update their information
    • How privacy questions are handled
    • What employees should do if they notice suspicious activity
    • Where plan statements and notices are delivered

    Transparent communication builds trust and helps employees understand their own role in protecting retirement-plan information.

    Employees should also be reminded not to share passwords, respond to suspicious messages, or send sensitive documents through unsecured channels.

    5. Create a Cyber and Privacy Incident Plan

    Employers should prepare for a potential privacy or cyber incident before one occurs.

    A practical incident plan should identify:

    • Who must be notified internally
    • Which provider contacts should be involved
    • Who will assess the incident
    • How affected systems will be protected
    • What records must be preserved
    • How employees will be informed
    • When legal or privacy professionals should be contacted
    • How follow-up actions will be documented
    • Who will approve public or employee communication

    Incident planning improves response speed and consistency.

    It also reduces the risk that employees receive conflicting or incomplete information during a stressful event.

    6. eview Data-Protection Practices Regularly

    Technology, cyber threats, employee roles, providers, and retirement-plan systems change over time.

    For this reason, retirement plan data security should be reviewed as part of the regular retirement-plan governance cycle.

    A review may include:

    • User-access permissions
    • Provider security reports
    • Privacy procedures
    • Employee training
    • Incident-response contacts
    • Data-retention practices
    • Backup systems
    • Business-continuity procedures
    • Unresolved security issues
    • Changes in technology platforms

    Ongoing review helps ensure that protection remains aligned with changing risks and business operations.

    7. Train Employees Who Handle Retirement Data

    Human error is a common source of cyber and privacy risk.

    Employees in HR, payroll, finance, benefits administration, and management should receive practical training on how to handle retirement-plan information securely.

    Training may cover:

    • Recognizing phishing emails
    • Secure password practices
    • Multi-factor authentication
    • Safe document sharing
    • Secure remote work
    • Reporting suspicious activity
    • Protecting printed records
    • Verifying requests for employee information
    • Escalating potential privacy incidents

    Regular education helps build a stronger security culture and reduces the risk that sensitive information is exposed through avoidable mistakes

    Common Sources of Cyber and Privacy Risk

    Employers should be aware of several common risk areas.

    These may include:

    • Phishing and social-engineering attacks
    • Weak passwords
    • Shared user accounts
    • Excessive system access
    • Unsecured laptops or mobile devices
    • Remote-work vulnerabilities
    • Outdated software
    • Vendor-system weaknesses
    • Incorrect employee data
    • Lost documents
    • Improper file sharing
    • Data retained longer than necessary
    • Inadequate employee training

    A strong retirement plan data security process does not rely on one control. It combines technology, policies, training, oversight, and clear accountability

    How Does Data Protection Support Retirement Plan Governance

    Cyber and privacy protection should be integrated with broader retirement plan governance.

    Employers can include data-protection questions in provider reviews, annual governance meetings, service-level discussions, and risk-management checklists.

    This approach helps ensure that security is not treated as a separate technical issue.

    It also creates a documented process for reviewing responsibilities, monitoring providers, and following up on unresolved concerns.

    Businesses can connect this work with their broader retirement plan governance framework to create more consistent oversight.

    Important Implementation Boundaries

    Cybersecurity and privacy obligations may vary based on:

    • Jurisdiction
    • Type of organization
    • Plan structure
    • Contract terms
    • Nature of the information
    • Service-provider arrangements
    • Applicable privacy laws
    • Regulatory requirements
    • The seriousness of an incident

    Employers should work with qualified legal, privacy, cyber-security, and retirement-plan professionals before finalizing policies or incident procedures.

    The employer’s role is to establish responsible processes and oversight—not to make legal conclusions without appropriate advice.

    How Open Access Limited Can Help

    Open Access Limited can help employers create a clearer and more coordinated retirement-plan administration process.

    Support may include:

    • Employee communication
    • Provider coordination
    • Plan-governance reviews
    • Documentation support
    • Operational-risk discussions
    • Data-handling process reviews
    • Retirement-plan education
    • Service-provider oversight

    A coordinated approach can help businesses improve retirement plan data security, strengthen employee confidence, and prepare for unexpected incidents.

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6
    Canada

    Phone: (416) 364-8877
    Toll-Free: 1-866-625-4777
    Email: inquiry@openaccessltd.com
    Website: OpenAccessLtd.com

    Canadian business leaders reviewing retirement plan data security, cyber risk, employee privacy, vendor oversight, access controls, incident response, and retirement plan governance.

    Final Thoughts

    Protecting employee retirement-plan information requires more than installing security software.

    Employers need a practical framework that includes data inventories, controlled access, vendor oversight, transparent employee communication, incident planning, regular reviews, and employee training.

    Strong retirement plan data security can protect sensitive information, strengthen retirement-plan governance, reduce operational risk, and improve employee trust.

    The most effective approach is clear, documented, regularly reviewed, and proportionate to the organization’s size, plan structure, and risk profile.

    Canadian employers reviewing retirement plan data security, cyber risk, employee privacy, vendor oversight, access controls, incident planning, and retirement plan governance.

    References

    CAPSA — Cyber Security as a Pension Risk-Management Topic

    OSFI — Technology and Cyber Security Incident Reporting for Federally Regulated Private Pension Plans

    Office of the Privacy Commissioner of Canada — PIPEDA Accountability Principle

    Office of the Privacy Commissioner of Canada — Privacy in the Workplace

    Canadian Centre for Cyber Security — Baseline Cyber Security Controls for Small and Medium Organizations

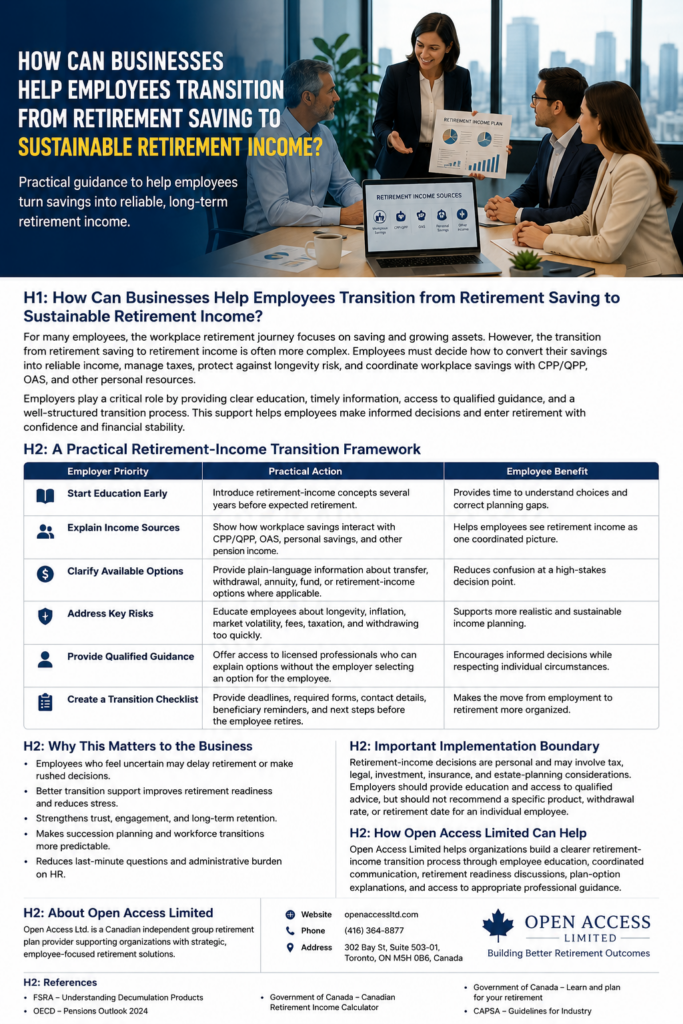
  • How Can Businesses Help Employees Transition from Retirement Saving to Sustainable Retirement Income?

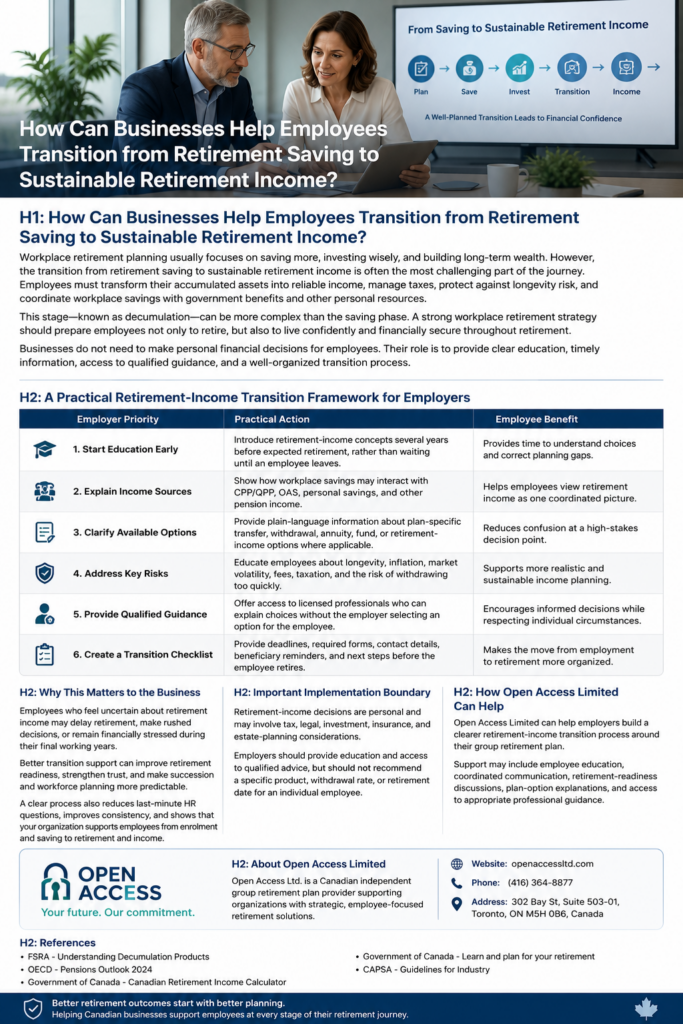
    How Can Businesses Help Employees Transition from Retirement Saving to Sustainable Retirement Income?

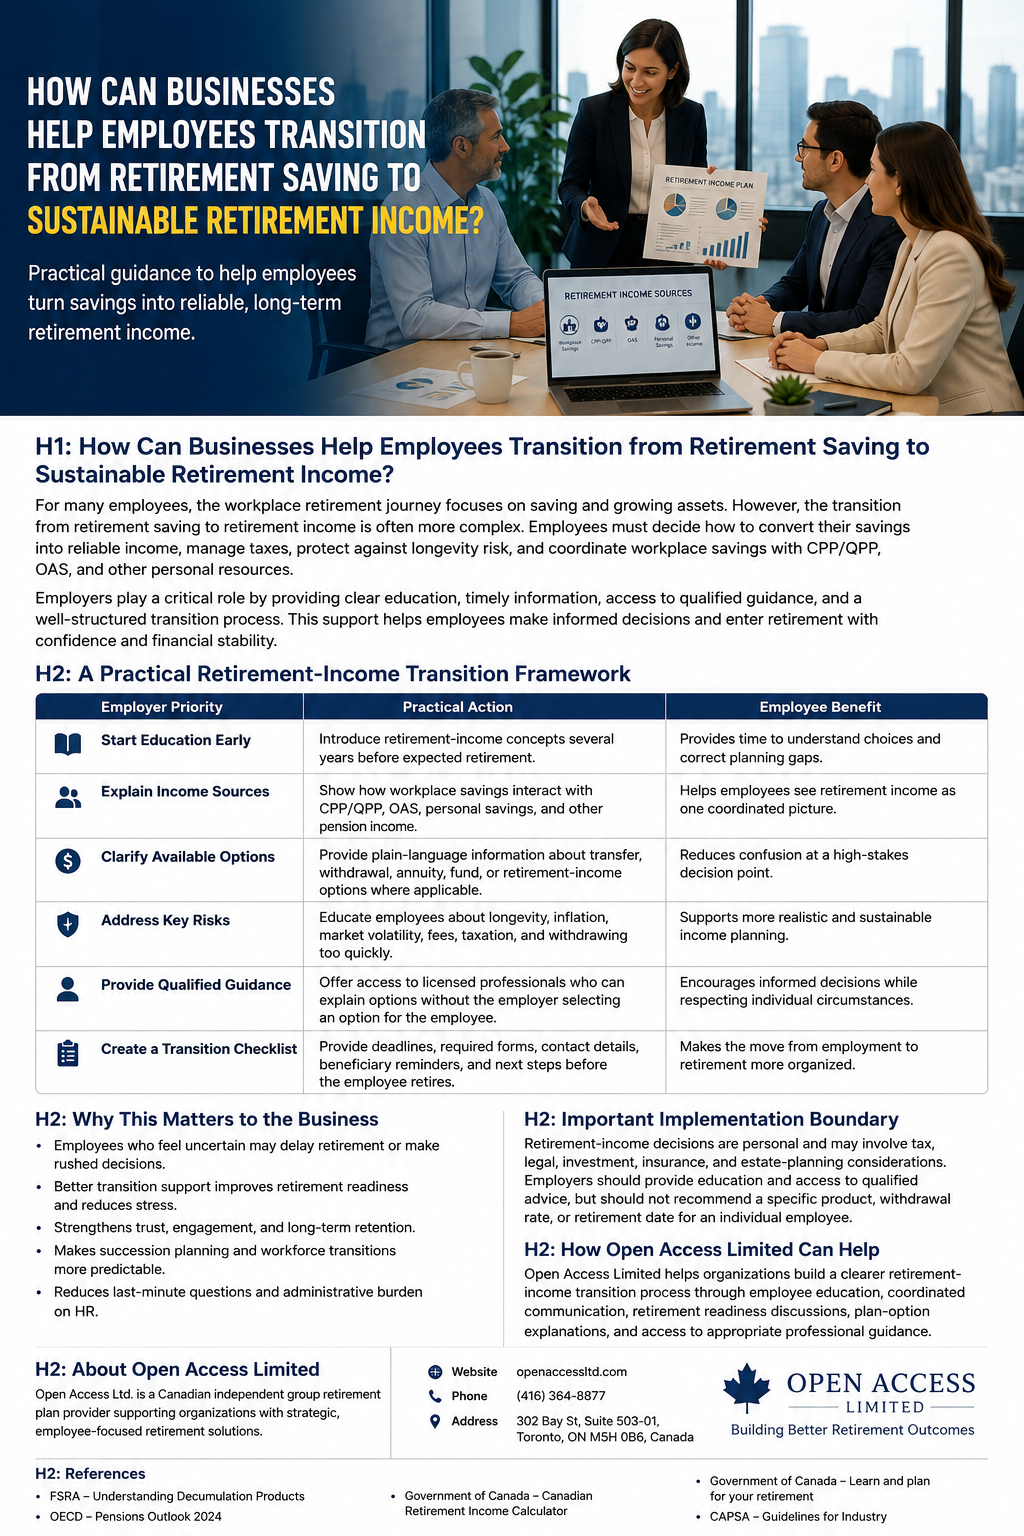
    Sustainable retirement income is becoming an important part of workplace retirement planning. For many employees, most retirement education focuses on accumulation—contributing to a workplace plan, selecting investments, and building long-term savings.

    However, reaching retirement creates a different set of decisions.

    Employees must determine how to convert accumulated savings into reliable income, manage taxation, protect against longevity risk, respond to inflation and market volatility, and coordinate workplace savings with public pensions and personal financial resources.

    This stage is often called decumulation. It can be more complicated than saving because employees may need to make decisions that affect their financial security for the rest of their lives.

    A strong workplace retirement strategy should therefore prepare employees not only to reach retirement, but also to create sustainable retirement income after employment ends.

    Businesses do not need to make personal financial decisions for employees. Their role is to provide clear education, timely information, access to qualified guidance, and a well-organized transition process

    Why Is the Transition to Sustainable Retirement Income Important?

    Employees may spend decades building retirement savings without receiving enough guidance about how those savings will eventually provide income.

    Retirement income may come from several sources, including:

    • Workplace retirement plans
    • CPP or QPP
    • Old Age Security
    • Personal RRSPs or other savings
    • Pension income
    • Investment accounts
    • Annuities or retirement-income funds
    • Other personal or family resources

    When these sources are considered separately, employees may find it difficult to understand their complete financial position.

    Effective sustainable retirement income planning helps employees view these resources as one coordinated picture.

    It also helps employees understand that retirement income must often last for many years while managing inflation, market changes, fees, taxation, health-related costs, and unexpected expenses.

    7 Proven Ways Employers Can Support Sustainable Retirement Income

    1. Start Retirement-Income Education Early

    Retirement-income education should begin several years before an employee expects to retire.

    Waiting until an employee submits a retirement notice can create unnecessary pressure. Employees may not have enough time to understand their choices, correct contribution gaps, review beneficiaries, or seek professional advice.

    Employers can introduce concepts such as retirement income sources, withdrawal planning, taxation, inflation, longevity, and plan-specific options through workshops, webinars, employee guides, and retirement-readiness discussions.

    Early education gives employees time to make informed decisions and prepare for sustainable retirement income gradually.

    2. Explain How Different Income Sources Work Together

    Employees should understand how workplace retirement savings may interact with CPP or QPP, Old Age Security, personal savings, pension income, and other resources.

    Employers should not calculate or recommend an individual retirement-income strategy. However, they can provide general education showing how different income sources may form part of a broader retirement plan.

    This helps employees avoid viewing their workplace account as their only source of income.

    A coordinated approach can improve financial awareness and help employees ask better questions when speaking with a qualified professional.

    3. Clarify Available Retirement-Plan Options

    Options

    Employees approaching retirement should receive clear, plain-language information about the options available under their specific workplace plan.

    Depending on the plan, options may involve:

    • Remaining in the existing plan
    • Transferring assets
    • Moving funds to an eligible retirement-income vehicle
    • Purchasing an annuity
    • Establishing scheduled withdrawals
    • Selecting available fund or income options
    • Completing required forms before retirement

    Not every option is available under every plan.

    Employers should work with their plan provider to ensure information is accurate, timely, and consistent.

    Clear explanations can reduce confusion at a high-stakes decision point and support more confident sustainable retirement income planning

    4. Educate Employees About Key Retirement Risks

    Employees need to understand that retirement-income planning involves several risks.

    These may include:

    • Longevity risk
    • Inflation
    • Market volatility
    • Investment fees
    • Taxation
    • Unexpected expenses
    • Withdrawing money too quickly
    • Holding an unsuitable investment mix
    • Failing to update beneficiaries
    • Losing track of retirement accounts

    Employers can offer general education about these risks without recommending a specific withdrawal rate, investment product, or retirement date.

    Risk awareness helps employees understand why sustainable income requires ongoing planning rather than a single decision made on the day they retire.

    5. Provide Access to Qualified Professional Guidance

    Retirement-income decisions may involve tax, investment, insurance, legal, and estate-planning considerations.

    Employers should not select a product or financial strategy for an employee.

    Instead, they can provide access to licensed and qualified professionals who are able to discuss individual circumstances.

    Professional guidance can help employees understand their available choices, ask appropriate questions, and evaluate how workplace savings fit into their broader retirement goals.

    This supports informed decisions while respecting the boundary between employer education and personalized financial advice.

    6.Create a Retirement Transition Checklist

    A transition checklist can make the move from employment to retirement more organized.

    The checklist may include:

    • Required forms
    • Important deadlines
    • Plan-provider contact information
    • Beneficiary review reminders
    • Personal contact-information updates
    • Information about account access
    • Available education sessions
    • Public pension resources
    • Professional guidance contacts
    • Next steps after employment ends

    Employees should receive this checklist before their final working day.

    A clear process can reduce last-minute questions, improve consistency, and help HR teams support employees more efficiently.

    7. Continue Support Beyond the Initial Retirement Decision

    The transition to sustainable retirement income is not always completed through one meeting or one form.

    Employees may need time to review their options, consult family members, speak with professionals, and coordinate several retirement-income sources.

    Where appropriate, employers and plan providers can maintain a structured communication process that explains deadlines, account access, and available support.

    This does not mean the employer remains responsible for the employee’s personal financial decisions.

    It means the organization provides a clear and respectful transition from workplace saving to retirement income.

    Why Does Retirement-Income Support Matter to the Business

    Employees who feel uncertain about retirement income may postpone retirement, make rushed decisions, or remain financially stressed during their final working years.

    Better transition support can improve retirement readiness, strengthen employee confidence, and make succession planning more predictable.

    A clear process may also:

    • Reduce last-minute HR questions
    • Improve communication consistency
    • Support workforce planning
    • Strengthen trust in the retirement program
    • Demonstrate long-term employer support
    • Reduce confusion during retirement transitions

    Employers that support the complete retirement journey—from enrolment and accumulation to retirement and income—can demonstrate that their workplace plan offers long-term value.

    This approach also connects naturally with broader retirement readiness workforce planning strategies.

    mportant Implementation Boundaries

    Retirement-income decisions are personal.

    They may involve taxation, investment management, insurance, pension legislation, estate planning, and family circumstances.

    Employers should provide education and access to qualified guidance, but should not recommend:

    • A specific investment product
    • A particular withdrawal rate
    • A retirement date
    • An annuity or income fund
    • A personal tax strategy
    • A specific asset-transfer decision

    Plan rules and retirement-income options may also vary depending on the type of workplace retirement plan and the employee’s circumstances.

    Employers should coordinate communication with their plan provider and seek appropriate legal, tax, pension, investment, or insurance advice when required.

    Strong retirement plan governance can help ensure that employee communication remains accurate, consistent, and appropriately documented.

    How Open Access Limited Supports Sustainable Retirement Income

    Open Access Limited can help employers create a clearer retirement-income transition process around their group retirement plan.

    Support may include:

    • Employee retirement education
    • Retirement-readiness discussions
    • Coordinated plan communication
    • Explanations of available plan options
    • Transition checklists
    • Provider coordination
    • Access to appropriate professional guidance
    • Employee-focused retirement solutions

    Open Access Limited helps employers support employees throughout the full retirement journey—from enrolment and saving to retirement and income.

    A structured approach can improve employee understanding, support better decisions, reduce administrative confusion, and help employees prepare for sustainable retirement income.

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6
    Canada

    Phone: (416) 364-8877
    Toll-Free: 1-866-625-4777
    Email: inquiry@openaccessltd.com
    Website: OpenAccessLtd.com

    Canadian employers discussing sustainable retirement income planning, employee retirement benefits, and retirement transition strategies in a professional office setting.

    Final Thoughts

    Helping employees transition from retirement saving to sustainable retirement income requires more than providing a workplace savings plan.

    Employees need early education, clear explanations of income sources, understandable plan options, risk awareness, professional guidance, and an organized transition process.

    Employers should not make personal financial decisions for employees. However, they can create a supportive framework that helps employees understand their choices and prepare for retirement with greater confidence.

    A well-designed retirement-income transition process can strengthen retirement readiness, reduce financial stress, support workforce planning, and demonstrate that the organization values employees throughout every stage of their retirement journey.

    Canadian employers helping employees transition from retirement saving to sustainable retirement income through education, risk planning, qualified guidance, and coordinated retirement support.

    References

    FSRA — Understanding Decumulation Products
    https://www.fsrao.ca/

    OECD — Pensions Outlook 2024
    https://www.oecd.org/

    Government of Canada — Canadian Retirement Income Calculator
    https://www.canada.ca/en/services/benefits/publicpensions.html

    Government of Canada — Learn and Plan for Your Retirement
    https://www.canada.ca/en/services/finance/pensions.html

    CAPSA — Guidelines for Industry
    https://www.capsa-acor.org/

  • What Is a Common Mistake Businesses Make When Implementing Retirement Plans for Employees?

    Why Retirement Plan Strategy Matters

    A common challenge businesses may face when implementing retirement plans is treating them as a standard employee benefit rather than as part of a broader workforce strategy.

    In today’s evolving labour market, employees increasingly value benefits that support long-term financial well-being. As a result, retirement plans are often viewed as an important component of overall compensation and employee experience.

    Common Mistakes Businesses Make With Retirement Plans
    Some organizations implement retirement programs with:

    • Limited customization
    • Minimal employer contributions
    • Generic plan structures
    • Limited alignment with workforce needs

    When retirement plans are not tailored to employee priorities, workers may perceive them as having limited relevance to their long-term financial goals.

    The Importance of Aligning Benefits With Workforce Needs

    Research suggests employee benefits tend to be more effective when they align with workforce priorities and are supported by a clearly defined value proposition.

    An effective retirement program is often designed with objectives such as:

    • Supporting employee financial wellness
    • Improving employee retention
    • Encouraging long-term workforce stability
    • Enhancing overall employee engagement

    Key Factors in Effective Retirement Plan Design

    Several factors may influence the effectiveness of a retirement program, including:

    • Contribution structures
    • Vesting schedules
    • Investment options
    • Workforce demographics
    • Employee financial priorities

    When these elements are thoughtfully aligned,retirement plans may better support both employee satisfaction and organizational objectives.

    Why Some Employers Work With Retirement Advisory Firms

    Because retirement outcomes can vary based on plan structure and implementation, some organizations choose to work with experienced retirement advisory firms to help design customized strategies aligned with business and workforce goals.

    For example, Open Access Limited works with employers across Ontario and Canada to help develop retirement program structures focused on employee financial well-being and long-term organizational alignment.

    Frequently Asked Questions

    What is a common mistake employers make with retirement plans?

    A common mistake is treating retirement plans as a generic employee benefit instead of aligning them with workforce needs and long-term business goals.

    Why should retirement plans be customized?

    Customized employee retirement plans may better support employee financial wellness, engagement, and retention by addressing workforce-specific priorities.

    What makes a retirement plan effective?

    Effective retirement plans often include thoughtful contribution structures, investment options, and alignment with employee financial goals.

    Can retirement benefits improve employee retention?

    Retirement benefits may contribute to retention efforts by supporting long-term financial security and improving overall employee satisfaction.

    Final Thoughts

    Retirement plans are often most effective when they are treated as part of a broader workforce and employee well-being strategy rather than as a generic benefit offering.

    Organizations that thoughtfully design retirement programs around workforce needs, financial wellness goals, and long-term business objectives may be better positioned to support employee engagement, attraction, and retention.

    Retirement Plans Mistakes for Employee Engagement and Workforce Strategy