Tag: Group RRSP

  • How Can Canadian Businesses Help Employees Understand How Workplace Retirement Contributions Affect Taxes, RRSP Room, and Year-End Planning?

    How Can Canadian Businesses Help Employees Understand How Workplace Retirement Contributions Affect Taxes, RRSP Room, and Year-End Planning?

    Workplace retirement contributions can affect more than an employee’s retirement account balance. Depending on the type of plan and who makes the contribution, they may also affect tax reporting, RRSP deduction room, pension adjustments, payroll information, and year-end financial planning.

    This can become especially confusing during tax season, when employees begin reviewing T4 slips, contribution receipts, plan statements, and their CRA account.

    A Group RRSP, Deferred Profit Sharing Plan (DPSP), Registered Pension Plan (RPP), and Pooled Registered Pension Plan (PRPP) do not all receive the same tax treatment.

    For employers, the objective should be to explain the general rules of the workplace plan clearly, show employees where relevant information appears, and direct personal tax or investment questions to the Canada Revenue Agency or appropriately qualified professionals.

    The employer should not calculate an individual employee’s RRSP deduction limit or predict their personal tax result. OpenAccess_Q53_QA_with_Resource…

    Quick Answer: How Do Workplace Retirement Contributions Affect Taxes and RRSP Room?

    Canadian employers can help employees understand workplace retirement contributions by explaining the type of retirement plan, distinguishing employee and employer contributions, describing pension adjustments in general terms, showing where amounts may appear on pay statements and tax slips, and directing employees to CRA resources for their personal RRSP deduction limit.

    The tax effect depends on the plan type and the employee’s individual circumstances, so general workplace education should remain separate from personal tax advice.
    Workplace retirement contributions explained for Canadian employees with taxes, RRSP deduction room, pension adjustments, tax slips, and year-end planning.

    On This Page

    1. Why Workplace Contributions Can Affect Tax Planning
    2. 7 Smart Employer Education Steps
    3. Group RRSP Tax Treatment
    4. DPSP and Pension Adjustments
    5. Registered Pension Plans
    6. PRPP Contributions
    7. How RRSP Room Is Determined
    8. Year-End and Tax-Season Planning
    9. What Employers Should Avoid
    10. Ongoing Employee Education
    11. How Open Access Limited May Support Employers
    12. FAQs
    13. Final Thoughts
    14. References

    Why Workplace Retirement Contributions Can Affect Tax Planning

    The phrase workplace retirement contributions can describe several different arrangements.

    An employee may participate in:

    • A Group RRSP
    • A DPSP
    • A Registered Pension Plan
    • A Defined Contribution pension plan
    • A PRPP

    The effect on income, deductions, RRSP room, and tax reporting can differ substantially.

    That is why employers should begin by answering one basic question:

    “Which retirement arrangement does this employee actually participate in?”

    Only after the plan type is clear should the employer explain its general tax and reporting features.

    7 Smart Ways to Explain Workplace Retirement Contributions

    1. Start by Explaining the Type of Retirement Plan

    Employees should first understand which retirement arrangement applies to them.

    For example:

    Group RRSP
    Employees may contribute through payroll and the employer may also contribute.

    DPSP
    Only the employer contributes.

    RPP or Defined Contribution Pension Plan
    Both employee and employer contribution rules may apply, depending on plan terms.

    PRPP
    Contribution and tax rules differ again.

    Explaining the plan type first can prevent employees from applying information about another type of retirement plan to their own situation.

    This is one of the most important foundations for explaining workplace retirement contributions accurately.

    2. Clearly Separate Employee Contributions From Employer Contributions

    Employees may see several contribution amounts without knowing who funded them or how they are reported.

    Employers should explain:

    • What the employee contributes
    • What the employer contributes
    • Whether employer matching applies
    • When contributions are made
    • Where contributions appear on pay statements
    • Where they appear on plan statements
    • Which tax documents may contain relevant information

    This is especially important where employer matching contributions form part of the plan.

    A simple communication model is:

    Employee Contribution → Employer Contribution → Plan Record → Tax Information

    The employer should explain the process without predicting the employee’s personal tax result.

    3. Explain RRSP Room in General Terms

    Employees often ask:

    “How much can I still put into my personal RRSP?”

    The employer should not calculate this amount.

    CRA calculates each individual’s RRSP deduction limit.

    In general terms, the calculation can involve unused deduction room carried forward plus a percentage of previous-year earned income up to the applicable annual limit, with adjustments that can include a Pension Adjustment.

    Employees can find their own RRSP deduction limit through their CRA Notice of Assessment or Reassessment or their CRA account. OpenAccess_Q53_QA_with_Resource…

    A useful employer message is:

    “Before making an additional personal RRSP contribution, check your current RRSP deduction limit directly with the CRA.”

    4. Explain the Pension Adjustment Without Making It Complicated

    The Pension Adjustment (PA) is one of the most confusing areas for employees.

    A clear general explanation is:

    A pension adjustment reflects the value of certain retirement benefits earned through an employer-sponsored pension arrangement during the year.

    Where applicable, it is generally reported in Box 52 of the T4 slip.

    It is not itself employment income and it is not an RRSP deduction.

    Instead, it can reduce the employee’s RRSP deduction limit for the following year.

    This is particularly relevant for DPSPs and Registered Pension Plans. OpenAccess_Q53_QA_with_Resource…

    Employees should still use CRA information to determine their actual available room.

    5. Show Employees Where to Find Their Information

    Employees should not have to guess which document contains which information.

    A year-end guide can show them where to look:

    Pay Statement
    Employee payroll deductions and applicable employer contributions.

    Retirement Plan Statement or Portal
    Contributions recorded in the workplace retirement account.

    T4 Slip
    Certain pension contributions, taxable benefits, and pension adjustments where applicable.

    CRA Notice of Assessment
    The employee’s personal RRSP deduction limit.

    This practical explanation makes workplace retirement contributions easier to understand than simply describing tax rules in abstract terms.

    6. Prepare Employees Before Year-End

    Tax questions often arise between year-end and the tax-filing period.

    Employees may be:

    • Reviewing their T4
    • Checking contribution receipts
    • Looking at plan statements
    • Reviewing their CRA account
    • Considering an additional personal RRSP contribution

    Employers can reduce confusion by providing general education before employees make additional personal contributions.

    The message should not say:

    “You should contribute another $X.”

    Instead:

    “Check your current CRA RRSP deduction limit before deciding whether to make an additional personal contribution.”

    This keeps education useful without becoming personal tax advice.

    7. Coordinate HR, Payroll, and the Plan Provider

    Employee confusion increases when HR, payroll, and the provider explain the same issue differently.

    Before year-end communication is released, employers should align:

    • Plan terminology
    • Contribution descriptions
    • Tax-slip explanations
    • Pension-adjustment language
    • RRSP-room guidance
    • Support contacts

    The source specifically recommends coordination between HR, payroll, and the provider to reduce inconsistent answers. OpenAccess_Q53_QA_with_Resource…

    For growing businesses, this also connects naturally with controls designed to reduce retirement plan payroll errors.
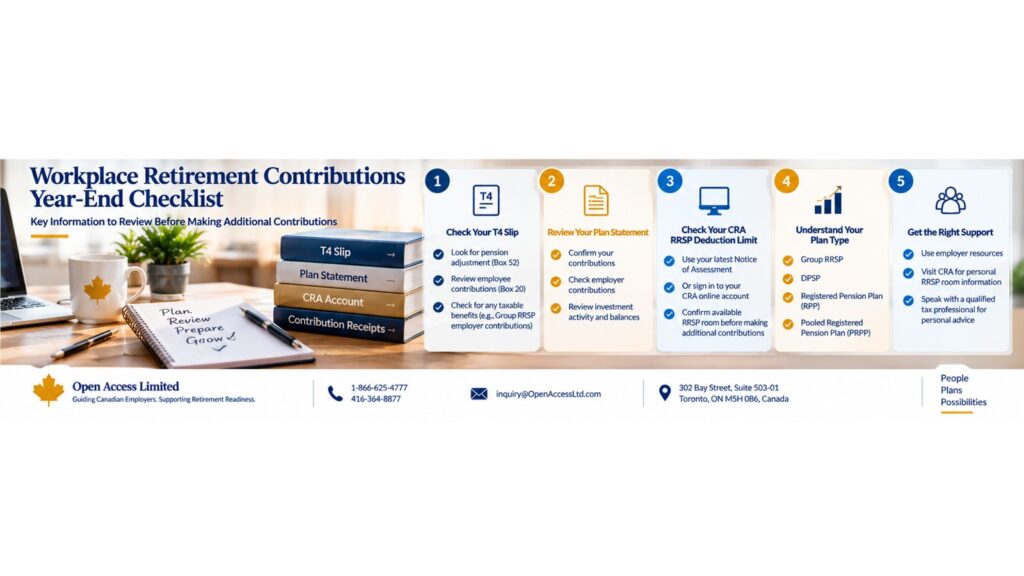
    Workplace retirement contributions year-end checklist showing T4 slips, pension adjustments, RRSP deduction limits, plan statements, CRA information, and employee support.

    How Group RRSP Contributions Affect Taxes and RRSP Room

    A Group RRSP is an employer-sponsored retirement savings arrangement.

    Employees commonly make contributions through payroll deductions, and an employer may also contribute.

    CRA guidance states that employer contributions to an employee’s RRSP are generally treated as a taxable benefit and reported on the employee’s T4.

    Contributions to the employee’s RRSP count against that individual’s RRSP deduction limit. OpenAccess_Q53_QA_with_Resource…

    This means employees should not assume that an employer contribution exists outside their personal RRSP-room considerations.

    They should review their actual CRA limit before making additional personal RRSP contributions.

    How DPSP Contributions Affect RRSP Room

    A Deferred Profit Sharing Plan works differently.

    Employees do not contribute to a DPSP.

    Only the employer contributes.

    Employer DPSP contributions generate a Pension Adjustment, which is reported on the employee’s T4 and generally reduces the employee’s RRSP deduction limit for the following year. OpenAccess_Q53_QA_with_Resource…

    This is a useful distinction for employees who participate in a Group RRSP plus DPSP arrangement.

    They may see contributions going into two retirement accounts, but the tax and RRSP-room treatment of those arrangements is not identical.
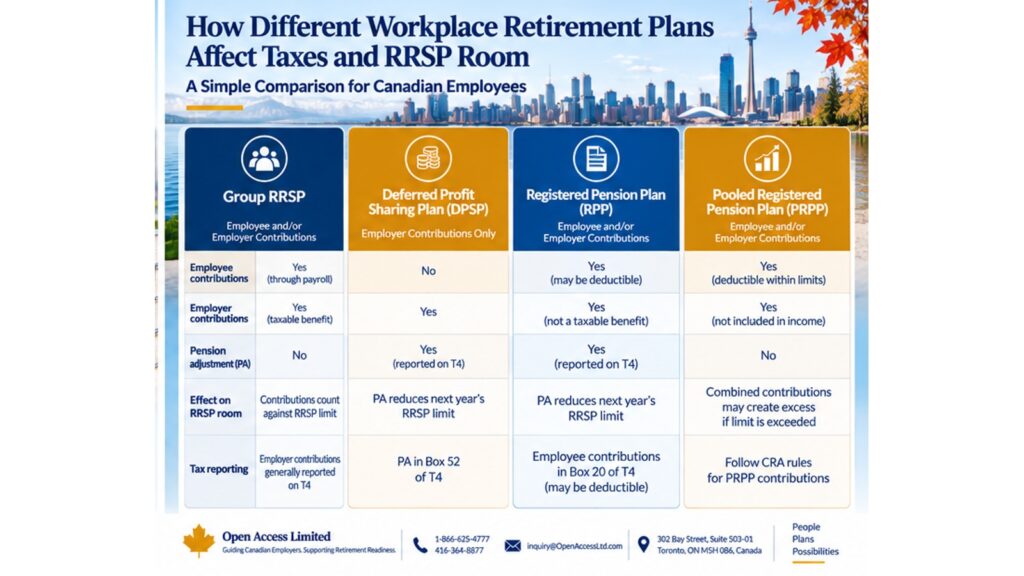
    Different workplace retirement plans can affect tax reporting, deductions, and RRSP room in different ways.

    How Registered Pension Plan Contributions Are Treated

    Registered Pension Plans, including defined contribution pension plans, follow another set of rules.

    According to the source:

    • Employer contributions to an RPP are generally not a taxable benefit to the employee.
    • Eligible employee RPP contributions reported in Box 20 of the T4 may be deductible on line 20700.
    • A Pension Adjustment may be reported and can reduce the following year’s RRSP deduction limit. OpenAccess_Q53_QA_with_Resource…

    This is why employees should not assume that the tax treatment of an RPP is identical to a Group RRSP.

    What About PRPP Contributions?

    A Pooled Registered Pension Plan follows different contribution and deduction rules again.

    The source notes that a member’s own PRPP contributions may be deductible within applicable limits.

    Employer PRPP contributions are not included in the member’s income and are not deductible by the member.

    However, employer PRPP contributions combined with the employee’s own PRPP and RRSP contributions may create an excess-contribution issue if the applicable RRSP deduction limit is exceeded. OpenAccess_Q53_QA_with_Resource…

    Employees should therefore confirm their personal limit before making additional registered contributions.

    Why RRSP Overcontributions Matter

    The source notes that CRA generally imposes a tax of 1% per month on RRSP contributions exceeding an individual’s deduction limit by more than the applicable $2,000 threshold. OpenAccess_Q53_QA_with_Resource…

    This is an important reason employers should avoid estimating an employee’s RRSP room.

    The safest general message is:

    “Confirm your personal RRSP deduction limit with the CRA before making additional personal contributions.”

    Why Year-End Communication Matters

    Year-end creates a natural opportunity to explain workplace retirement contributions.

    Employees are already reviewing:

    • Payroll records
    • Retirement statements
    • Contribution receipts
    • Tax slips
    • CRA information

    Employers can prepare a short year-end FAQ addressing common questions.

    For example:

    Where Can I Find My RRSP Deduction Limit?

    Use your latest CRA Notice of Assessment, Reassessment, or CRA account.

    What Is the Pension Adjustment on My T4?

    It generally reflects certain employer-sponsored retirement benefits earned during the year and can reduce next year’s RRSP deduction limit.

    Does My Employer Contribution Affect My Taxes?

    It depends on the type of retirement arrangement.

    Can I Still Contribute to My Personal RRSP?

    Possibly, but employees should confirm their available deduction room with the CRA first.

    Who Should I Ask About My Personal Tax Situation?

    CRA or an appropriately qualified tax or financial professional.

    What Employers Should Avoid

    Employers should avoid:

    • Telling an employee exactly how much to contribute
    • Calculating an employee’s RRSP deduction limit
    • Promising a tax refund
    • Predicting tax savings
    • Predicting an individual RRSP-room outcome
    • Assuming every employee has the same circumstances
    • Giving personal investment recommendations
    • Giving personal tax advice
    • Sending conflicting HR, payroll, and provider messages

    The source specifically identifies these as important boundaries. OpenAccess_Q53_QA_with_Resource…

    A workplace education program should explain how the plan works, not determine what a specific employee should do.

    Keep Workplace Education Separate From Personal Tax Advice

    This distinction is central to the entire article.

    Employers can explain:

    • Plan type
    • General contribution rules
    • Employer matching
    • Where contribution information appears
    • What a pension adjustment means generally
    • Where employees can find CRA information

    Employers should not determine:

    • The employee’s personal RRSP room
    • Whether the employee should make a contribution
    • The employee’s tax refund
    • The employee’s personal tax strategy
    • Which investment is best for that employee

    The employee’s individual circumstances may include income, unused RRSP room, other registered plans, previous contributions, and personal tax circumstances that the employer does not know.

    Ongoing Education Is Better Than a One-Time Tax-Season Message

    Tax questions recur every year.

    That means education about workplace retirement contributions should not happen only at onboarding or only once during tax season.

    CAPSA’s Guideline No. 3 emphasizes ongoing member communication and education rather than limiting education to initial enrolment. OpenAccess_Q53_QA_with_Resource…

    Employers can reinforce information:

    • Before year-end
    • When tax slips become available
    • During benefit education
    • When contribution formulas change
    • When employees change contribution elections
    • Through financial-wellness education

    This also supports broader retirement income education.

    How Can Employers Keep Tax-Time Communication Accurate?

    A strong process can include:

    • Current plan documents
    • Current CRA guidance
    • Plan-provider confirmation
    • Consistent HR and payroll explanations
    • Annual FAQ review
    • Updated contribution limits
    • Clear disclaimer language
    • Direct links to CRA resources
    • Qualified-professional referrals

    Dollar limits and CRA guidance can change from year to year.

    That means employee-facing materials should be reviewed before being reused.

    Important Implementation Boundaries

    This article describes general federal income-tax treatment.

    It does not determine individual tax outcomes.

    It does not address every provincial or territorial tax issue, locked-in arrangement, Group TFSA, or personal circumstance.

    The treatment of workplace retirement contributions depends on:

    • Plan type
    • Official plan documents
    • Payroll arrangements
    • Employee circumstances
    • Current CRA guidance

    Before sending tax-related communication or changing a payroll or contribution practice, employers should confirm the information with the plan provider and obtain qualified tax or payroll advice where appropriate. OpenAccess_Q53_QA_with_Resource…

    Need Help Make Workplace Retirement Contributions Easier to Understand?

    Open Access Limited may support employers with workplace retirement-plan education and year-end contribution communication.

    Open Access materials include group retirement-plan information, financial-wellness resources, RRSP and TFSA education, calculators, contribution forms, member portal access, statements and transaction information, and member support. OpenAccess_Q53_QA_with_Resource…

    Depending on the applicable plan, Open Access Limited may help employers and members understand:

    • The type of workplace retirement plan
    • Contribution provisions
    • Employer matching
    • Recorded contributions
    • Available plan statements
    • Member portal information
    • Financial-wellness resources
    • Available member support

    Employers should confirm with Open Access Limited which receipts, statements, or tax slips apply to their particular plan and when they are issued.

    Open Access Limited should not be positioned as providing personal tax advice or determining an individual employee’s RRSP deduction limit.

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6, Canada

    Toll-Free: 1 (866) 625 4777
    General: 416 364 8877
    Fax: 416 955 4878
    Email: inquiry@OpenAccessLtd.com
    Website: www.OpenAccessLtd.com

    Frequently Asked Questions

    Do Workplace Retirement Contributions Reduce Taxable Income?

    It depends on the plan type, who makes the contribution, and applicable tax rules. Employees should use current plan information and CRA resources.

    Do Employer Contributions Reduce My RRSP Room?

    They may affect RRSP room differently depending on the plan structure. For example, DPSP and RPP benefits can create a Pension Adjustment that reduces the following year’s RRSP deduction limit.

    Where Can Employees Find Their RRSP Deduction Limit?

    Employees can review their CRA Notice of Assessment or Reassessment or their CRA account.

    What Is a Pension Adjustment?

    A Pension Adjustment generally reflects the value of certain retirement benefits earned through an employer-sponsored pension or DPSP arrangement. It is not income or a deduction but may reduce next year’s RRSP deduction limit.

    Are Group RRSP and RPP Contributions Taxed the Same Way?

    No. Group RRSPs and Registered Pension Plans can have different tax, reporting, and RRSP-room treatment.

    Can an Employer Calculate an Employee’s RRSP Room?

    Employers should not calculate an individual employee’s RRSP deduction limit. Employees should confirm their current limit directly with the CRA.

    Should Employees Check RRSP Room Before Making an Extra Year-End Contribution?

    Yes. Employees considering additional personal contributions should review their own current CRA limit before making a decision.

    Final Thoughts

    Workplace retirement contributions can affect tax reporting and RRSP room in different ways depending on the retirement-plan structure.

    For Canadian employers, the strongest educational approach is:

    Explain the Plan Type → Separate Employee and Employer Contributions → Explain Pension Adjustments → Show Employees Where to Find Information → Prepare for Year-End → Coordinate HR, Payroll and Provider → Refer Personal Tax Questions Appropriately

    The objective is not to turn employers into tax advisers.

    It is to give employees clearer information about their workplace retirement plan so they know what to look for, what questions to ask, and where to obtain authoritative information before making personal year-end financial decisions.

    References

    1. Canada Revenue Agency — How Contributions Affect Your RRSP Deduction Limit.
    2. Canada Revenue Agency — Where Can You Find Your RRSP Deduction Limit.
    3. Financial Consumer Agency of Canada — Employer Pension Plans.
    4. Canada Revenue Agency — Contributions to Savings and Pension Plans.
    5. Canada Revenue Agency — Contributing to a Deferred Profit Sharing Plan.
    6. Canada Revenue Agency — Reporting a Pension Adjustment.
    7. Canada Revenue Agency — Line 20600 — Pension Adjustment.
    8. Canada Revenue Agency — Line 20700 — Registered Pension Plan (RPP) Deduction.
    9. Canada Revenue Agency — Contributions to a PRPP.
    10. Canadian Association of Pension Supervisory Authorities — Guideline No. 3: Guideline for Capital Accumulation Plans.
    11. Open Access Limited — Group Retirement Plans in Canada; Financial Wellness Resources; Member Forms; Member Resources.
  • How Should Canadian Businesses Manage Workplace Retirement Plan Contributions During Employee Leaves of Absence?

    How Should Canadian Businesses Manage Workplace Retirement Plan Contributions During Employee Leaves of Absence?

    Retirement contributions during leave can become complicated because there is no single Canada-wide rule that applies to every employee, every type of leave, or every workplace retirement arrangement.

    Employees may take pregnancy, parental, medical, family caregiver, statutory, or employer-approved leaves. At the same time, workplace retirement plans may include Registered Pension Plans (RPPs), defined contribution pension plans, Group RRSPs, DPSPs, and other arrangements that follow different contribution, tax, payroll, and reporting rules. OpenAccess_Q52_QA_with_Resource…

    For Canadian employers, the goal should not be to promise that contributions will always continue in the same way.

    A stronger approach is to create a documented process that covers:

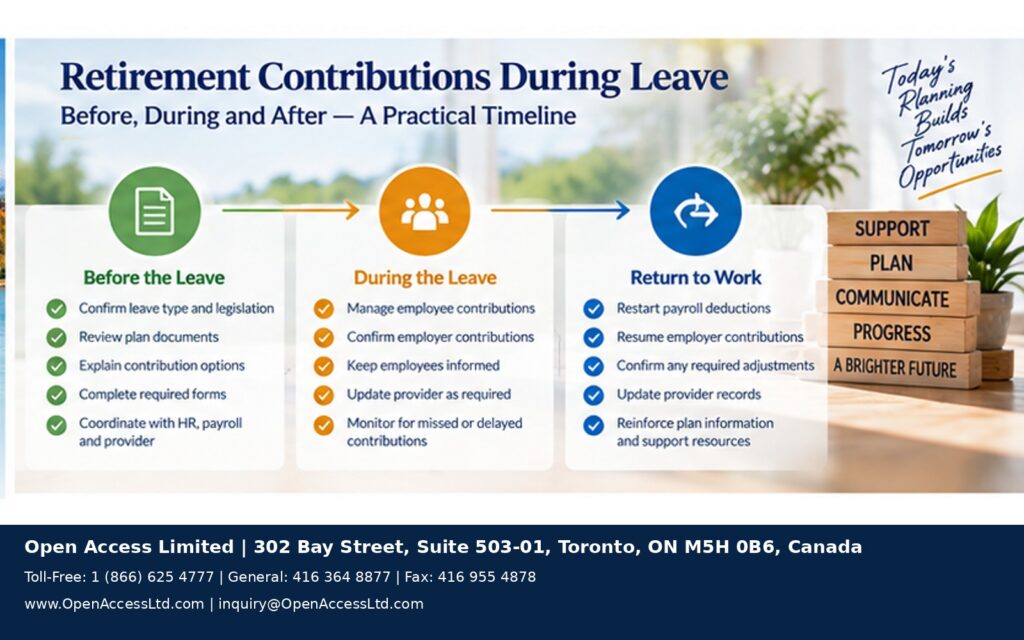
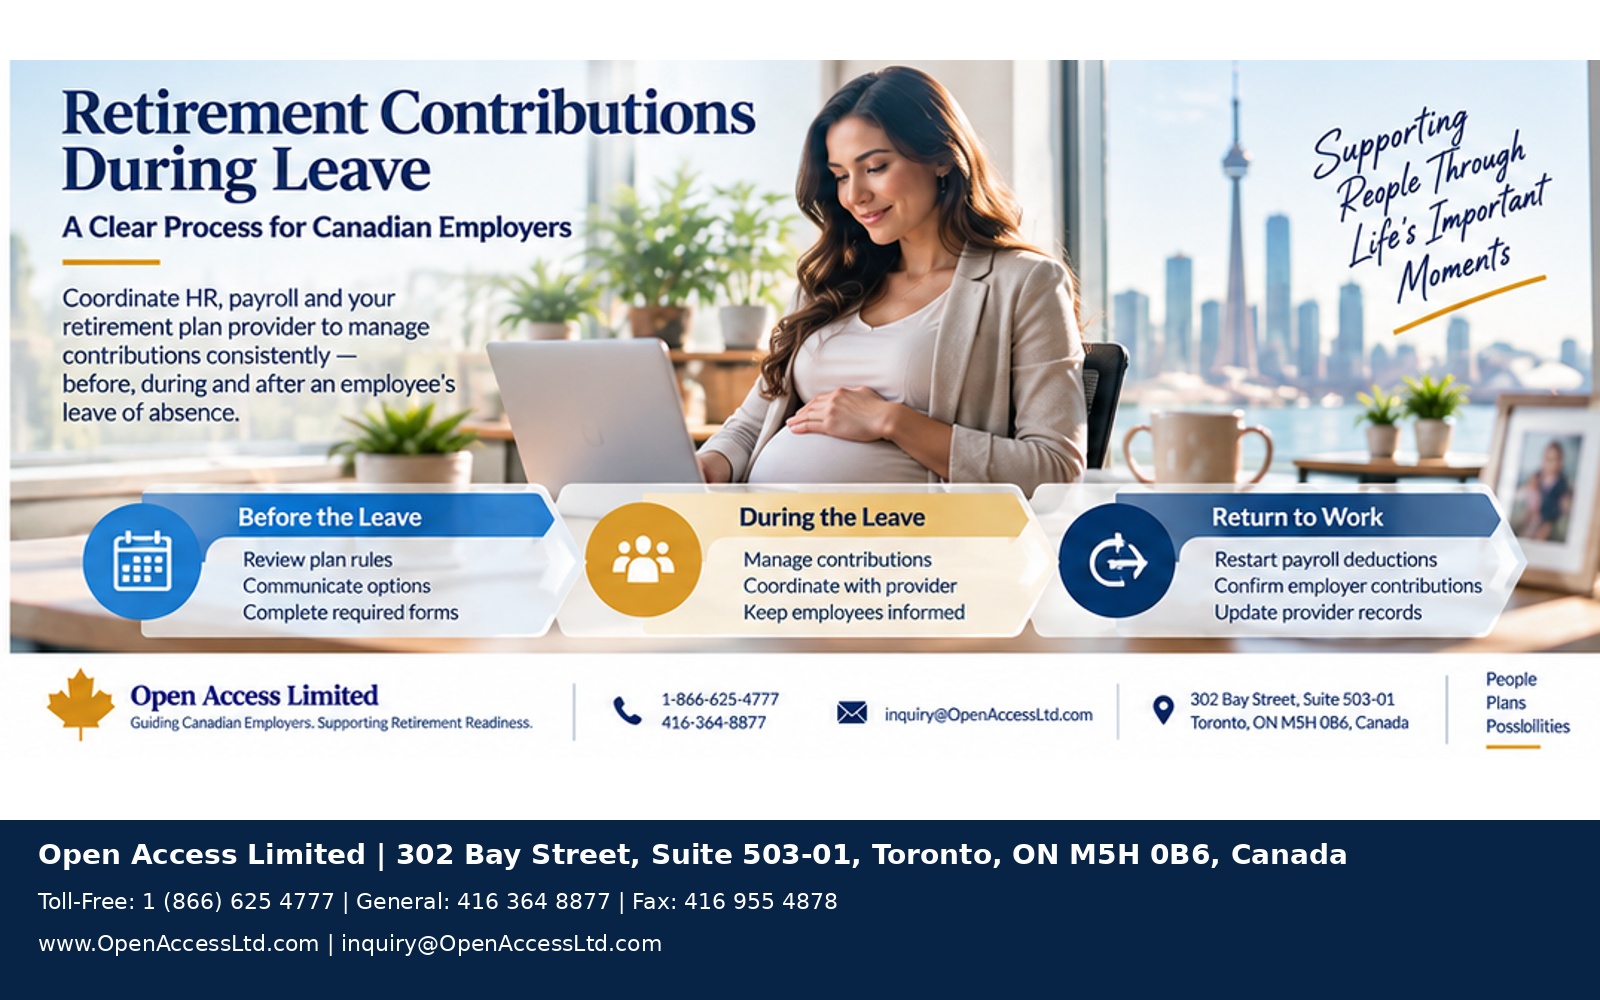
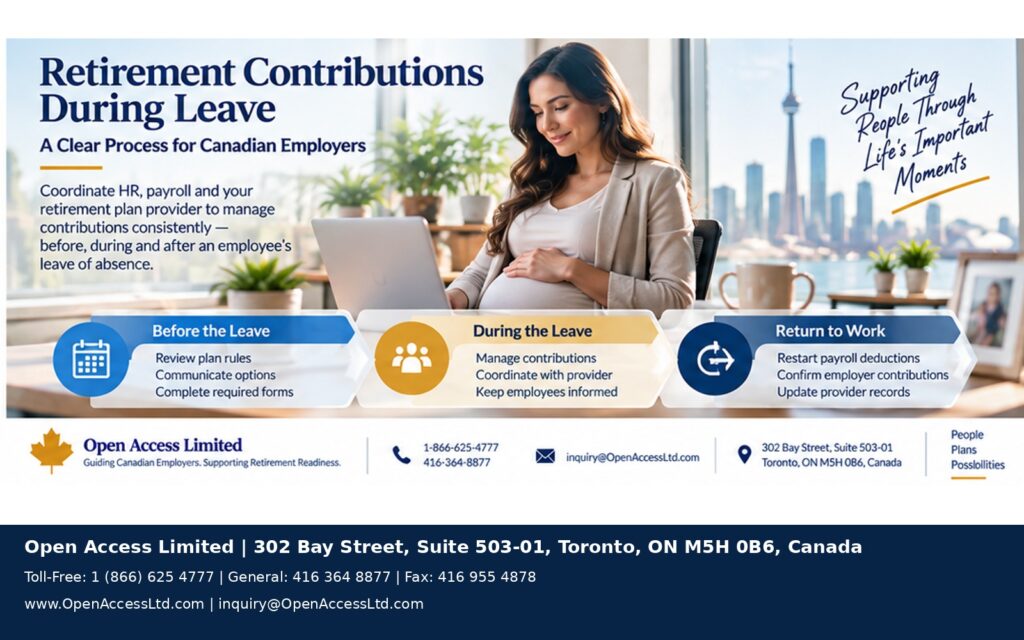
    Before the leave → During the leave → Return to work

    That process should connect applicable legislation, official plan documents, HR, payroll, the retirement-plan provider, employee communication, and recordkeeping.

    Quick Answer: How Should Employers Handle Retirement Contributions During Leave?

    Canadian employers should manage retirement contributions during leave by first identifying the type of leave and applicable jurisdiction, reviewing official plan documents, confirming employee and employer contribution rules, coordinating HR and payroll with the plan provider, communicating options clearly, planning for the employee’s return to work, and documenting decisions and corrections.

    Employers should avoid assuming that the same rules apply to every plan or jurisdiction and should not recommend which personal contribution option an employee should choose.

    On This Page

    1. Why Leave Contributions Require a Defined Process
    2. 7 Smart Employer Steps
    3. Ontario Leave Examples
    4. Federally Regulated Workplaces
    5. Other Provinces and Territories
    6. How Plan Type Changes the Rules
    7. Employee Questions to Prepare For
    8. Ongoing Communication
    9. Common Administrative Risks
    10. Important Implementation Boundaries
    11. How Open Access Limited May Support Employers
    12. FAQs
    13. Final Thoughts
    14. References

    Why Retirement Contributions During Leave Need a Documented Process

    A leave of absence can affect several systems at the same time.

    HR may record the employee’s leave status.

    Payroll may reduce or stop regular pay.

    The retirement-plan provider may require different contribution or member information.

    The employee may need to make an election or provide written notice.

    When these activities are not coordinated, retirement contributions during leave may be missed, delayed, calculated incorrectly, or require correction later. OpenAccess_Q52_QA_with_Resource…

    This is why the employer should avoid relying on informal instructions.

    The process should be documented and repeatable.

    Retirement contributions during leave workflow for Canadian employers coordinating employee leave, HR, payroll, retirement plan contributions, and return to work.

    7 Smart Ways to Manage Retirement Contributions During Leave

    1. Identify the Type of Leave and Applicable Jurisdiction

    Start by determining:

    • What type of leave is involved?
    • Is it statutory or employer-approved?
    • Is the leave paid or unpaid?
    • Which employment standards legislation applies?
    • Is the employer provincially, territorially, or federally regulated?

    This matters because leave entitlements can vary significantly.

    A pregnancy or parental leave in an Ontario-regulated workplace may not operate under exactly the same rules as a federally regulated leave or a leave in another province.

    Retirement contributions during leave should therefore begin with the applicable legal framework—not with a generic company practice.

    An internal policy cannot override legislation or official plan terms.

    2. Review the Official Retirement Plan Documents

    The official plan documents should be one of the first places an employer looks.

    Review:

    • Eligibility provisions
    • Employee contributions
    • Employer contributions
    • Matching formulas
    • Definitions of earnings
    • Leave-of-absence provisions
    • Contribution timing
    • Suspension or continuation rules
    • Return-to-work provisions

    If the documents are silent or unclear, confirm the treatment with the plan administrator or provider.

    The original framework specifically recommends checking official plan terms before determining how leave contributions will be administered. OpenAccess_Q52_QA_with_Resource…

    This is also where the employer’s broader retirement plan governance process becomes important.

    3. Confirm How Employee Contributions Will Be Handled

    If an employee normally contributes through payroll, an unpaid or reduced-pay leave can create an operational challenge.

    Regular payroll deductions may no longer be available.

    If another method of collecting contributions is being considered, it should be permitted by:

    • Applicable legislation
    • The plan terms
    • The plan provider
    • Relevant payroll procedures

    Employees should receive neutral information about the options available under the plan.

    Employers should not tell an employee which option is personally best.

    The employee’s choice—and any required election or notice—should be documented in writing where applicable.

    4. Coordinate HR, Payroll, and the Retirement-Plan Provider

    This is one of the most important operational controls.

    HR, payroll, and the provider should be working from the same information.

    The employer should confirm:

    • Leave start date
    • Leave type
    • Eligibility status
    • Employee contribution treatment
    • Employer contribution treatment
    • Pay status
    • Contribution amount
    • Method of collection
    • Remittance timing
    • Required forms
    • Provider updates

    This coordination helps reduce retirement contributions during leave errors involving missed, late, duplicated, or incorrectly calculated contributions.

    It also connects directly with the employer’s broader retirement plan payroll errors controls.

    5. Communicate the Process in Plain Language

    Employees should not need to interpret legal language or technical plan provisions themselves.

    Provide a clear written summary explaining:

    • What happens before the leave
    • Whether contributions may continue
    • How employee contributions may be collected
    • How employer contributions are treated
    • Important deadlines
    • Required forms
    • Where official documents can be found
    • Who to contact with questions

    The source framework specifically recommends repeating key information rather than communicating only once before the leave begins. OpenAccess_Q52_QA_with_Resource…

    A leave may last many months.

    Information provided at the beginning may need to be reinforced later.

    6. Plan the Employee’s Return to Work

    The contribution process should not end with the leave itself.

    Before or when the employee returns, confirm:

    • When regular payroll deductions restart
    • When employer contributions resume
    • Whether payroll requires updating
    • Whether the provider requires an update
    • Whether any adjustment is required under the plan
    • Whether the employee needs new information

    A clean return-to-work process reduces the risk that deductions remain paused or that the wrong contribution formula continues after the employee returns.

    7. Document the Entire Process

    Keep appropriate records of:

    • Employee notices
    • Elections
    • Payroll instructions
    • Provider communications
    • Effective dates
    • Forms
    • Contribution calculations
    • Corrections
    • Return-to-work updates

    Good documentation supports both administration and later review.

    It can also help identify recurring problems.

    A disciplined approach to retirement contributions during leave should create a clear record of what was decided, why, and how it was implemented.

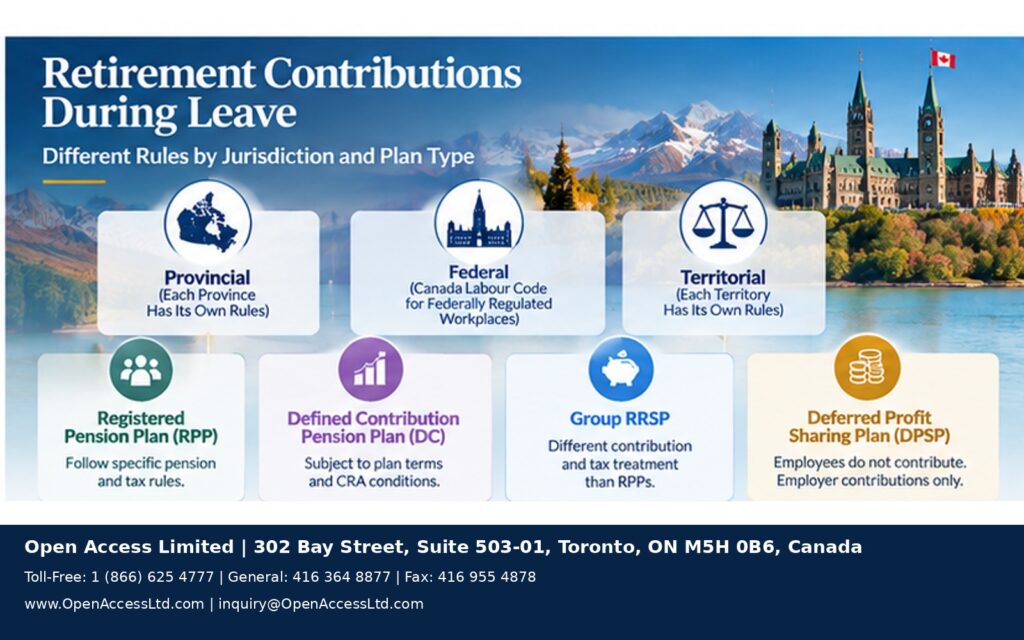
    Retirement contributions during leave compared across jurisdictions and workplace retirement arrangements including pension plans, Group RRSPs, and DPSPs.

    Ontario: Leave Rules Can Affect Benefit Participation

    For Ontario-regulated employers, the Employment Standards Act guidance provides specific examples relating to benefit-plan participation during certain leaves.

    Ontario guidance states that employees on pregnancy or parental leave have rights relating to continued participation in certain benefit plans, including pension plans, and describes employer and employee contribution responsibilities in that context. OpenAccess_Q52_QA_with_Resource…

    The Ontario guidance also identifies other ESA leaves where benefit-plan continuation provisions may apply.

    However, an important distinction must be preserved:

    The cited Ontario sources refer to pension plans.

    They do not establish in this Q&A that a Group RRSP or DPSP must be treated in exactly the same way.

    Employers should not automatically extend one plan-type rule to another.

    Federally Regulated Workplaces Have Their Own Rules

    Federally regulated employers operate under a different framework.

    The source notes that section 209.2 of the Canada Labour Code addresses pension, health, disability benefits, and seniority during certain Division VII leaves.

    Where an employee is required to contribute, the Code addresses employee contribution responsibilities and corresponding employer contributions, subject to the applicable conditions. OpenAccess_Q52_QA_with_Resource…

    For federally regulated employers, retirement contributions during leave should therefore be reviewed against the Canada Labour Code and current federal guidance.

    Do not assume provincial rules apply.

    What About Other Provinces and Territories?

    Other provinces and territories have their own employment standards legislation.

    An employer with employees in several provinces may need a jurisdiction-by-jurisdiction process.

    That means a national business may need to distinguish between:

    Ontario employee → Federal employee → Alberta employee → British Columbia employee → Other jurisdiction

    rather than applying one internal leave-contribution rule across Canada.

    The source explicitly notes that leave entitlements may differ and multi-jurisdiction employers may need separate review. OpenAccess_Q52_QA_with_Resource…

    Plan Type Matters: RPP, Group RRSP, and DPSP Are Different

    Another major source of risk is assuming that every retirement arrangement follofollows the same contribution rules.

    It does not.

    Registered Pension Plans and DC Pension Plans

    The CRA framework discussed in the source permits certain defined contribution pension arrangements to recognize prescribed compensation for qualifying periods of reduced pay or leave, subject to conditions and limits.

    The source also notes that employer contributions to an RPP are not generally treated as a taxable benefit to the employee in the same way as employer RRSP contributions. OpenAccess_Q52_QA_with_Resource…

    Group RRSPs

    Employer contributions to an employee’s RRSP are generally treated differently for tax and payroll purposes.

    If regular pay is reduced or paused during leave, employers may need to confirm with the payroll and plan provider how contributions can be processed under the applicable arrangement.

    Deferred Profit Sharing Plans

    A DPSP is different again.

    Employees do not contribute to a DPSP; only participating employers contribute.

    Contribution limits also include compensation-based calculations.

    Reduced compensation during a leave can therefore create different questions than it would under a Group RRSP or pension plan. OpenAccess_Q52_QA_with_Resource…

    This is why retirement contributions during leave should always be reviewed by plan type.

    Employee Questions Employers Should Be Ready to Answer

    Employees may reasonably ask:

    Will My Workplace Retirement Plan Continue While I Am on Leave?

    The answer depends on the applicable legislation, plan type, and official plan documents.

    Will My Payroll Contributions Continue?

    If regular pay is reduced or stopped, normal payroll deductions may not continue in the usual way.

    Will My Employer Continue Contributing?

    This depends on applicable requirements and plan terms.

    Do I Need to Complete a Form?

    Some plans or leave situations may require notices, elections, or contribution instructions.

    What Happens if I Do Not Contribute During the Leave?

    The employer should explain the applicable plan process without advising the employee which personal choice to make.

    How Do Contributions Restart When I Return?

    The employer should clearly explain the return-to-work process.

    Who Can Help Me?

    Employees should have access to the employer, plan administrator/provider, or another appropriate contact depending on the question.

    The source specifically recommends answering these questions from applicable legislation, official documents, and provider confirmation—not personal assumptions. OpenAccess_Q52_QA_with_Resource…

    Ongoing Communication Should Continue Throughout the Leave

    A long leave can last many months.

    Employees may not remember every instruction received before it began.

    Employers can use a three-stage communication model:

    Before Leave

    Provide:

    • Written contribution information
    • Required forms
    • Deadlines
    • Contacts
    • Plan-document references

    During Leave

    Where appropriate, remind employees about:

    • Deadlines
    • Contribution arrangements
    • Support contacts
    • Plan information

    Return to Work

    Confirm:

    • Payroll restart
    • Employer contribution restart
    • Required adjustments
    • Provider updates
    • Current plan resources

    CAPSA’s Guideline No. 3 supports an ongoing education approach rather than restricting member education to initial enrolment. OpenAccess_Q52_QA_with_Resource…

    This is also a natural opportunity to reinforce broader retirement income education.

    Common Mistakes Employers Should Avoid

    Avoid these common administrative problems:

    • Assuming one Canada-wide rule exists
    • Treating every type of leave the same way
    • Applying pension-plan rules automatically to Group RRSPs
    • Applying Group RRSP rules automatically to DPSPs
    • Relying on an internal practice instead of official documents
    • Failing to coordinate payroll and HR
    • Forgetting to notify the plan provider
    • Giving employees personal contribution recommendations
    • Communicating only once before the leave
    • Failing to plan for return to work
    • Assuming a payroll correction automatically solves a plan issue
    • Failing to document employee elections or corrections

    These mistakes can increase the risk of inconsistent retirement contributions during leave administration.

    How Can Employers Keep Leave Contribution Information Accurate?

    Employers can strengthen accuracy by:

    • Using current legislation
    • Using current official plan documents
    • Confirming plan treatment with the provider
    • Documenting payroll instructions
    • Recording employee elections
    • Reviewing changes before implementation
    • Keeping HR and payroll information aligned
    • Confirming return-to-work procedures
    • Escalating unclear cases to qualified professionals

    The goal is not to create a one-size-fits-all policy.

    The goal is a controlled decision process.

    Retirement contributions during leave timeline showing employer actions before leave, during leave, and when the employee returns to work.

    Important Implementation Boundaries

    Managing retirement contributions during leave can involve multiple areas of law and administration, including:

    • Employment standards
    • Pension law
    • Tax
    • Payroll
    • Human rights
    • Workers’ compensation
    • Privacy
    • Collective agreements
    • Contracts

    Requirements depend on the jurisdiction, type of leave, plan type, plan documents, and provider agreements. OpenAccess_Q52_QA_with_Resource…

    Government guides are useful resources, but employers should confirm current requirements before implementing or changing a practice.

    Internal policy cannot override legislation, employee rights, official plan terms, or plan-administrator responsibilities.

    Individual legal, tax, payroll, or financial questions should be referred to appropriately qualified professionals.

    Need Help Communicating Retirement Plan Contributions During Employee Leave?

    Open Access Limited may support employers with the workplace retirement-plan portion of leave-related communication.

    Open Access materials include plan-specific resources for several types of group retirement arrangements, as well as contribution forms, member portal access, education resources, and member support.

    Depending on the applicable Open Access plan, employers may use these resources to help confirm:

    • Plan-specific eligibility
    • Contribution provisions
    • Employer-matching terms
    • Member forms
    • Payroll contribution authorization
    • Member account information
    • Statements and transaction history
    • Financial-wellness education
    • Member-support contacts

    Whether a particular process can be used during a leave depends on the applicable plan terms and should be confirmed directly. OpenAccess_Q52_QA_with_Resource…

    Open Access Limited should remain positioned as supporting plan information, enrolment, contribution communication, education, member resources, and plan administration coordination—not as determining statutory leave entitlements or providing individual legal, tax, payroll, or employment-standards advice.

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6, Canada

    Toll-Free: 1 (866) 625 4777
    General: 416 364 8877
    Fax: 416 955 4878
    Email: inquiry@OpenAccessLtd.com
    Website: www.OpenAccessLtd.com

    Frequently Asked Questions

    Do Retirement Contributions Always Continue During a Leave of Absence?

    No. Retirement contributions during leave depend on the applicable jurisdiction, type of leave, type of retirement plan, plan documents, and other requirements.

    Are Pregnancy and Parental Leave Rules the Same Across Canada?

    No. Provincial, territorial, and federal employment rules can differ.

    Can Employers Stop Contributions When Payroll Stops?

    Not necessarily. Reduced or paused payroll does not, by itself, determine all employee or employer contribution obligations. The plan terms and applicable requirements must be reviewed.

    Are Group RRSPs and Pension Plans Treated the Same During Leave?

    No. Employers should not assume that pension-plan continuation rules automatically apply to a Group RRSP or DPSP.

    Can an Employer Tell an Employee Whether They Should Keep Contributing?

    Employers can explain available options and plan procedures but should avoid making individualized financial recommendations.

    What Should Happen When the Employee Returns to Work?

    The employer should confirm when payroll deductions and employer contributions resume and whether adjustments or provider updates are required.

    Should Leave Contribution Decisions Be Documented?

    Yes. Appropriate records of notices, employee elections, payroll instructions, provider updates, and corrections can support administration and future review.

    Final Thoughts

    Retirement contributions during leave should be managed through a documented process—not assumptions.

    For Canadian employers, the strongest framework is:

    Identify the Leave → Check the Jurisdiction → Review the Plan → Confirm Contributions → Coordinate Payroll and Provider → Communicate Clearly → Plan the Return → Document Everything

    There is no universal rule that fits every employee or every retirement plan.

    By grounding decisions in current legislation, official plan documents, provider information, clear communication, and qualified professional advice where necessary, employers can reduce administrative inconsistency while giving employees clearer information before, during, and after a leave.

    References

    1. Government of Ontario — Pregnancy and Parental Leave, Your Guide to the Employment Standards Act.
    2. Government of Ontario — Benefit Plans, Your Guide to the Employment Standards Act.
    3. Financial Services Regulatory Authority of Ontario — Events That May Affect Your Pension.
    4. Government of Canada — Canada Labour Code, Section 209.2.
    5. Government of Canada — Types of Leaves for Employees in Federally Regulated Industries and Workplaces.
    6. Canada Revenue Agency — Registered Plans Directorate Technical Manual: Periods of Reduced Pay and Salary Deferral Leave Plans.
    7. Canada Revenue Agency — Contributions to Savings and Pension Plans.
    8. Canada Revenue Agency — Contributing to a Deferred Profit Sharing Plan.
    9. Canadian Association of Pension Supervisory Authorities — Guideline No. 3: Guideline for Capital Accumulation Plans.
    10. Open Access Limited — Group Retirement Plans, Member Forms, Member Resources, Financial Wellness Resources, and Plan-Specific Enrolment Resources.

    These are the authoritative resources identified in the supplied Q&A 52 source. OpenAccess_Q52_QA_with_Resource…


  • How Can Canadian Businesses Reduce Payroll and Contribution Errors in Workplace Retirement Plans as They Grow?

    How Can Canadian Businesses Reduce Payroll and Contribution Errors in Workplace Retirement Plans as They Grow?

    Retirement plan payroll errors can become more likely as a business grows and its workplace retirement plan becomes more complex.

    More employees, additional locations, different payroll schedules, bonuses, commissions, part-time arrangements, eligibility rules, employer contribution formulas, and new service providers can all create additional administrative touchpoints.

    The risk is not simply a payroll calculation being wrong. Problems can arise when the official plan terms, payroll configuration, employee records, provider records, and employee communication no longer match.

    Examples may include an eligible employee being enrolled late, an incorrect contribution percentage being entered, employer matching being calculated differently from the plan terms, or bonuses and commissions being treated inconsistently.

    For Canadian employers, the objective should not be to promise an error-free system.

    A stronger approach is to establish controls that reduce the likelihood of errors, identify discrepancies earlier, document corrections, and make responsibilities clear across HR, payroll, the employer, and the retirement-plan provider.


    As organizations expand, retirement plan payroll errors can become harder to detect when HR, payroll, provider records, and official plan terms are not reviewed together.

    
Retirement plan payroll errors prevention workflow connecting HR, payroll, plan records, provider records, and employee contribution information.

    Quick Answer: How Can Employers Reduce Retirement Plan Payroll Errors?

    Canadian businesses can reduce retirement plan payroll errors by translating official plan terms into clear payroll instructions, defining responsibilities, reviewing employee eligibility, testing contribution formulas, reconciling payroll with provider records, controlling plan changes, communicating deductions clearly, documenting corrections, and reassessing processes as the organization grows.

    The goal is not perfection. It is earlier detection, clearer ownership, more consistent records, and stronger retirement-plan governance.


    Why Payroll and Retirement Plan Records Can Fall Out of Sync

    As a business grows, different systems may hold different pieces of employee information.

    HR may manage employment status and eligibility.

    Payroll may calculate deductions and employer contributions.

    A retirement-plan provider may maintain member and contribution records.

    Management may approve plan amendments.

    Employees may receive information through another communication channel.

    If these processes are not coordinated, retirement plan payroll errors may arise even when each team believes it is following the correct procedure.

    Common examples include:

    • Eligible employees not being enrolled when expected
    • Incorrect employee contribution percentages
    • Employer contributions calculated differently from plan terms
    • Bonuses or commissions handled inconsistently
    • Different eligibility dates across systems
    • Plan amendments implemented in one system but not another
    • Incorrect contribution-limit or reporting treatment
    • Unclear employee communication about deductions or matching

    The control objective is therefore alignment.


    9 Proven Controls to Reduce Retirement Plan Payroll Errors

    1. Translate Official Plan Terms Into Payroll Instructions

    Payroll teams should not have to interpret retirement-plan documents every time a contribution is calculated.

    Employers can document how the plan’s official terms translate into operational payroll instructions.

    This may include:

    • Eligibility
    • Waiting periods
    • Employee contributions
    • Employer contributions
    • Matching formulas
    • Contribution caps
    • Definition of eligible compensation
    • Contribution timing
    • Effective dates

    For example, if the plan uses a specific definition of compensation, payroll configuration should reflect that definition accurately.

    This becomes particularly important where salaries, bonuses, commissions, or other forms of compensation are treated differently.

    A written bridge between plan documents and payroll processes can help reduce inconsistencies.


    2. Define Who Is Responsible for What

    One of the easiest ways for an administrative task to be missed is when everyone assumes someone else owns it.

    Employers should clearly establish which responsibilities belong to:

    • HR
    • Payroll
    • Finance
    • Management
    • The plan administrator
    • The retirement-plan provider
    • External service providers

    The process should also identify:

    Who approves a change?
    Who enters it?
    Who checks it?
    Who resolves discrepancies?

    Clear ownership can help prevent both duplicated work and missed steps.

    As the organization grows, these responsibilities should be documented rather than relying only on informal knowledge.


    Clear ownership can also reduce retirement plan payroll errors by ensuring that changes, approvals, calculations, and corrections have a defined responsible party.


    3. Review Employee Eligibility Regularly

    Employee eligibility is not always static.

    An employee’s status may change because of:

    • Hours worked
    • Employment status
    • Compensation
    • Waiting periods
    • Location
    • Plan amendments
    • Changes in employment arrangements

    Employers should establish a process for identifying when employees become eligible under the official plan terms.

    This is closely connected with retirement plan eligibility governance.

    Eligibility information should also be compared across HR, payroll, and plan-provider records.

    That can help identify missed enrolments or inconsistent eligibility dates earlier.


    Regular eligibility reviews can help prevent retirement plan payroll errors caused by missed enrolment dates, changing work status, or inconsistent employee records.


    4. Test Contribution Calculations Before Going Live

    A contribution formula should be tested before it affects the entire workforce.

    Testing is especially valuable:

    • When launching a plan
    • When changing employer matching
    • When changing eligibility
    • When changing payroll systems
    • When adding new compensation types
    • When implementing a material plan amendment

    Employers can create representative payroll scenarios that include:

    Regular salary → bonus → commission → different eligibility dates → employee contribution → employer match

    The purpose is to see whether payroll produces the result required by the plan terms.

    This type of testing may identify retirement plan payroll errors before they affect multiple employees.


    5. Reconcile Payroll and Provider Records

    Reconciliation is one of the strongest controls in the entire process.

    Payroll processing and retirement-plan administration may take place in different systems.

    Employers can periodically compare four things:

    1. What payroll says was deducted or contributed
    2. What was transmitted to the provider
    3. What appears in member records
    4. What the official plan formula requires

    These figures should logically align.

    When they do not, the difference should be investigated using an established escalation process.

    Examples may include:

    • Missing contributions
    • Duplicate transactions
    • Delayed transactions
    • Incorrect amounts
    • Incorrect employee records
    • Contribution timing differences

    CAPSA’s guidance emphasizes accurate member records and periodic review of identified errors, controls, processes, and systems.

    A Simple Reconciliation Question

    Payroll → Provider → Member Account → Plan Document

    Do all four tell the same story?

    If not, investigate.


    6. Use Controlled Procedures for Plan Changes

    Plan changes create a particularly important period of administrative risk.

    When eligibility, matching formulas, compensation definitions, or contribution rules change, employers should document:

    • What is changing
    • Effective date
    • Who approved it
    • Which systems need updating
    • Who updates each system
    • Employee communication
    • Provider communication
    • Testing
    • Final confirmation

    Without a controlled process, one system may start using new information while another continues using the previous rules.

    For example:

    Plan document updated ✓
    Payroll updated ✓
    Provider updated ✓
    Employee communication updated ✓

    All four matter.

    Controlled implementation can significantly reduce avoidable retirement plan payroll errors.


    7. Communicate Contributions and Deductions Clearly

    Employees can also act as an additional source of early detection when they understand what should appear on their pay and retirement-plan records.

    Employers should clearly explain:

    • Employee contribution options
    • Employer matching or contributions
    • Eligibility
    • Applicable limits
    • Contribution timing
    • Changes employees can make
    • Important deadlines
    • Where account information can be reviewed
    • Who to contact with questions

    This is particularly important for employer matching contributions, because employees should understand both their contribution and the employer-funded portion of the arrangement.

    Communication should continue after onboarding.

    Employees receive large amounts of information when starting a new position, so retirement-plan education should be reinforced throughout employment.


    8. Document Errors and Corrections

    Errors can still occur even when good controls exist.

    The important question becomes:

    What happens next?

    When a discrepancy is identified, employers should document:

    • What happened
    • When it occurred
    • Who was affected
    • How it was identified
    • What corrective action was taken
    • Who approved the correction
    • Whether employee communication was required
    • Whether a process change was implemented

    This creates an audit trail and can help prevent the same issue from happening again.

    Employers should not automatically assume that simply adjusting the next payroll is the appropriate correction.

    The required approach may depend on the plan type, nature of the error, period affected, tax treatment, plan documents, and applicable regulatory requirements.

    Material errors should be reviewed with appropriately qualified professionals.


    9. Review the Process as the Business Grows

    A process designed for 20 employees may not remain appropriate for 200 employees.

    Administrative controls should be reassessed when there are material changes involving:

    • Workforce size
    • Locations
    • Payroll systems
    • Compensation structures
    • Eligibility
    • Providers
    • Plan design
    • Employer contribution formulas
    • Internal responsibilities

    Growth should trigger a review of the process—not simply more transactions through the same workflow.

    Strong retirement plan governance includes asking whether existing controls remain appropriate for the organization’s current operating environment.


    Why Reconciliation Is One of the Most Important Controls

    Reconciliation deserves additional attention because payroll and retirement-plan records may exist in different systems.

    A practical reconciliation process can compare:

    Payroll Record

    What amount was deducted from the employee or calculated as the employer contribution?

    Amount Transmitted

    What amount was actually sent to the applicable provider or retirement plan?

    Provider Record

    What amount appears in the member account?

    Official Plan Formula

    What amount should have been calculated under the plan terms?

    When these amounts do not align, the organization should investigate the difference promptly.

    This process can help identify missing, duplicated, delayed, or inconsistent transactions before they remain unresolved for an extended period.

    
Retirement plan payroll errors reconciliation comparing payroll deductions, transmitted contributions, provider records, and official plan formulas

    Plan Type Matters

    Not every retirement arrangement follows the same tax, reporting, contribution, or administrative rules.

    Examples include:

    • Registered Pension Plan — RPP
    • Deferred Profit Sharing Plan — DPSP
    • Group Registered Retirement Savings Plan — Group RRSP
    • Pooled Registered Pension Plan — PRPP

    Employers should not automatically apply the requirements of one arrangement to another.

    Pension Adjustments Are One Example

    CRA guidance distinguishes between plan structures when determining whether a pension adjustment may be required.

    Employers participating in certain RPPs or DPSPs may need to calculate and report a pension adjustment.

    The original source also notes that a pension adjustment is not reported for an individual or Group RRSP or for a PRPP.

    This demonstrates why payroll administration should begin with the specific plan structure rather than a generic retirement-plan assumption.


    Compensation Type Can Affect Payroll Configuration

    Payroll treatment can also vary depending on the type of payment.

    Examples include:

    • Regular salary
    • Bonuses
    • Commissions
    • Retroactive pay
    • Other remuneration

    However, an important distinction must be maintained.

    How payroll treats compensation does not automatically determine whether that compensation should be included when calculating retirement-plan contributions.

    The applicable plan terms should determine the contribution calculation.

    For example, if the employer contribution formula uses a defined category of eligible compensation, payroll should be configured according to that definition.


    Additional Considerations for Registered Pension Plans

    Registered pension plans may involve additional statutory administration and contribution requirements depending on jurisdiction.

    For Ontario-registered pension plans, FSRA identifies contribution oversight as one of the administrator’s responsibilities and uses Form 7 contribution reporting within the applicable Ontario framework.

    These requirements should not automatically be applied to Group RRSPs, DPSPs, PRPPs, or arrangements governed under another jurisdiction.

    This is why employers should identify:

    Plan Type + Jurisdiction + Plan Terms + Payroll Treatment

    before establishing an administrative process.


    Why Retirement Plan Education Should Continue After Onboarding

    Contribution information should not disappear after an employee’s first week.

    Employers may reinforce:

    • Employee contribution choices
    • Employer matching
    • Eligibility
    • Changes employees can make
    • Deadlines
    • Plan amendments
    • Account access
    • Member support

    Ongoing communication can also complement broader retirement income education by helping employees understand how workplace contributions fit within their retirement planning.

    The purpose is not to recommend how much an individual should contribute.

    It is to make the workplace plan easier to understand.


    How Can Employers Keep Payroll and Plan Information Accurate?

    A strong process should be built around authoritative information.

    Employers can:

    • Use current official plan documents
    • Keep payroll instructions documented
    • Verify provider information
    • Maintain clear approval processes
    • Test material changes
    • Reconcile records
    • Record corrections
    • Update employee communication
    • Review controls periodically

    This is the accuracy and authenticity layer of the article.

    Do not call the heading “Authenticity Layer” in WordPress.
    The reader-facing heading above — How Can Employers Keep Payroll and Plan Information Accurate? — is much more natural.


    Why This Matters to Growing Businesses

    Administrative discrepancies create more than an accounting inconvenience.

    They may require additional work from:

    • HR
    • Payroll
    • Finance
    • Management
    • The retirement-plan provider
    • External advisers

    A structured administration process may help businesses:

    • Identify discrepancies earlier
    • Clarify responsibilities
    • Maintain consistent records
    • Coordinate system changes
    • Document corrective actions
    • Improve employee communication

    However, these controls should not be presented as guaranteeing:

    • Error-free administration
    • Higher participation
    • Better retention
    • Increased employee trust
    • Better investment outcomes

    Their appropriate purpose is supporting consistent administration, stronger governance, and clearer communication.

    
Retirement plan payroll errors controls for a growing Canadian business with multiple employees, locations, payroll schedules, eligibility rules, and contribution processes.

    Important Implementation Boundaries

    Payroll and retirement-plan administration can involve:

    • Tax
    • Payroll
    • Pension requirements
    • Employment requirements
    • Privacy
    • Recordkeeping
    • Plan documents
    • Service-provider contracts
    • Regulatory obligations

    The applicable approach can depend on:

    • Plan type
    • Jurisdiction
    • Contribution formula
    • Compensation definition
    • Employee classification
    • Payroll system
    • Provider arrangement
    • Nature of an error

    Employers should obtain appropriately qualified payroll, tax, pension, legal, HR, and retirement-plan advice before making material contribution changes or correcting significant errors.


    Need Help Coordinate Your Workplace Retirement Plan More Clearly?

    Open Access Limited may support employers with the retirement-plan side of administration, including:

    • Documenting plan-specific eligibility and contribution provisions
    • Providing contribution and enrolment materials
    • Communicating employer and employee contribution rules
    • Supporting member education
    • Coordinating retirement-plan information with the employer
    • Supporting ongoing review of the group retirement arrangement

    Open Access Limited should be positioned as supporting plan design, contribution information, enrolment, education, and retirement-plan administration coordination.

    The employer remains responsible for its payroll processes and for obtaining appropriate payroll, tax, legal, pension, and regulatory advice where required.

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6, Canada

    Toll-Free: 1-866-625-4777
    General: 416-364-8877
    Fax: 416-955-4878
    Email: inquiry@OpenAccessLtd.com
    Website: www.OpenAccessLtd.com


    Frequently Asked Questions

    What Is a Common Cause of Retirement Plan Payroll Errors?

    One common cause is inconsistency between official plan terms and payroll configuration. Eligibility rules, contribution formulas, compensation definitions, and effective dates should be reflected accurately across systems.

    How Often Should Payroll and Provider Records Be Reconciled?

    The appropriate frequency depends on the arrangement and operating environment. Employers should establish a periodic reconciliation process appropriate to their plan and review it as the organization grows.

    Should Bonuses and Commissions Always Be Included in Retirement Contributions?

    Not necessarily. Whether particular compensation is included should be determined by the applicable plan terms and relevant requirements rather than assumed from payroll treatment alone.

    Are Group RRSP, DPSP, RPP, and PRPP Payroll Rules the Same?

    No. Tax, reporting, contribution, and administrative requirements can differ by plan structure.

    Can Employers Simply Correct a Contribution Error on the Next Payroll?

    Not necessarily. The appropriate correction may depend on the type of plan, nature and period of the error, tax treatment, plan documents, and regulatory requirements.

    Can Open Access Limited Guarantee Payroll Accuracy?

    No. Open Access Limited may support plan design, contribution information, enrolment, employee education, and retirement-plan coordination, while employers remain responsible for their own payroll processes.


    Final Thoughts

    As a company grows, retirement plan payroll errors can become more difficult to prevent through informal processes alone.

    A stronger approach is systematic:

    Translate the plan → Define responsibility → Test calculations → Reconcile records → Control changes → Communicate clearly → Document corrections → Review again as the business grows.

    The goal is not to claim that errors will never happen.

    The goal is to make discrepancies easier to prevent, easier to identify, and easier to address through clear processes, reliable records, and appropriate governance.


    References

    1. Canadian Association of Pension Supervisory Authorities (CAPSA) (2024). Guideline No. 3: Guideline for Capital Accumulation Plans.
    2. Canada Revenue Agency (2026). T4001 Employers’ Guide — Payroll Deductions and Remittances.
    3. Canada Revenue Agency (2026). Payroll Deductions Formulas.
    4. Canada Revenue Agency. Pension Adjustment Guide.
    5. Canada Revenue Agency (2026). Pension Adjustment — Personal Income Tax.
    6. Financial Services Regulatory Authority of Ontario (FSRA). Pension Plan Administrator Roles and Responsibilities.
    7. Financial Services Regulatory Authority of Ontario (FSRA). Form 7 — Summary of Contributions.
    8. Open Access Limited. Current Group Retirement Plan and Plan-Specific Enrolment Materials.

  • How Can Canadian Businesses Structure Employer Matching Contributions While Managing Long-Term Costs?

    How Can Canadian Businesses Structure Employer Matching Contributions While Managing Long-Term Costs?

    Employer matching contributions can be a valuable part of a workplace retirement plan, but the strongest contribution strategy is not necessarily the one with the highest percentage.

    Canadian employers may use a percentage of employee pay, a contribution tied to employee savings, a fixed-dollar formula, or another structure permitted under the applicable retirement plan.

    The more important question is whether the contribution formula is clear to employees, aligned with the purpose of the plan, financially sustainable, and administratively workable.

    A well-designed approach to employer matching contributions should therefore balance employee participation with budget capacity, payroll administration, plan structure, eligibility rules, communication, and ongoing governance.

    Quick Answer: How Should Employers Structure Matching Contributions?

    Canadian businesses can structure employer matching contributions by first defining the purpose of the retirement plan, modelling employer costs under different participation scenarios, choosing an appropriate plan structure, keeping the formula easy to understand, coordinating payroll and administration, communicating requirements clearly, and reviewing the arrangement periodically.

    The goal should be a clear and sustainable contribution structure—not simply the highest possible employer match.

    Why Employer Matching Contributions Require Careful Planning

    Employer contributions represent a real compensation and plan cost.

    Before introducing or changing a formula, employers may need to consider:

    • The purpose of the retirement plan
    • Budget and cash-flow capacity
    • Workforce characteristics
    • Eligibility rules
    • Payroll requirements
    • Contribution timing
    • Applicable tax rules
    • Plan type
    • Employee participation
    • Contribution caps
    • Administrative complexity
    • Future workforce growth

    The source file specifically recommends considering different participation scenarios because an arrangement that appears affordable at today’s participation level may cost substantially more if more employees begin contributing or payroll grows.

    There is no single formula that works for every Canadian employer.

    8 Smart Ways to Structure Employer Matching Contributions

    1. Define the Purpose of the Employer Contribution

    Start by deciding what the contribution structure is intended to support.

    The objective may include:

    • Encouraging retirement saving
    • Supporting employee participation
    • Strengthening total compensation
    • Supporting a profit-sharing philosophy
    • Providing a structured workplace savings benefit
    • Supporting another clearly documented plan objective

    This matters because employer matching contributions should be designed around the purpose of the plan—not added simply because another employer offers a particular percentage.

    A documented purpose also helps future governance reviews.

    2. Build a Sustainable Employer Budget

    Before finalizing a formula, model the potential cost using actual payroll information.

    Consider several scenarios:

    • Current participation
    • Higher employee participation
    • Workforce growth
    • Higher average compensation
    • Changes in eligibility
    • Different contribution caps
    • Different matching formulas

    For example, a formula that is manageable when 40% of eligible employees participate may produce a very different employer cost if participation rises to 75%.

    The objective is not to predict employee behaviour.

    It is to understand the range of possible costs before committing to employer matching contributions.

    3. Choose the Right Retirement Plan Structure

    Employer contributions can work differently depending on the type of retirement arrangement.

    For example, a Group RRSP and a DPSP are not interchangeable.

    The source file notes that employer-made Group RRSP contributions may have specific payroll and tax treatment, while a DPSP has its own rules and only participating employers contribute to it.

    Depending on the organization, a structure might involve:

    • Group RRSP
    • DPSP
    • Registered pension plan
    • PRPP
    • Another permitted group retirement arrangement

    The appropriate structure depends on plan objectives, payroll, tax treatment, legal requirements, and administration.

    4. Keep the Matching Formula Easy to Understand

    Employees should be able to understand the employer contribution without needing to decode a complicated formula.

    Communication should explain:

    • What percentage or dollar amount applies
    • Whether an employee contribution is required
    • The maximum employer contribution
    • Eligibility requirements
    • Waiting periods
    • Contribution timing
    • Any applicable limits

    A simple employer matching contributions formula can be easier for employees to understand and easier for HR and payroll teams to administer.

    Complexity should only be added when there is a clear plan reason for it.

    5. Explain Exactly What Employees Need to Do

    Employees should know what actions are required to receive the employer contribution.

    A clear explanation might answer:

    • Do I need to contribute first?
    • What percentage do I need to contribute?
    • What is the maximum employer contribution?
    • When does matching begin?
    • When are contributions deposited?
    • Is there a waiting period?
    • Can the formula change?
    • Where are the official plan terms?

    Clear communication reduces uncertainty around employer matching contributions and prevents employees from relying on assumptions.

    6. Coordinate Payroll and Administration Before Launch

    Contribution design and payroll administration need to match.

    Employers should confirm:

    • Payroll coding
    • Contribution calculations
    • Eligibility dates
    • Provider requirements
    • Contribution timing
    • Reporting
    • Reconciliation
    • Employee records
    • Plan administration responsibilities

    Even a strong matching formula can create problems if payroll and provider processes are not aligned.

    This is why contribution design should connect with broader retirement plan governance rather than being treated only as an HR benefit decision.

    For example, when an employee becomes eligible, there should be a clear process showing:

    1. When eligibility begins
    2. When payroll deductions start
    3. How the employer match is calculated
    4. When funds are transmitted
    5. How errors are identified and corrected

    Clear administration helps ensure employer matching contributions operate as described to employees.

    7. Review the Contribution Structure Regularly

    A contribution formula should not automatically remain unchanged forever.

    The employer should periodically consider whether the arrangement still fits:

    • Plan objectives
    • Financial capacity
    • Workforce size
    • Payroll levels
    • Employee participation
    • Compensation strategy
    • Plan structure
    • Administrative requirements

    A formula that worked for a business with 25 employees may need a different review when that organization grows to 100 employees.

    Similarly, changing salaries or eligibility rules may alter employer costs even when the matching percentage stays the same.

    Regular review helps keep employer matching contributions aligned with both the retirement plan and the organization’s financial capacity.


    How Can Employers Balance Participation and Cost?

    This is where the strategy becomes particularly important.

    An employer may want employees to understand and use the benefit while also avoiding an unpredictable long-term cost commitment.

    The answer is not necessarily to reduce the benefit.

    Instead, employers can improve the quality of the design through:

    • Clearly defined contribution limits
    • Sustainable caps
    • Eligibility rules
    • Accurate cost modelling
    • Clear employee communication
    • Payroll controls
    • Periodic review

    The employer can model several participation levels before implementation.

    For example:

    Current Participation → Higher Participation → Workforce Growth → Higher Payroll

    The key question is:

    Can the organization continue funding the contribution formula if more eligible employees actually use the benefit?

    That is a healthier question than designing the plan around today’s lowest-cost scenario.


    Cost Modelling Should Include More Than Today’s Payroll

    A common planning mistake is to calculate employer cost using current payroll and current participation only.

    That provides only one snapshot.

    A stronger analysis should consider how employer matching contributions may change when:

    Employee Participation Increases

    More eligible employees may decide to participate after improved education or communication.

    Compensation Increases

    If the employer contribution is tied to salary, cost may increase as compensation increases.

    The Workforce Expands

    Hiring can increase the number of eligible plan members.

    Eligibility Changes

    Expanding eligibility may affect the number of employees receiving employer contributions.

    Contribution Caps Change

    A higher maximum employer contribution can materially affect future cost.

    Scenario modelling helps management understand the range of potential commitments before changing the plan.


    How Should Employer Matching Be Explained to Employees?

    Employee communication should answer practical questions quickly.

    How Much Does the Employer Contribute?

    Explain the formula clearly using the plan’s actual terms.

    What Must the Employee Do?

    If the employee must contribute to receive the match, say so clearly.

    Is There a Maximum?

    Employees should understand applicable contribution caps.

    When Do Contributions Begin?

    Clearly explain eligibility dates and waiting periods.

    Can the Formula Change?

    Where appropriate, explain that the contribution structure is governed by plan documents and may be subject to permitted amendments.

    Where Can Employees Get Help?

    Provide a clear member-support contact and access to official plan documents.

    Clear communication makes the employer contribution easier to value.


    Why Education Should Continue After Enrolment

    Employees may first hear about the retirement plan during onboarding—when they are also processing payroll information, workplace policies, training, benefits, technology, and job expectations.

    That is a lot of information at once.

    Employers can reinforce employer matching contributions later through:

    • Annual benefit communication
    • Plan reminders
    • Member education sessions
    • Digital plan materials
    • Portal resources
    • Financial-wellness education
    • Communications when plan features change

    CAPSA’s guidance emphasizes ongoing member education rather than treating enrolment as the only communication event.

    Repeated education gives employees another opportunity to understand the employer-funded portion of their retirement plan.


    How Can Employers Keep Contribution Information Accurate and Reliable?

    The communication process should always be grounded in current information.

    Employers should:

    • Use current official plan documents
    • Confirm contribution formulas with the provider
    • Verify payroll treatment
    • Avoid unsupported promises
    • Update materials after plan changes
    • Document decisions
    • Review employee-facing explanations
    • Provide a clear contact point for questions

    If a plain-language summary conflicts with the official plan document, the plan document should govern.

    This authenticity layer is especially important when contribution formulas are adjusted over time.


    How Employer Matching Fits With Retirement Plan Governance

    Employer matching contributions should be part of the broader retirement plan governance process.

    Employers should document:

    • Why the contribution formula was selected
    • What cost scenarios were considered
    • Who approved the arrangement
    • How payroll implementation was reviewed
    • How employees were informed
    • When the structure will be reviewed again

    This creates accountability and makes future plan reviews easier.

    It also reduces reliance on institutional memory when HR, finance, management, or provider contacts change.


    Employer Matching and Inclusive Retirement Benefits

    Employers should also consider how employees across different career stages and income levels understand the matching formula.

    This does not mean recommending different personal contribution amounts.

    Instead, an inclusive retirement benefits approach can ensure employees receive:

    • Clear eligibility information
    • Plain-language matching explanations
    • Accessible education
    • Multiple learning formats
    • Ongoing support

    Employees should be able to understand how the benefit works even if they make different personal contribution decisions.


    Employer Matching and Retirement Income Education

    The employer contribution can also be explained within the employee’s broader retirement income education.

    For example, employees can learn that retirement income may come from several sources, including:

    • Government programs
    • Workplace retirement benefits
    • Personal savings
    • Investments

    The employer matching contribution is one component within that broader picture.

    Employers should explain the workplace plan clearly without estimating an employee’s future retirement income or promising a particular outcome.

    Employer matching contributions for Canadian businesses with clear plan design, employee participation, payroll coordination, and sustainable long-term costs.

    What Employers Should Avoid

    When designing or communicating employer matching contributions, employers should avoid:

    • Selecting a formula without modelling future cost
    • Making the formula unnecessarily complicated
    • Treating different retirement structures as interchangeable
    • Promising that the match will never change when plan terms permit changes
    • Guaranteeing increased participation
    • Guaranteeing improved retention
    • Recommending a personal contribution level
    • Allowing payroll and plan documents to conflict
    • Relying only on onboarding for employee education

    The strongest approach is clear, documented, administratively workable, and financially sustainable.


    Why This Matters to Business Owners

    Employer contributions are both a retirement-plan feature and a compensation cost.

    That means decisions about employer matching contributions should be considered alongside:

    • Cash flow
    • Compensation strategy
    • Workforce growth
    • Payroll
    • Employee communication
    • Plan administration
    • Long-term business planning

    The objective should not be to maximize the percentage simply because a higher number appears more attractive.

    A more useful objective is:

    Create a contribution arrangement employees can understand and the business can sustain.

    That is a stronger foundation for long-term plan management.


    Important Implementation Boundaries

    Employer contribution arrangements can involve:

    • Tax
    • Payroll
    • Pension
    • Employment requirements
    • Plan documents
    • Contribution limits
    • Governance
    • Communication

    Treatment can differ materially depending on whether the arrangement involves a:

    • Group RRSP
    • DPSP
    • Registered pension plan
    • Pooled registered pension plan
    • Other retirement-savings structure

    Employers should obtain appropriately qualified retirement-plan, legal, tax, payroll, pension, and compliance advice before introducing or materially changing employer matching contributions.

    This includes changes to eligibility, contribution caps, payroll treatment, plan combinations, or material employee communication.

    Employees who require individualized financial or tax advice should be directed to qualified professionals.


    Need Help Structuring Employer Contributions More Clearly?

    A well-designed employer contribution arrangement should align the workplace retirement plan with the organization’s objectives, administration, employee communication, and financial capacity.

    Open Access Limited may support employers with the retirement-plan component of this process, including:

    • Reviewing available group retirement structures
    • Establishing plan-specific eligibility and contribution provisions
    • Documenting employer matching rules
    • Coordinating plan administration
    • Preparing enrolment and member materials
    • Supporting ongoing employee education
    • Providing member support

    Open Access Limited materials also describe employer contributions that may be structured as a percentage of salary or a fixed-dollar amount, depending on plan design.

    Employers remain responsible for determining the financial commitment appropriate for their organization and obtaining tax, payroll, legal, and other professional advice where required.

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6, Canada

    Toll-Free: 1-866-625-4777
    General: 416-364-8877
    Fax: 416-955-4878
    Email: inquiry@OpenAccessLtd.com
    Website: www.OpenAccessLtd.com

    Employer matching contributions cost modelling for Canadian businesses across employee participation, payroll growth, workforce expansion, eligibility changes, and contribution caps.

    Frequently Asked Questions About Employer Matching Contributions

    Are Employer Matching Contributions Required to Be the Same for Every Business?

    No. There is no single contribution formula that is appropriate for every organization. Plan type, workforce characteristics, compensation, financial resources, and organizational objectives may all affect the design.

    Should Employers Offer the Highest Match They Can Afford Today?

    Not necessarily. Employers should also consider how the cost could change with increased participation, higher salaries, workforce growth, or changes in eligibility.

    Can an Employer Matching Formula Change?

    That depends on the governing plan terms and applicable requirements. Employers should avoid describing a reviewable or amendable contribution as permanently guaranteed.

    Can Employers Recommend How Much Employees Should Contribute?

    Employers can explain the plan and matching formula, but personalized contribution recommendations should be handled by appropriately qualified professionals.

    Are Group RRSPs and DPSPs the Same?

    No. They operate differently and may have different contribution, tax, payroll, eligibility, and administrative requirements.

    How Often Should Employer Contributions Be Reviewed?

    Employers should periodically reassess the contribution arrangement as payroll, participation, workforce composition, plan objectives, and financial circumstances change.


    Final Thoughts

    Employer matching contributions can add meaningful value to a workplace retirement plan when they are designed with both employees and the business in mind.

    The strongest contribution strategy is not necessarily the largest.

    It is one that is:

    Clear to employees. Sustainable for the employer. Accurate in payroll. Consistent with the plan. Reviewed over time.

    By defining the purpose, modelling long-term costs, selecting an appropriate plan structure, communicating clearly, coordinating administration, and reviewing the arrangement regularly, Canadian businesses can create a more durable employer contribution strategy without making promises about employee behaviour or business outcomes.

    Employer matching contributions explained to Canadian employees with clear eligibility rules, contribution limits, payroll timing, enrolment information, and retirement plan support.

    REFERENCES

    1. Canadian Association of Pension Supervisory Authorities — Guideline No. 3: Guideline for Capital Accumulation Plans
    2. Canada Revenue Agency — Contributions to Savings and Pension Plans
    3. Canada Revenue Agency — Register a Deferred Profit Sharing Plan
    4. Canada Revenue Agency — RRSPs and Other Registered Plans for Retirement
    5. Open Access Limited — Group Retirement Plans in Canada
    6. Open Access Limited — Setting Up a Group Retirement Plan for Your Business in Canada