Employees may receive fraudulent messages, suspicious investment offers, or communications that appear to come from a financial institution, government agency, adviser, or retirement-plan provider.
For Canadian employers, raising awareness about retirement savings scams can help employees recognize common warning signs, understand how their workplace plan provider normally communicates, and know where to verify or report a suspicious message.
Employers are not responsible for employees’ personal financial decisions, and awareness education cannot guarantee that fraud will be prevented.
However, clear and consistent communication can help employees pause before sharing information or acting on an unexpected investment offer.
Quick Answer: How Can Employers Help Protect Employees From Retirement Savings Scams?
“Employ ers can reduce the risk of retirement savings scams by teaching employees how to recognize warning signs and verify suspicious communications
Canadian businesses can support employees by:
- Sharing common warning signs of investment fraud.
- Explaining the plan provider’s official communication channels.
- Reminding employees not to share sensitive information through unverified links.
- Encouraging employees to verify suspicious messages directly with the provider.
- Using simple, plain-language fraud-awareness education.
- Providing clear information about where suspected fraud can be reported.
- Repeating fraud-awareness reminders throughout employment.
The goal is not to tell employees whether a particular investment is safe.
The employer’s role is to provide general awareness information and direct employees to official sources.
Why Retirement Savings Scams Matter
Fraudulent investment messages can appear professional and convincing.
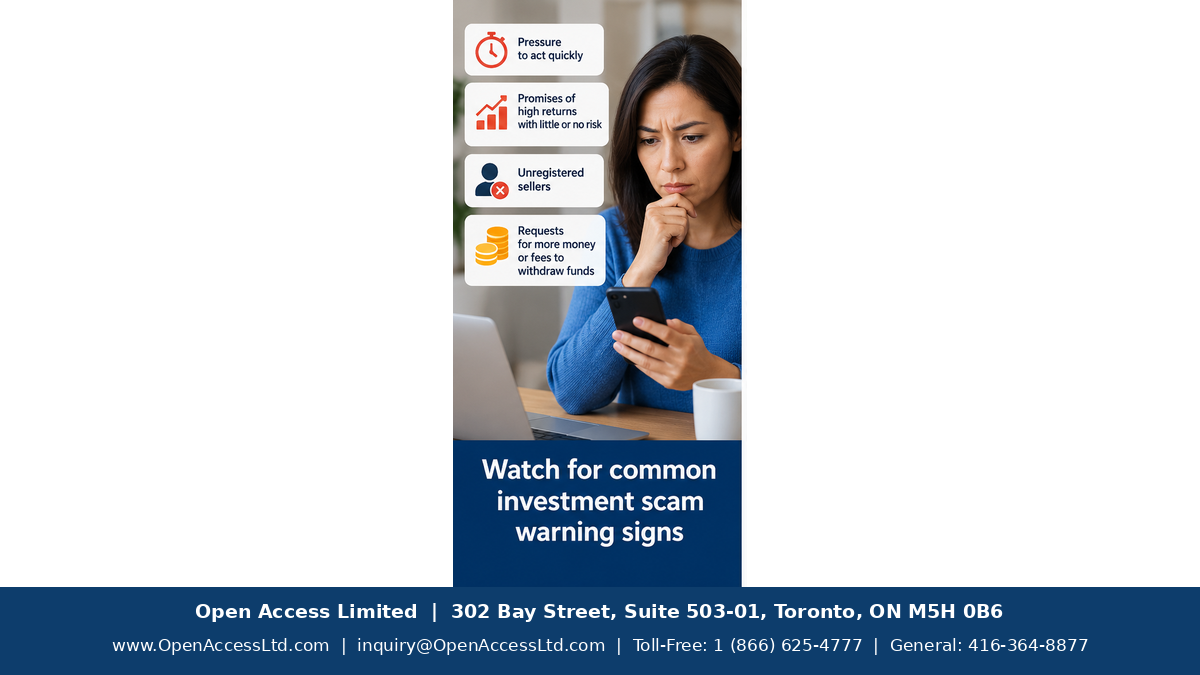
According to the Canadian Securities Administrators, warning signs of investment fraud may include:
- Pressure to act quickly
- Promises of high returns with little or no risk
- Unregistered sellers
- Exclusive or limited-time offers
- Repeated requests for additional money
- Requests for fees before money can be withdrawn
Employees may also receive messages that appear to come from a trusted financial institution or retirement-plan provider.
That is why employees should be encouraged to verify unexpected communications using official contact information rather than relying on contact details contained in the suspicious message itself.
1. Share Common Investment Fraud Warning Signs
The first step in reducing exposure to retirement savings scams is awareness.
Employers can periodically share general information from Canadian regulators about common fraud warning signs.
The communication should be educational rather than alarmist.
“Retirement savings scams often rely on urgency, imperson ation, or misleading investment claims, so employees should verify unusual requests through official provider channels.”
For example, employees can be reminded to be cautious when someone:
- Pressures them to make an immediate decision
- Promises unusually high returns with little or no risk
- Claims an opportunity is available only to a select group
- Repeatedly requests more money
- Asks for additional fees before releasing funds
Simple reminders may help employees pause and verify an offer before taking action.
2. Explain Official Communication Channels
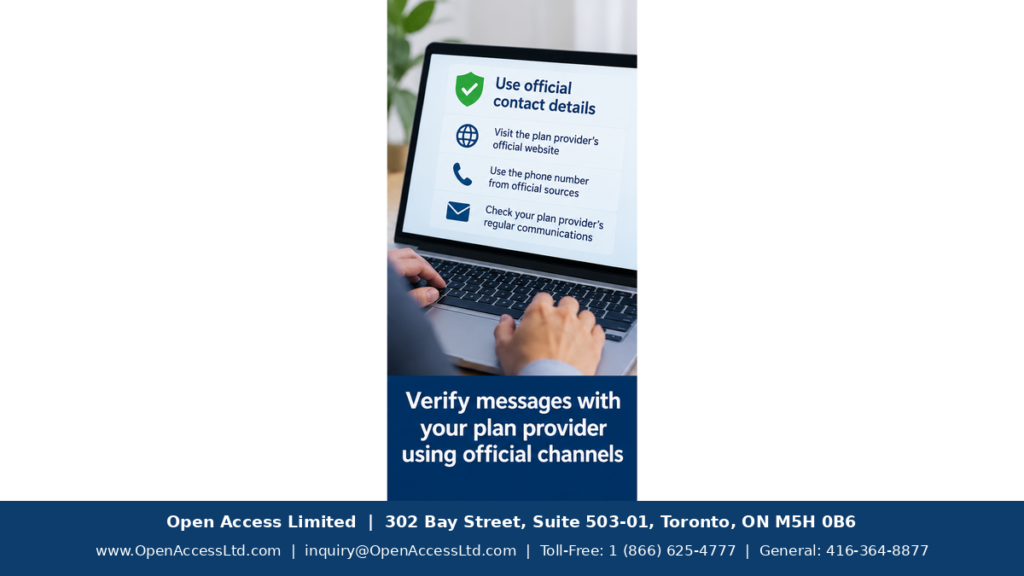
Employees should know how their workplace retirement-plan provider normally communicates with them.
Employers can make it easy for employees to find:
- The provider’s official website
- Official telephone numbers
- Official email contact information
- Member portal information
- Plan documents and official forms
This can help employees compare an unexpected message with the communication channels normally used by their provider.
If an employee is unsure whether a message is legitimate, the safest approach is to contact the provider directly using official contact details.
3. Protect Personal and Financial Information
Fraud attempts may seek sensitive personal or financial information.
Employees can be reminded not to provide information such as:
- Social Insurance Numbers
- Banking information
- Passwords
- Retirement account credentials
- Other confidential account details
through unverified links, emails, text messages, or other unexpected communications.
Employers should also never ask employees to share passwords or account credentials as part of a fraud-awareness process.
4. Encourage Direct Provider Verification
If an employee receives an unexpected message about workplace retirement savings, the employee should be encouraged to verify it through the plan provider’s official contact channels.
A useful general principle is:
Do not reply to the suspicious message first. Verify the source independently.
For example, an employee can use the telephone number, website, member portal, or contact information contained in official workplace plan materials.
This may reduce the risk of responding directly to someone impersonating the provider.
5. Use Plain-Language Fraud Education
Fraud-awareness education is more useful when employees can understand and apply it quickly.
Employers do not need highly technical cybersecurity language to communicate the basic message.
Short reminders can be effective.
For example:
Before clicking a link, sharing personal information, or acting on an unexpected message about your retirement savings, verify the source using the contact details in the official plan materials. If you are unsure whether a message is from the plan provider, contact the provider directly.
Any sample wording should be reviewed against current plan documents and the provider’s official communication materials before being used.
6. Give Employees a Clear Reporting Pathway
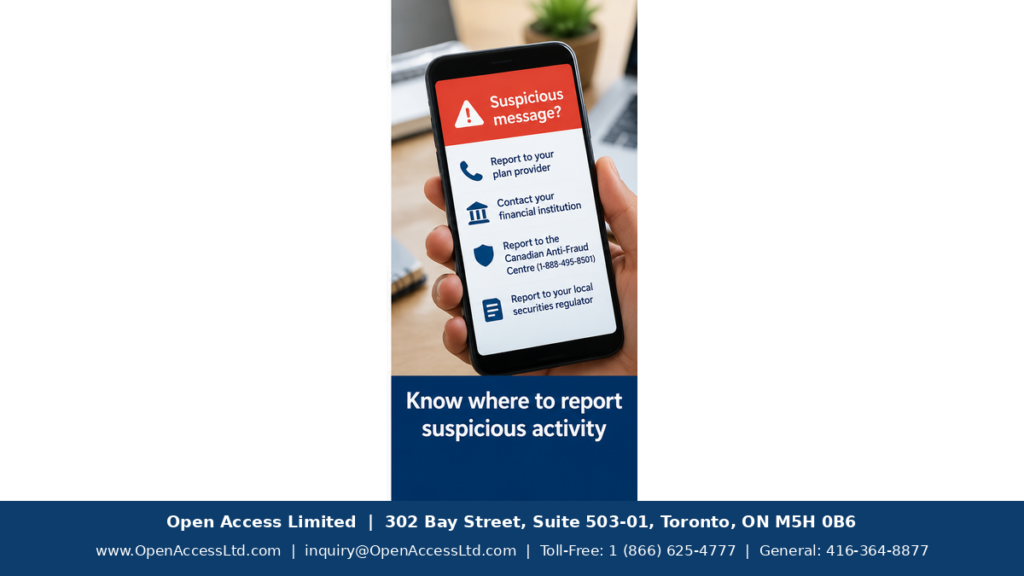
Employees should also know where they may report suspected fraud.
Depending on the circumstances, this may include:
- The workplace retirement-plan provider
- The employee’s financial institution
- The Canadian Anti-Fraud Centre
- Local police
- The applicable securities regulator
The Canadian Anti-Fraud Centre accepts reports of fraud and cybercrime online and by telephone at 1-888-495-8501.
Canadian securities regulators also provide resources for reporting suspected investment fraud.
Providing employees with a clear reporting pathway may help them respond more quickly when something appears suspicious.
7. Make Fraud Awareness an Ongoing Process
Fraud methods change over time.
For that reason, fraud-awareness education should not be limited to a single onboarding message.
Employers may consider providing reminders:
- During onboarding
- During workplace retirement-plan education
- When provider communication methods change
- Periodically throughout employment
CAPSA guidance for capital accumulation plans recognizes that member communication and education continue beyond initial enrolment.
Regular reminders can help keep fraud-awareness information current and easier for employees to remember.
What Employers Should Avoid
Employers should be careful not to go beyond general fraud-awareness education.
They should avoid:
- Giving individual investment advice
- Deciding whether a specific investment opportunity is legitimate
- Promising that a message or investment is safe
- Asking employees to provide passwords or account credentials
- Using alarmist language that may discourage employees from participating in the retirement plan
- Assuming that a particular employee or employee group is more likely to become a fraud victim
Questions about whether a particular investment or seller is legitimate should be referred to the appropriate securities regulator or another qualified source.
Can Employees Check Whether an Investment Professional Is Registered?
Yes.
The Canadian Securities Administrators state that securities professionals generally need to be registered with the securities regulator in each province or territory in which they conduct business.
Employees who are considering an investment opportunity can be directed to official securities-regulator resources, including the National Registration Search, to check registration information.
The employer should not perform an investment suitability assessment on the employee’s behalf.
What Should an Employee Do After Receiving a Suspicious Retirement Savings Message?
A simple process may help:
Pause → Do Not Share Information → Verify Independently → Contact the Provider → Report Suspected Fraud
Employees should avoid using contact information contained only within the suspicious message.
Instead, they should use official plan materials or trusted government and regulator sources.
Important Boundary for Canadian Employers
This article focuses on general employee awareness regarding retirement savings scams and investment fraud.
It does not address an employer’s own cybersecurity, privacy, or breach-reporting obligations involving payroll or retirement-plan data.
Those responsibilities may require qualified legal, privacy, cybersecurity, or other professional advice.
Employers should also confirm the security practices and official communication methods of their own retirement-plan provider directly with that provider.
How Open Access Limited May Support Fraud-Awareness Communication
Open Access Limited’s public materials include member resources, contact channels, member forms, a member portal, a trusted contact person form, and complaint-related information.
Where a workplace retirement plan is provided through Open Access Limited, employers may direct employees to official Open Access Limited contact information when an employee needs to verify a message relating to the plan.
Employers should confirm current provider practices directly with Open Access Limited rather than making assumptions about security controls.
Open Access Limited
302 Bay Street, Suite 503-01
Toronto, ON M5H 0B6, Canada
Toll-Free: 1 (866) 625-4777
General: 416-364-8877
Fax: 416-955-4878
Email: inquiry@OpenAccessLtd.com
Website: www.OpenAccessLtd.com
Frequently Asked Questions
What Are Common Warning Signs of Retirement Savings Scams?
Common warning signs may include pressure to act immediately, promises of unusually high returns with little or no risk, unregistered sellers, exclusive offers, repeated requests for more money, or demands for fees before funds can be released.
Should Employees Click a Link in an Unexpected Retirement-Plan Message?
Employees should first verify the source using the official contact information contained in their workplace retirement-plan materials or provider website.
Can an Employer Tell an Employee Whether an Investment Offer Is Legitimate?
Employers should generally avoid evaluating specific investment opportunities. Questions about the legitimacy or registration of an investment seller should be directed to the appropriate securities regulator or another qualified authority.
What Personal Information Should Employees Avoid Sharing?
Employees should be cautious about sharing Social Insurance Numbers, banking information, passwords, account credentials, or other confidential financial information through unverified communications.
Where Can Employees Report Suspected Investment Fraud in Canada?
Possible reporting channels include the Canadian Anti-Fraud Centre, local police, the relevant financial institution, the retirement-plan provider, and the applicable provincial or territorial securities regulator.
Should Fraud Awareness Be Included Only During Employee Onboarding?
No. Because fraud methods and provider communication practices can change, awareness information may be more useful when it is refreshed periodically.
Can Employers Guarantee That Fraud Awareness Will Prevent Scams?
No. Awareness education may reduce risk and help employees recognize warning signs, but it cannot guarantee that fraud will be prevented.
Final Thoughts
Helping employees recognize retirement savings scams does not require an employer to become an investment adviser or cybersecurity expert.
A practical employer approach is to:
Educate → Verify → Protect Information → Refer to Official Sources → Explain Reporting Options → Repeat the Message
Clear communication can help employees recognize suspicious messages, protect personal information, verify communications through official channels, and understand where to seek help.
The strongest approach is one that provides useful information while maintaining appropriate boundaries between workplace education and individual financial or investment advice.
“A consistent fraud-awareness program can help employees identify retirement savings scams earlier and make safer decisions about their workplace retirement savings.
References
- Canadian Securities Administrators (CSA) — Know the Red Flags of Fraud, updated June 18, 2025.
https://www.securities-administrators.ca/investor-tools/avoiding-fraud/know-the-red-flags-of-fraud/ - Canadian Securities Administrators (CSA) — Are They Registered?, updated January 13, 2026.
https://www.securities-administrators.ca/investor-tools/are-they-registered/ - Canadian Anti-Fraud Centre (CAFC) — Report fraud and cybercrime, modified November 27, 2025.
https://antifraudcentre-centreantifraude.ca/report-signalez-eng.htm - Canadian Association of Pension Supervisory Authorities (CAPSA) — Guideline No. 3: Guideline for Capital Accumulation Plans, September 9, 2024.
- Open Access Limited — Member Resources, Member Forms, Plan-Specific Enrolment Resources, and Contact Us.
Leave a Reply