Tag: Canadian Employers

  • How Can Canadian Businesses Help Employees Protect Their Workplace Retirement Savings From Scams and Investment Fraud?

    How Can Canadian Businesses Help Employees Protect Their Workplace Retirement Savings From Scams and Investment Fraud?

    Employees may receive fraudulent messages, suspicious investment offers, or communications that appear to come from a financial institution, government agency, adviser, or retirement-plan provider.

    For Canadian employers, raising awareness about retirement savings scams can help employees recognize common warning signs, understand how their workplace plan provider normally communicates, and know where to verify or report a suspicious message.

    Employers are not responsible for employees’ personal financial decisions, and awareness education cannot guarantee that fraud will be prevented.

    However, clear and consistent communication can help employees pause before sharing information or acting on an unexpected investment offer.

    Quick Answer: How Can Employers Help Protect Employees From Retirement Savings Scams?

    “Employ ers can reduce the risk of retirement savings scams by teaching employees how to recognize warning signs and verify suspicious communications

    Canadian businesses can support employees by:

    1. Sharing common warning signs of investment fraud.
    2. Explaining the plan provider’s official communication channels.
    3. Reminding employees not to share sensitive information through unverified links.
    4. Encouraging employees to verify suspicious messages directly with the provider.
    5. Using simple, plain-language fraud-awareness education.
    6. Providing clear information about where suspected fraud can be reported.
    7. Repeating fraud-awareness reminders throughout employment.

    The goal is not to tell employees whether a particular investment is safe.

    The employer’s role is to provide general awareness information and direct employees to official sources.

    Why Retirement Savings Scams Matter

    Fraudulent investment messages can appear professional and convincing.

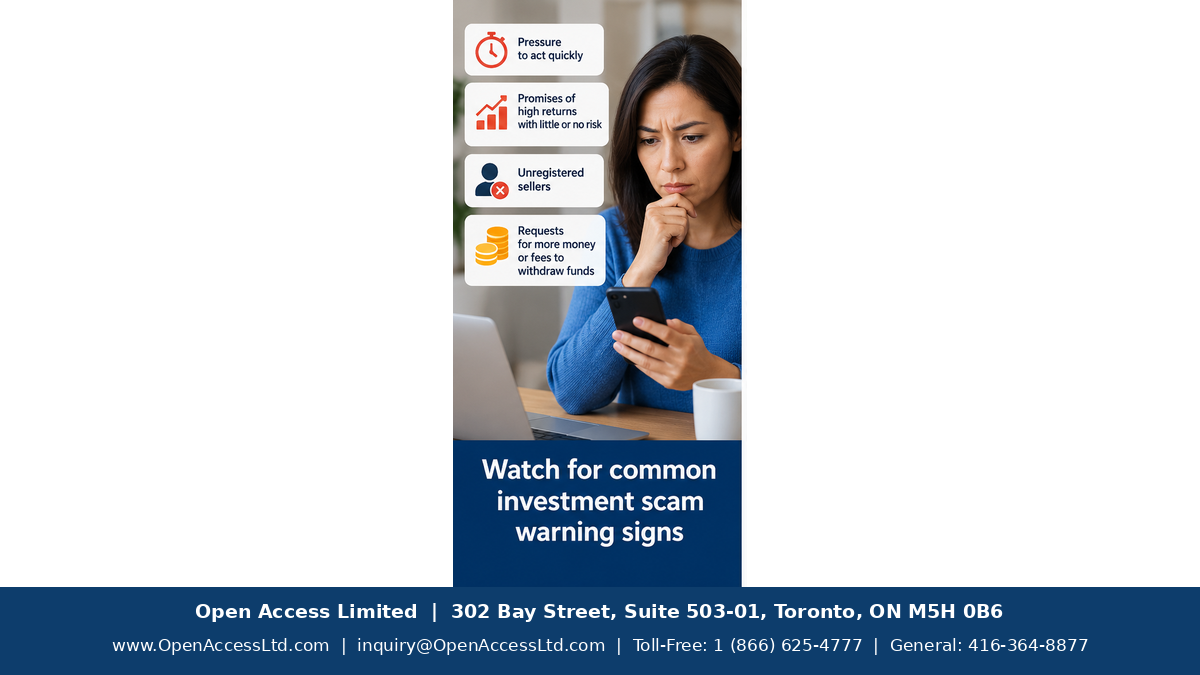
    According to the Canadian Securities Administrators, warning signs of investment fraud may include:

    • Pressure to act quickly
    • Promises of high returns with little or no risk
    • Unregistered sellers
    • Exclusive or limited-time offers
    • Repeated requests for additional money
    • Requests for fees before money can be withdrawn

    Employees may also receive messages that appear to come from a trusted financial institution or retirement-plan provider.

    That is why employees should be encouraged to verify unexpected communications using official contact information rather than relying on contact details contained in the suspicious message itself.
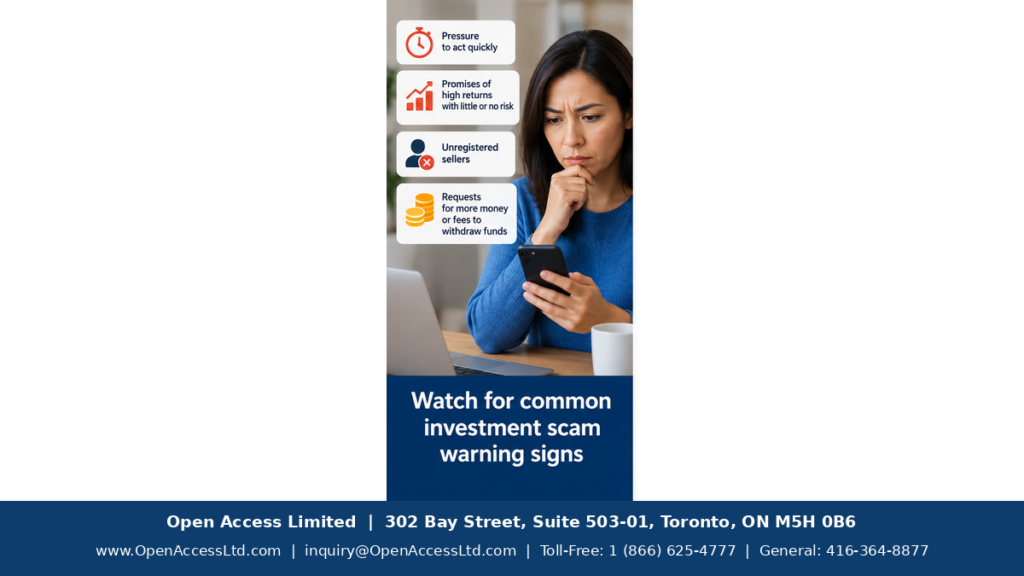
    Retirement savings scams awareness for Canadian employees showing common fraud warning signs and official verification steps.

    1. Share Common Investment Fraud Warning Signs

    The first step in reducing exposure to retirement savings scams is awareness.

    Employers can periodically share general information from Canadian regulators about common fraud warning signs.

    The communication should be educational rather than alarmist.

    “Retirement savings scams often rely on urgency, imperson ation, or misleading investment claims, so employees should verify unusual requests through official provider channels.”

    For example, employees can be reminded to be cautious when someone:

    • Pressures them to make an immediate decision
    • Promises unusually high returns with little or no risk
    • Claims an opportunity is available only to a select group
    • Repeatedly requests more money
    • Asks for additional fees before releasing funds

    Simple reminders may help employees pause and verify an offer before taking action.
    Investment fraud warning signs including pressure to act quickly, promises of high returns, unregistered sellers, and requests for personal information.

    2. Explain Official Communication Channels

    Employees should know how their workplace retirement-plan provider normally communicates with them.

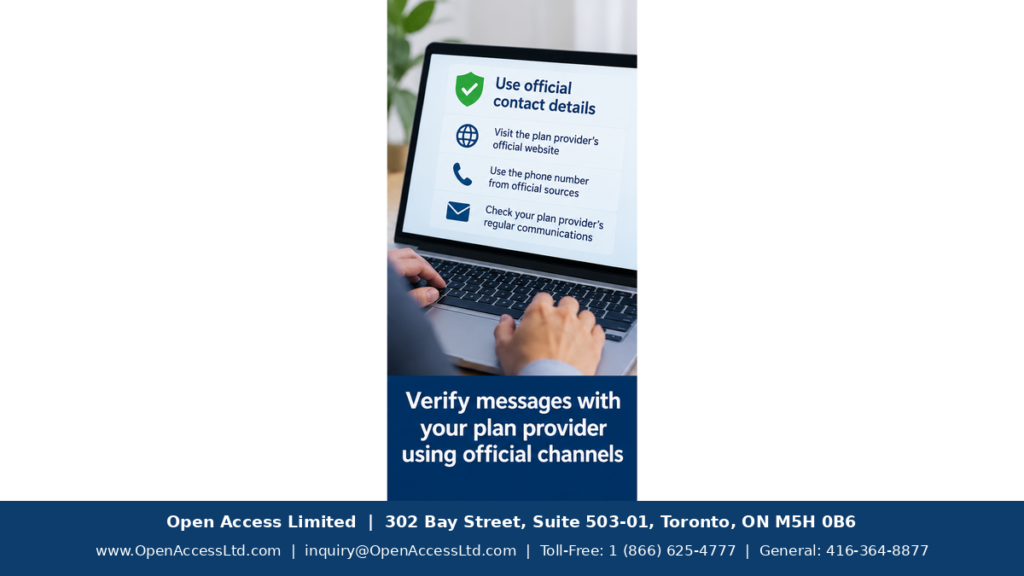
    Employers can make it easy for employees to find:

    • The provider’s official website
    • Official telephone numbers
    • Official email contact information
    • Member portal information
    • Plan documents and official forms

    This can help employees compare an unexpected message with the communication channels normally used by their provider.

    If an employee is unsure whether a message is legitimate, the safest approach is to contact the provider directly using official contact details.

    3. Protect Personal and Financial Information

    Fraud attempts may seek sensitive personal or financial information.

    Employees can be reminded not to provide information such as:

    • Social Insurance Numbers
    • Banking information
    • Passwords
    • Retirement account credentials
    • Other confidential account details

    through unverified links, emails, text messages, or other unexpected communications.

    Employers should also never ask employees to share passwords or account credentials as part of a fraud-awareness process.

    4. Encourage Direct Provider Verification

    If an employee receives an unexpected message about workplace retirement savings, the employee should be encouraged to verify it through the plan provider’s official contact channels.

    A useful general principle is:

    Do not reply to the suspicious message first. Verify the source independently.
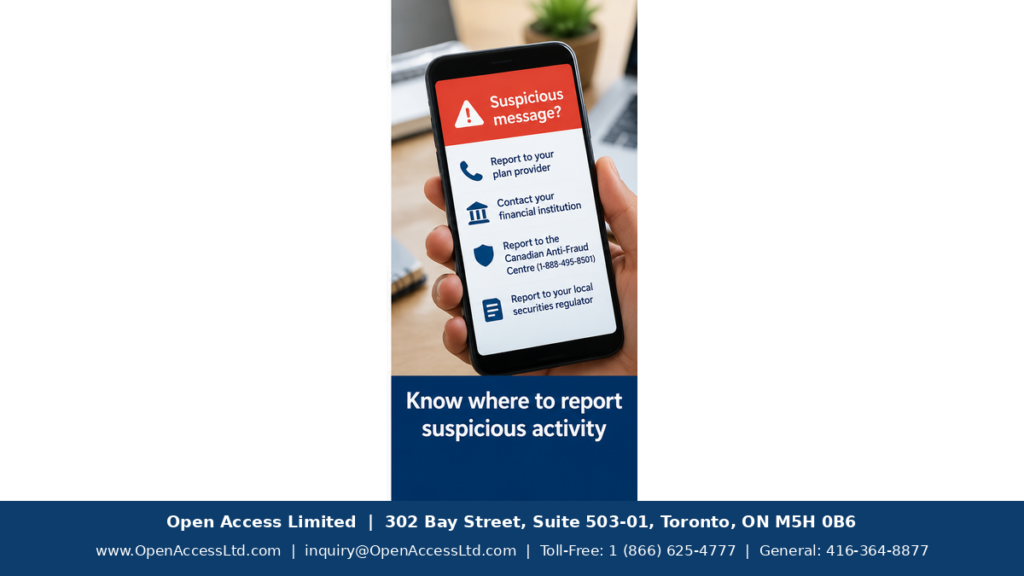
    Retirement savings scams verification pathway showing how employees can verify unexpected messages through official plan-provider contact channels.

    For example, an employee can use the telephone number, website, member portal, or contact information contained in official workplace plan materials.

    This may reduce the risk of responding directly to someone impersonating the provider.

    5. Use Plain-Language Fraud Education

    Fraud-awareness education is more useful when employees can understand and apply it quickly.

    Employers do not need highly technical cybersecurity language to communicate the basic message.

    Short reminders can be effective.

    For example:

    Before clicking a link, sharing personal information, or acting on an unexpected message about your retirement savings, verify the source using the contact details in the official plan materials. If you are unsure whether a message is from the plan provider, contact the provider directly.

    Any sample wording should be reviewed against current plan documents and the provider’s official communication materials before being used.

    6. Give Employees a Clear Reporting Pathway

    Employees should also know where they may report suspected fraud.

    Depending on the circumstances, this may include:

    • The workplace retirement-plan provider
    • The employee’s financial institution
    • The Canadian Anti-Fraud Centre
    • Local police
    • The applicable securities regulator

    The Canadian Anti-Fraud Centre accepts reports of fraud and cybercrime online and by telephone at 1-888-495-8501.

    Canadian securities regulators also provide resources for reporting suspected investment fraud.

    Providing employees with a clear reporting pathway may help them respond more quickly when something appears suspicious.

    7. Make Fraud Awareness an Ongoing Process

    Fraud methods change over time.

    For that reason, fraud-awareness education should not be limited to a single onboarding message.

    Employers may consider providing reminders:

    • During onboarding
    • During workplace retirement-plan education
    • When provider communication methods change
    • Periodically throughout employment

    CAPSA guidance for capital accumulation plans recognizes that member communication and education continue beyond initial enrolment.

    Regular reminders can help keep fraud-awareness information current and easier for employees to remember.

    What Employers Should Avoid

    Employers should be careful not to go beyond general fraud-awareness education.

    They should avoid:

    • Giving individual investment advice
    • Deciding whether a specific investment opportunity is legitimate
    • Promising that a message or investment is safe
    • Asking employees to provide passwords or account credentials
    • Using alarmist language that may discourage employees from participating in the retirement plan
    • Assuming that a particular employee or employee group is more likely to become a fraud victim

    Questions about whether a particular investment or seller is legitimate should be referred to the appropriate securities regulator or another qualified source.

    Can Employees Check Whether an Investment Professional Is Registered?

    Yes.

    The Canadian Securities Administrators state that securities professionals generally need to be registered with the securities regulator in each province or territory in which they conduct business.

    Employees who are considering an investment opportunity can be directed to official securities-regulator resources, including the National Registration Search, to check registration information.

    The employer should not perform an investment suitability assessment on the employee’s behalf.

    What Should an Employee Do After Receiving a Suspicious Retirement Savings Message?

    A simple process may help:

    Pause → Do Not Share Information → Verify Independently → Contact the Provider → Report Suspected Fraud

    Employees should avoid using contact information contained only within the suspicious message.

    Instead, they should use official plan materials or trusted government and regulator sources.

    Important Boundary for Canadian Employers

    This article focuses on general employee awareness regarding retirement savings scams and investment fraud.

    It does not address an employer’s own cybersecurity, privacy, or breach-reporting obligations involving payroll or retirement-plan data.

    Those responsibilities may require qualified legal, privacy, cybersecurity, or other professional advice.

    Employers should also confirm the security practices and official communication methods of their own retirement-plan provider directly with that provider.

    How Open Access Limited May Support Fraud-Awareness Communication

    Open Access Limited’s public materials include member resources, contact channels, member forms, a member portal, a trusted contact person form, and complaint-related information.

    Where a workplace retirement plan is provided through Open Access Limited, employers may direct employees to official Open Access Limited contact information when an employee needs to verify a message relating to the plan.

    Employers should confirm current provider practices directly with Open Access Limited rather than making assumptions about security controls.

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6, Canada

    Toll-Free: 1 (866) 625-4777
    General: 416-364-8877
    Fax: 416-955-4878
    Email: inquiry@OpenAccessLtd.com
    Website: www.OpenAccessLtd.com

    Frequently Asked Questions

    What Are Common Warning Signs of Retirement Savings Scams?

    Common warning signs may include pressure to act immediately, promises of unusually high returns with little or no risk, unregistered sellers, exclusive offers, repeated requests for more money, or demands for fees before funds can be released.

    Should Employees Click a Link in an Unexpected Retirement-Plan Message?

    Employees should first verify the source using the official contact information contained in their workplace retirement-plan materials or provider website.

    Can an Employer Tell an Employee Whether an Investment Offer Is Legitimate?

    Employers should generally avoid evaluating specific investment opportunities. Questions about the legitimacy or registration of an investment seller should be directed to the appropriate securities regulator or another qualified authority.

    What Personal Information Should Employees Avoid Sharing?

    Employees should be cautious about sharing Social Insurance Numbers, banking information, passwords, account credentials, or other confidential financial information through unverified communications.

    Where Can Employees Report Suspected Investment Fraud in Canada?

    Possible reporting channels include the Canadian Anti-Fraud Centre, local police, the relevant financial institution, the retirement-plan provider, and the applicable provincial or territorial securities regulator.

    Should Fraud Awareness Be Included Only During Employee Onboarding?

    No. Because fraud methods and provider communication practices can change, awareness information may be more useful when it is refreshed periodically.

    Can Employers Guarantee That Fraud Awareness Will Prevent Scams?

    No. Awareness education may reduce risk and help employees recognize warning signs, but it cannot guarantee that fraud will be prevented.

    Final Thoughts

    Helping employees recognize retirement savings scams does not require an employer to become an investment adviser or cybersecurity expert.

    A practical employer approach is to:

    Educate → Verify → Protect Information → Refer to Official Sources → Explain Reporting Options → Repeat the Message

    Clear communication can help employees recognize suspicious messages, protect personal information, verify communications through official channels, and understand where to seek help.

    The strongest approach is one that provides useful information while maintaining appropriate boundaries between workplace education and individual financial or investment advice.

    “A consistent fraud-awareness program can help employees identify retirement savings scams earlier and make safer decisions about their workplace retirement savings.

    References

    1. Canadian Securities Administrators (CSA) — Know the Red Flags of Fraud, updated June 18, 2025.
      https://www.securities-administrators.ca/investor-tools/avoiding-fraud/know-the-red-flags-of-fraud/
    2. Canadian Securities Administrators (CSA) — Are They Registered?, updated January 13, 2026.
      https://www.securities-administrators.ca/investor-tools/are-they-registered/
    3. Canadian Anti-Fraud Centre (CAFC) — Report fraud and cybercrime, modified November 27, 2025.
      https://antifraudcentre-centreantifraude.ca/report-signalez-eng.htm
    4. Canadian Association of Pension Supervisory Authorities (CAPSA) — Guideline No. 3: Guideline for Capital Accumulation Plans, September 9, 2024.
    5. Open Access Limited — Member Resources, Member Forms, Plan-Specific Enrolment Resources, and Contact Us.
  • How Can Canadian Businesses Handle Retirement Planning Conversations Without Creating Age-Discrimination or Pressure Concerns?

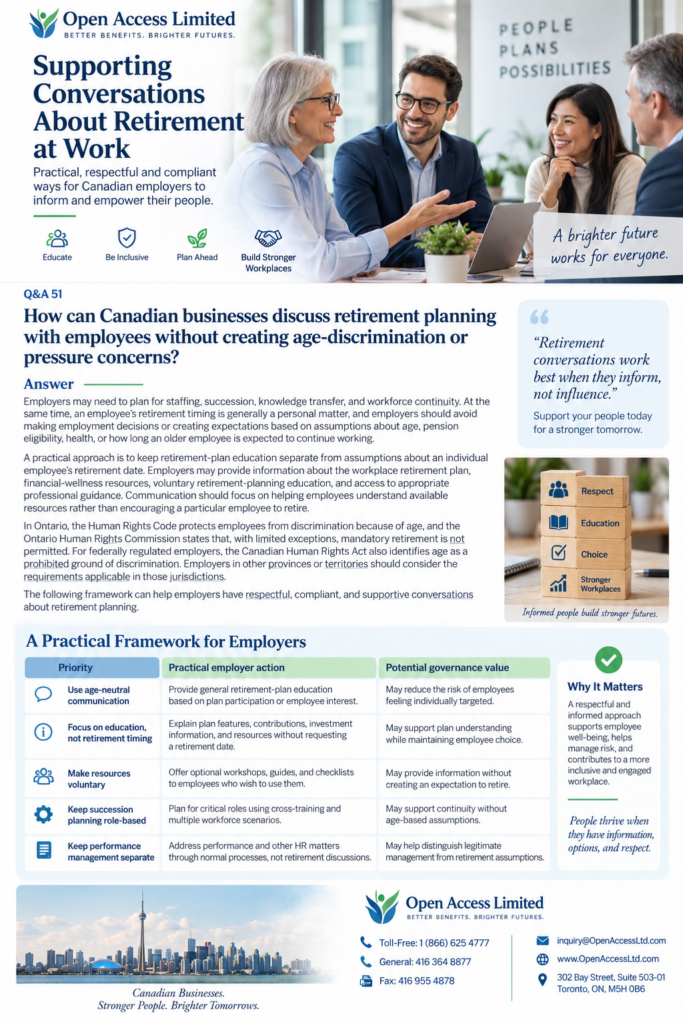
    How Can Canadian Businesses Handle Retirement Planning Conversations Without Creating Age-Discrimination or Pressure Concerns?

    Canadian businesses can approach retirement planning conversations by keeping communication age-neutral, making retirement education broadly available, offering additional resources voluntarily, and separating retirement education from individual employment decisions..

    In these situations, retirement planning conversations should remain voluntary and focused on the employee’s individual choices and available options.

    Employers should avoid making assumptions about an employee’s retirement timing based on age, pension eligibility, health, or how long the employee is expected to continue working.

    A practical approach is to focus on helping employees understand their workplace retirement plan and available resources rather than encouraging a particular employee to retire.

    Why Retirement Planning Conversations Require Care

    Clear retirement planning conversations can help employees better understand available resources while keeping individual retirement decisions personal

    Well-structured retirement planning conversations can help employers provide useful information while respecting employee choice and avoiding assumptions about individual retirement timing.

    Employers may need to plan for staffing, succession, knowledge transfer, and workforce continuity. At the same time, an employee’s retirement timing is generally a personal matter.

    Retirement-plan education should therefore be kept separate from assumptions about when a particular employee may leave the workforce.

    Canadian businesses can manage retirement planning conversations by using age-neutral communication, providing retirement education broadly, keeping additional resources voluntary, and separating retirement discussions from performance or employment decisions. Employers should avoid assumptions about retirement timing based on age, pension eligibility, health, or expected tenure, and refer sensitive individual matters to HR or qualified legal professionals.

    Employers may provide:

    • workplace retirement-plan information;
    • financial-wellness resources;
    • voluntary retirement-planning education; and
    • access to appropriate professional guidance.

    Communication should focus on helping employees understand available resources rather than suggesting that a particular employee should retire.

    In Ontario, the Human Rights Code protects employees from discrimination in employment because of age. The Ontario Human Rights Commission also states that, with limited exceptions, mandatory retirement is not permitted.

    For federally regulated employers, the Canadian Human Rights Act also identifies age as a prohibited ground of discrimination.

    Employers in other provinces and territories should consider the human-rights and employment requirements that apply in their jurisdiction.

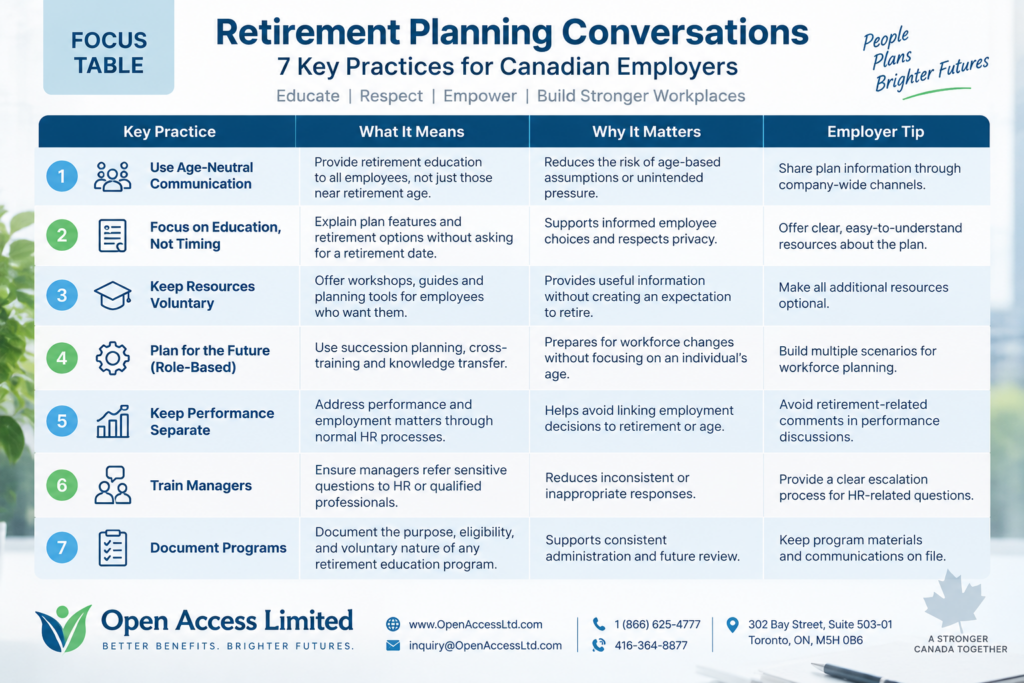
    7 Smart Retirement Planning Practices for Canadian Employers

    1. Use Age-Neutral Communication

    Retirement-plan education should be made available based on plan participation, employee interest, or broadly scheduled education.

    It should not be offered based on an assumption that employees of a certain age are preparing to leave the workforce.

    Age-neutral communication may help reduce the risk of employees feeling individually targeted because of age.

    2. Focus on Education, Not Retirement Timing

    Employers can explain:

    • plan features;
    • employee contributions;
    • employer contributions or matching, where applicable;
    • investment information;
    • retirement-income concepts;
    • fees;
    • available member tools; and
    • where employees may obtain qualified assistance.

    The purpose of retirement education should be to help employees understand their options, not to request that they commit to a retirement date.

    3. Make Additional Retirement Resources Voluntary

    Employers may offer optional:

    • workshops;
    • guides;
    • checklists;
    • retirement-readiness resources; and
    • access to qualified support.

    These resources should be available to employees who wish to use them.

    Keeping additional resources voluntary may provide useful information without creating an expectation that retirement is required.

    4. Keep Succession Planning Role-Based

    Succession planning is a legitimate business consideration, but employers do not necessarily need to know exactly when a particular employee plans to retire.

    Instead, businesses can prepare around roles and workforce scenarios through:

    • cross-training;
    • documentation of key processes;
    • leadership development;
    • knowledge-transfer procedures;
    • interim coverage;
    • planning for earlier-than-anticipated departures;
    • planning for longer-than-anticipated tenure; and
    • voluntary phased transitions where legally and operationally appropriate.

    This allows the organization to prepare for workforce changes without making assumptions about an individual employee based on age.

    5. Keep Performance Management Separate

    Performance, attendance, restructuring, role changes, and conduct should be addressed through the employer’s normal HR processes.

    They should not be reframed as retirement discussions.

    Employers should be cautious about statements such as:

    • “Have you thought about retiring?”
    • “Isn’t it time to slow down?”
    • “Wouldn’t retirement make sense now?”
    • “We need younger people for the next phase.”

    Statements of this nature may create age-discrimination concerns, particularly when connected to decisions about continued employment, promotion, training, assignments, or termination.

    6. Train Managers to Escalate Sensitive Questions

    Managers should have a clear process for referring retirement, pension, accommodation, and employment-law questions to HR or appropriately qualified professionals.

    Managers should generally avoid answering sensitive retirement or employment questions informally when those questions involve legal or employment issues.

    A clear escalation process may help reduce inconsistent or inappropriate responses.

    7. Document Formal Retirement Planning Programs

    If an employer provides a formal pre-retirement education or transition program, the business should document:

    • the purpose of the program;
    • eligibility criteria;
    • how the program is communicated; and
    • the voluntary nature of participation.

    Clear documentation may support consistent administration and future review.

    Retirement Planning Conversations: 7 key practices for Canadian employers

    What Retirement Planning Education Can Employers Provide?

    A business does not necessarily need to avoid retirement education because age discrimination is a concern.

    Effective retirement planning conversations can help employees better understand their workplace plan, available resources, and individual options.

    The more important distinction is between:

    • general or voluntary education available to employees; and
    • individual pressure or employment decisions based on age or presumed retirement intentions.

    Employers may provide ongoing education about:

    • plan contributions;
    • employer contributions or matching, where applicable;
    • investment options and risk profiles;
    • fees;
    • retirement-income concepts;
    • available member tools;
    • government retirement resources;
    • plan portability;
    • beneficiary information; and
    • where employees may obtain qualified assistance.

    Retirement education should also not be limited to onboarding.

    The Canadian Association of Pension Supervisory Authorities recommends that member education and communication for capital accumulation plans be considered on an ongoing basis rather than only at initial enrolment.

    Making information available periodically to a broader group of employees may also reduce the need for managers to initiate individualized retirement conversations based on perceived age.

    Regular retirement planning conversations can also help employees understand their workplace plan and available educational resources throughout their careers.

    Retirement planning  convesation without age discrimination for Canadian employers

    What Should Employers Avoid in Retirement Conversations?

    Retirement discussions can become sensitive when they begin to suggest that continued employment is connected to an employee’s age.

    Employers should be particularly cautious about:

    • repeatedly asking an employee when they intend to retire when they have not volunteered such plans;
    • assuming an employee wants fewer responsibilities because of age;
    • linking pension eligibility to an expectation that an employee should leave;
    • making assumptions about health, energy, adaptability, productivity, or career ambition based on age;
    • using retirement discussions as a substitute for performance management;
    • excluding older employees from training, promotion, development, or new assignments because retirement is assumed to be approaching;
    • targeting only older employees with communications that imply they are expected to leave; or
    • presenting an optional retirement arrangement in a way that could reasonably be perceived as coercive.

    These examples do not mean that every retirement-related conversation automatically constitutes discrimination.

    The context, jurisdiction, purpose, wording, frequency, and surrounding employment decisions may all matter.

    Employers should obtain qualified HR or legal advice where a conversation involves a particular employee’s employment status or potential retirement date.

    Employers should approach individual retirement planning conversations carefully when age, performance, pension eligibility, or continued employment may become part of the discussion.

    Can Employers Offer Voluntary Phased Retirement?

    Some employees may independently express an interest in gradually reducing their work commitments before retirement.

    Where an employer wishes to offer:

    • phased work;
    • reduced hours;
    • consulting arrangements;
    • mentoring roles; or
    • another transition option,

    participation should generally be voluntary and the arrangement should be reviewed carefully.

    Depending on the circumstances, the arrangement may involve:

    • employment law;
    • human rights;
    • pension and benefit eligibility;
    • payroll;
    • tax;
    • compensation;
    • accommodation obligations;
    • employment-status questions; and
    • plan rules.

    The existence of pension eligibility or a particular age should not automatically determine whether an employee is expected to participate.

    Why This Matters to Canadian Business Owners

    The objective is not to prevent retirement-planning conversations altogether.

    Clear retirement planning conversations can also support a more consistent approach to employee education across the workplace.

    A more appropriate process is one in which:

    • employees have access to retirement-plan education;
    • additional planning resources are voluntary;
    • managers know where to refer sensitive questions;
    • workforce planning is based on roles and scenarios rather than age assumptions;
    • employment decisions remain separate from retirement-plan education; and
    • individualized employment or legal issues are escalated appropriately.

    This type of process may help create clearer boundaries between retirement education and employment decision-making.

    It should not be presented as guaranteeing employee trust, preventing discrimination complaints, improving retention, or ensuring legally compliant outcomes in every situation.

    How Can Open Access Limited Support Retirement Planning Education?

    Open Access Limited may support employers with the retirement-plan education and member-support elements that can help inform retirement planning conversations.

    Structured retirement planning conversations can also help employers provide consistent plan education and access to appropriate member resources.

    Depending on the applicable plan, Open Access Limited may support employers through:

    • plan-specific employee education;
    • enrolment and plan materials;
    • explanations of plan features;
    • retirement-planning resources;
    • financial-wellness education;
    • member-support channels; and
    • communication relating to applicable group retirement-plan provisions.

    These resources may allow employers to provide retirement information through a structured plan-education process rather than relying on individual managers to explain retirement-plan details informally.

    Open Access Limited should not be positioned as determining whether an employer’s retirement conversation complies with human-rights or employment law, training managers on employment-law obligations, deciding when an employee should retire, or advising an employer on termination or performance management unless those services are specifically within the scope of an applicable engagement.

    Those matters should be addressed through the employer’s HR function and appropriately qualified legal professionals.

    Open Access Limited

    Website: www.OpenAccessLtd.com
    Email: inquiry@OpenAccessLtd.com
    Address: 302 Bay Street, Suite 503-01, Toronto, ON, M5H 0B6
    Toll-Free: 1 (866) 625-4777
    General: 416-364-8877
    Fax: 416-955-4878

    The Bottom Line

    Effective retirement planning conversations should focus on education, access to information, and employee choice rather than assumptions about when a particular employee should retire.

    Well-designed retirement planning conversations can support employee education while helping employers maintain clear boundaries between retirement information and employment decisions

    Canadian employers can create clearer boundaries by using age-neutral communication, making additional resources voluntary, keeping succession planning role-based, separating employment decisions from retirement education, and referring sensitive matters to appropriate HR or legal professionals.

    Effective retirement planning conversations can give employees clearer access to information while helping employers maintain appropriate boundaries around individual retirement decisions.

    Frequently Asked Questions

    Can an employer ask an employee when they plan to retire?

    Context matters. Repeatedly asking an employee about retirement when they have not volunteered such plans may create concerns, particularly where the conversation is connected to age or employment decisions.

    Should retirement education only be offered to older employees?

    Employers should generally use age-neutral communication and broadly available retirement education rather than targeting employees because they are assumed to be approaching retirement.

    Can Canadian employers offer phased retirement?

    Potentially. Participation should generally be voluntary, and the arrangement may require consideration of employment law, human rights, pension and benefit eligibility, payroll, tax, compensation, accommodation obligations, and plan rules.

    Can Open Access Limited support retirement planning education?

    Depending on the applicable plan, Open Access Limited may provide plan-specific employee education, retirement-planning resources, financial-wellness education, enrolment materials, plan information, and member-support channels.

    References

    1. Ontario Human Rights Commission. Age Discrimination. Guidance on protection from age discrimination in employment.
    2. Ontario Human Rights Commission. The End of Mandatory Retirement. Guidance explaining Ontario’s protection against age-based mandatory retirement, subject to limited exceptions.
    3. Government of Ontario. Human Rights Code, R.S.O. 1990, c. H.19. Current Ontario legislation governing equal treatment in employment, including discrimination based on age.
    4. Government of Canada, Justice Laws. Canadian Human Rights Act. Federal legislation identifying age as a prohibited ground of discrimination in areas under federal jurisdiction.
    5. Government of Canada. Rights in the Workplace. Overview of the Canadian Human Rights Act’s application to federally regulated employers.
    6. Canadian Association of Pension Supervisory Authorities (CAPSA) (2024). Guideline No. 3: Guideline for Capital Accumulation Plans. Guidance concerning plan communication, education, governance, and member responsibilities.
    7. Open Access Limited. Employee/Member Retirement Planning Resources. Current retirement-planning resources and member-support information.

    Editorial Note

    This Q&A is general educational content for employers and is not legal, human-rights, employment, pension, tax, payroll, HR, or regulatory advice.

    Retirement discussions and age-discrimination obligations are fact-specific and may differ by jurisdiction and employment context. Employers should obtain appropriately qualified employment-law, human-rights, HR, and retirement-plan advice before implementing policies, programs, or individual employment decisions involving retirement.

  • When Should Canadian Businesses Review Their Retirement Provider?

    When Should Canadian Businesses Review Their Retirement Provider?

    Short Answer:
    Canadian businesses should periodically review their retirement provider to ensure the plan still aligns with workforce needs, fees, services, investment options, technology, education, and governance expectations. A review does not automatically mean the provider needs to be changed.

    Why Should Employers Review Their Retirement Provider?

    Workplace retirement plans can remain in place for many years, while a business and its workforce continue to evolve.

    Employee demographics, technology, fees, investment options, available services, and organizational objectives can all change over time. For this reason, employers should generally view their retirement provider relationship as something that requires periodic review rather than a one-time decision.

    The Canadian Association of Pension Supervisory Authorities (CAPSA) recommends that sponsors of capital accumulation plans periodically review the performance of their service providers.

    Importantly, reviewing a retirement provider does not automatically mean that changing providers is necessary. A review may instead identify opportunities to improve communication, clarify responsibilities, review fees, update investment options, strengthen employee education, or improve governance processes.

    When Should You Review Your Retirement Provider?

    Several developments may indicate that it is time for a more detailed review.

    Your Business Has Changed

    Significant growth, restructuring, new locations, or changes in workforce demographics may mean that the existing retirement arrangement should be reassessed.

    Employees Have Recurring Questions

    Repeated employee questions about how the retirement plan works may indicate gaps in education, communication, or member support.

    Fees and Services Have Not Been Reviewed

    Employers may want to periodically assess whether fees remain reasonable and competitive in relation to the services, investment options, education, administration, and support being provided.

    Service Issues Keep Occurring

    Recurring administrative delays, reporting issues, unresolved service concerns, or inconsistent support may warrant closer examination.

    Technology Needs Have Changed

    Employers should consider whether portals, digital tools, communication channels, reporting capabilities, and accessibility features continue to meet the needs of the organization and its workforce.

    Canadian business retirement provider review

    How to Review Your Retirement Provider in Canada?

    A structured retirement provider review can consider several areas rather than focusing on a single issue.

    Plan Purpose and Responsibilities

    Does the current arrangement still reflect the documented purpose and objectives of the workplace retirement plan?

    Employers should also understand which responsibilities belong to the provider and which remain with the plan sponsor.

    Service Quality

    Consider responsiveness, reporting, issue resolution, employee support, and whether agreed services are being delivered consistently.

    Fees and Services

    Fees should generally be considered together with the services employees and employers receive.

    A lower fee alone does not necessarily establish that another provider would be more appropriate.

    Investment Options

    Investment options and default options should be periodically reviewed using appropriate criteria.

    CAPSA recommends periodically reviewing investment options and funds and states that this review should occur at least annually.

    Employee Education

    Employee education should extend beyond initial enrolment.

    Employers may consider whether employees continue to receive clear information about contributions, fees, investments, available tools, plan changes, and where to obtain assistance.

    Administration, Technology and Security

    Employers may also review recordkeeping, contribution processes, reporting, technology, privacy, cybersecurity, business continuity, and controls protecting member information.

    Should Fees Be the Main Reason to Change Retirement Providers?

    Not necessarily.

    Price is important, but a retirement provider should generally not be evaluated on fees alone.

    Employers may consider the overall arrangement, including:

    • total fees and expenses;
    • investment-management arrangements;
    • administration and recordkeeping;
    • employee education and support;
    • digital tools;
    • reporting;
    • governance support; and
    • additional or optional charges.

    This provides a broader picture of the value and services associated with the retirement plan.

    When Might Changing a Retirement Provider Make Sense?

    A provider change may be considered when a documented review identifies material gaps that cannot be satisfactorily resolved within the existing arrangement.

    Examples could include recurring unresolved service problems, unavailable required services, inadequate technology or administration, reporting or governance requirements that cannot be supported, or changes in plan objectives that the current arrangement cannot reasonably accommodate.

    However, these circumstances do not automatically require a provider change.

    Employers should consider their own plan circumstances and compare available alternatives using documented criteria.

    What Should Employers Avoid?

    Changing a retirement provider based on one isolated factor may not provide a complete picture.

    For example, a decision generally should not be based solely on one employee complaint, one service incident, one period of investment performance, one lower-fee proposal, a promotional claim, or a new technology feature.

    A more comprehensive review can help employers evaluate multiple factors before making a decision.

    What Should You Consider Before Changing Providers?

    Changing retirement providers may involve much more than signing a new agreement.

    Depending on the retirement arrangement, employers may need to consider existing contracts, termination provisions, plan documents, account or asset transfers, investment changes, payroll processes, employee records, privacy, cybersecurity, fees, communication, and applicable legal or regulatory requirements.

    Communicate Changes Clearly

    Employees should generally receive clear information about material changes affecting their retirement plan.

    Communication may need to explain:

    • what is changing and what is staying the same;
    • when the change takes effect;
    • whether investment options or fees will change;
    • whether employees need to take action;
    • how existing balances will be handled; and
    • where employees can obtain assistance.

    How Can Open Access Limited Support Employers?

    For Canadian employers considering their workplace retirement options, Open Access Limited provides customizable group retirement plans and plan-specific resources.

    Where an employer is considering Open Access Limited as a potential new provider, Open Access may support areas within its services, including:

    • discussing group retirement objectives;
    • developing an appropriate plan structure;
    • explaining available plan features and investment options;
    • providing applicable fee information;
    • establishing enrolment materials;
    • coordinating employee education and communication; and
    • supporting implementation of the Open Access arrangement.

    Employers remain responsible for evaluating existing obligations, comparing available alternatives, documenting their decisions, and obtaining appropriate professional advice where required.


Open Access Limited retirement plans supporting Canadian employees and stronger businesses

    The Bottom Line

    A retirement provider review does not necessarily mean it is time to switch providers.

    Instead, periodic review can help Canadian employers determine whether their workplace retirement arrangement continues to align with plan objectives, workforce needs, fees, services, technology, education, investment options, and governance expectations.

    A structured review can also help employers identify areas that may be improved within the existing arrangement before deciding whether a provider change should be considered.

    References

    1. Canadian Association of Pension Supervisory Authorities (CAPSA) (2024). Guideline No. 3: Guideline for Capital Accumulation Plans.
    2. Canadian Association of Pension Supervisory Authorities (CAPSA) (2024). Guideline No. 10: Guideline for Risk Management for Plan Administrators.
    3. Open Access Limited. Group Retirement Plans in Canada.
    4. Open Access Limited. Current Group Retirement Plan Enrolment and Member Resources.

  • What Is a Common Mistake Businesses Make When Implementing Retirement Plans for Employees?

    Why Retirement Plan Strategy Matters

    A common challenge businesses may face when implementing retirement plans is treating them as a standard employee benefit rather than as part of a broader workforce strategy.

    In today’s evolving labour market, employees increasingly value benefits that support long-term financial well-being. As a result, retirement plans are often viewed as an important component of overall compensation and employee experience.

    Common Mistakes Businesses Make With Retirement Plans
    Some organizations implement retirement programs with:

    • Limited customization
    • Minimal employer contributions
    • Generic plan structures
    • Limited alignment with workforce needs

    When retirement plans are not tailored to employee priorities, workers may perceive them as having limited relevance to their long-term financial goals.

    The Importance of Aligning Benefits With Workforce Needs

    Research suggests employee benefits tend to be more effective when they align with workforce priorities and are supported by a clearly defined value proposition.

    An effective retirement program is often designed with objectives such as:

    • Supporting employee financial wellness
    • Improving employee retention
    • Encouraging long-term workforce stability
    • Enhancing overall employee engagement

    Key Factors in Effective Retirement Plan Design

    Several factors may influence the effectiveness of a retirement program, including:

    • Contribution structures
    • Vesting schedules
    • Investment options
    • Workforce demographics
    • Employee financial priorities

    When these elements are thoughtfully aligned,retirement plans may better support both employee satisfaction and organizational objectives.

    Why Some Employers Work With Retirement Advisory Firms

    Because retirement outcomes can vary based on plan structure and implementation, some organizations choose to work with experienced retirement advisory firms to help design customized strategies aligned with business and workforce goals.

    For example, Open Access Limited works with employers across Ontario and Canada to help develop retirement program structures focused on employee financial well-being and long-term organizational alignment.

    Frequently Asked Questions

    What is a common mistake employers make with retirement plans?

    A common mistake is treating retirement plans as a generic employee benefit instead of aligning them with workforce needs and long-term business goals.

    Why should retirement plans be customized?

    Customized employee retirement plans may better support employee financial wellness, engagement, and retention by addressing workforce-specific priorities.

    What makes a retirement plan effective?

    Effective retirement plans often include thoughtful contribution structures, investment options, and alignment with employee financial goals.

    Can retirement benefits improve employee retention?

    Retirement benefits may contribute to retention efforts by supporting long-term financial security and improving overall employee satisfaction.

    Final Thoughts

    Retirement plans are often most effective when they are treated as part of a broader workforce and employee well-being strategy rather than as a generic benefit offering.

    Organizations that thoughtfully design retirement programs around workforce needs, financial wellness goals, and long-term business objectives may be better positioned to support employee engagement, attraction, and retention.

    Retirement Plans Mistakes for Employee Engagement and Workforce Strategy

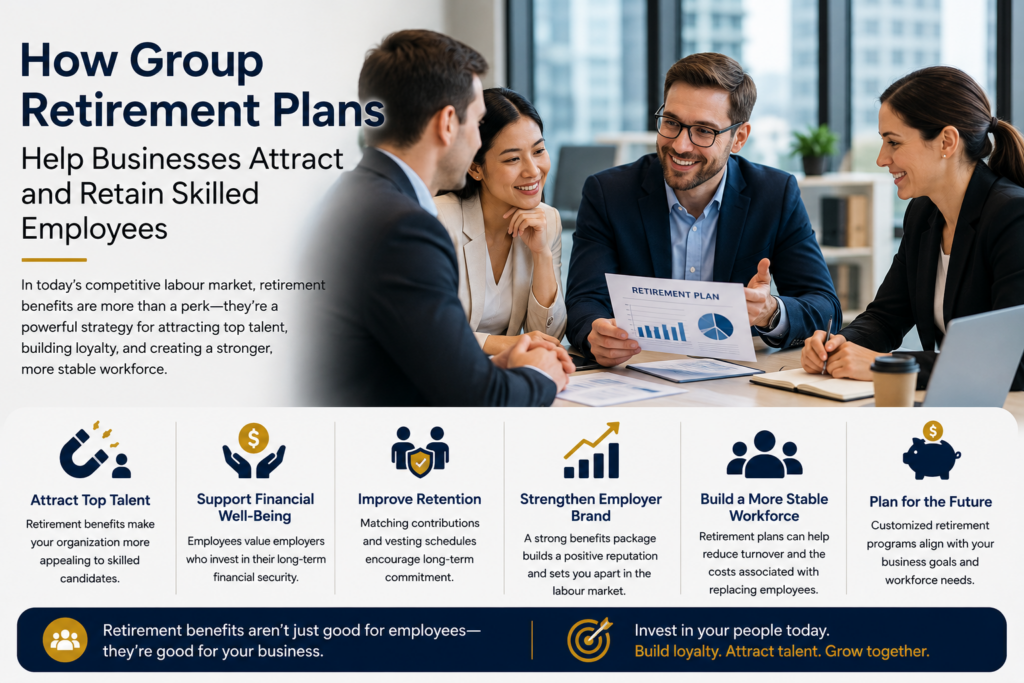
  • How Can Group Retirement Plans Help Businesses Attract and Retain Skilled Employees?

    In today’s competitive labour market, businesses are increasingly exploring ways to attract and retain skilled employees beyond offering competitive salaries. While compensation remains an important factor, research suggests that workplace benefits — particularly those related to long-term financial well-being — play a meaningful role in employee decision-making (SHRM, 2025; Gallup, 2024).

    How Retirement Plans Help Attract and Retain Employees

    Group retirement plans are one approach organizations may use to support both attraction and retention objectives.

    These programs allow employees to contribute regularly toward long-term savings, often with the addition of employer contributions. When employees perceive that their employer is supporting their future financial security, it can help strengthen trust and reinforce a sense of long-term commitment (Fidelity Investments, 2023).

    Effective retirement plans can improve employee engagement and support long-term workforce goals.

    From a retention perspective, certain plan features — such as employer matching contributions and vesting schedules — may encourage employees to remain with an organization longer in order to realize the full value of those benefits. Research in workplace benefits design indicates that these types of structures can contribute to workforce stability and help reduce turnover-related costs (Benefits Canada, 2025).

    Well-designed retirement plans help businesses build stronger employee benefit strategies.

    Group retirement programs may also support employer branding. Organizations that offer structured financial benefits are often viewed as more forward-looking and supportive of employee well-being, which can enhance their ability to compete for skilled talent in tight labour markets (SHRM, 2025).

    It is important to note that outcomes can vary depending on how a retirement program is designed. Factors such as contribution structure, vesting timelines, investment options, workforce demographics, and long-term cost sustainability all influence the effectiveness of these plans.

    Building Long-Term Value With Retirement Plans

    For this reason, many organizations choose to work with advisory firms experienced in designing customized group retirement strategies aligned with workforce needs and business objectives.

    For example, firms such as Open Access Limited, based in Ontario, work with employers to develop group retirement plans structures that aim to support employee financial well-being while aligning with long-term organizational goals.

    Business professionals discussing group retirement plans and employee retention strategies in a modern workplace, highlighting how retirement benefits can attract skilled employees, improve financial wellness, and support long-term workforce stability.

    References Society for Human Resource Management (SHRM) (2025).

    Employee Benefits Survey.
    https://www.shrm.org/topics-tools/research/employee-benefits-survey

    Society for Human Resource Management (SHRM) (2025).
    Employee Benefits Survey – Executive Summary.
    https://www.shrm.org

    Fidelity Investments (2023).
    Workplace Benefits and Retirement Trends Research.
    https://www.fidelityworkplace.com

    Benefits Canada (2025).
    Employers See Retirement Benefits as a Top Attraction and Retention Tool.
    https://www.benefitscanada.com

    Maytree Foundation.
    Retirement Plans and Workforce Attractiveness Research.
    https://maytree.com

    Gallup (2024).
    State of the Global Workplace Report.
    https://www.gallup.com

  • What Retirement Benefits Do Employees Value Most in Today’s Labour Market?

    In today’s labour market, employees are placing increasing importance on retirement benefits that support long-term financial security, flexibility, and meaningful employer participation.

    While competitive salaries remain an important component of total compensation, recent research indicates that workplace benefits — particularly those tied to long-term financial well-being — continue to play a significant role in how employees evaluate employers. For example, 81% of organizations report that retirement savings and planning benefits are “very” or “extremely” important as part of their overall benefits strategy (SHRM, 2025).

    Employees often view retirement benefits programs as an indicator of an employer’s commitment to supporting their long-term financial future.

    One of the most valued elements is employer contributions, such as matching programs or direct employer deposits into retirement savings plans. These contributions may help employees build retirement savings more effectively while reinforcing a sense of long-term partnership between the employer and its workforce (Fidelity Investments, 2022).

    Employees also tend to value access to tax-efficient retirement savings programs, including group plans that enable payroll deductions and streamlined investment access. These structures can support consistent saving behaviours and improve accessibility to long-term financial planning tools. Another important consideration is investment flexibility and access to guidance. Employees increasingly appreciate retirement programs that offer diversified investment options along with educational resources or advisory support, which may help improve confidence in financial decision-making (Deloitte, 2023).

    How Retirement Benefits Improve Employee Satisfaction

    Retirement benefits can help organizations create stronger workplace relationships by supporting employees’ long-term financial goals. Effective retirement benefits may improve employee confidence, loyalty, and overall satisfaction while helping businesses build a more stable workforce.

    In addition, retirement plans that include vesting structures tied to employer contributions can support retention by aligning long-term financial incentives with continued employment.

    Recent Canadian data also highlights the growing importance of financial well-being programs, with personal finances continuing to be a leading source of stress for employees. This has increased the relevance of employer-supported retirement and savings programs as part of a broader workforce strategy (Benefits Canada, 2025).

    It is important to note that employee preferences may vary based on factors such as age, income level, and financial literacy. As a result, the effectiveness of any retirement program often depends on how well it is designed to meet the needs of a specific workforce.

    For this reason, many organizations choose to work with advisory firms experienced in designing customized group retirement strategies aligned with workforce needs and business objectives. For example, firms such as Open Access Limited, based in Ontario, work with employers to develop retirement program structures that aim to support employee financial well-being while aligning with long-term organizational goals.

    Professional employees reviewing retirement benefits and financial planning options in a modern Canadian workplace discussing group retirement plans and employee financial wellness.

    References

    Society for Human Resource Management (SHRM) (2025).
    Employee Benefits Survey – Executive Summary.
    https://www.shrm.org

    Fidelity Investments (2022).
    Workplace Savings Research.
    https://www.fidelity.com

    Deloitte (2023).
    Global Human Capital Trends Report.
    https://www2.deloitte.com

    Benefits Canada (2025).
    Employee Benefits and Financial Wellness Insights.
    https://www.benefitscanada.com

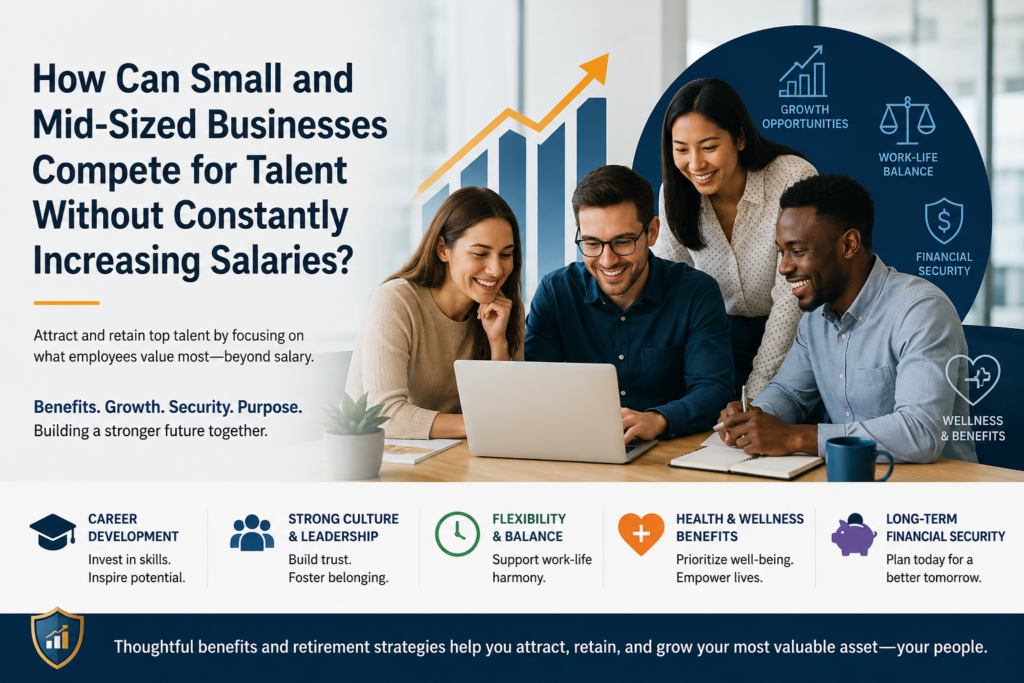
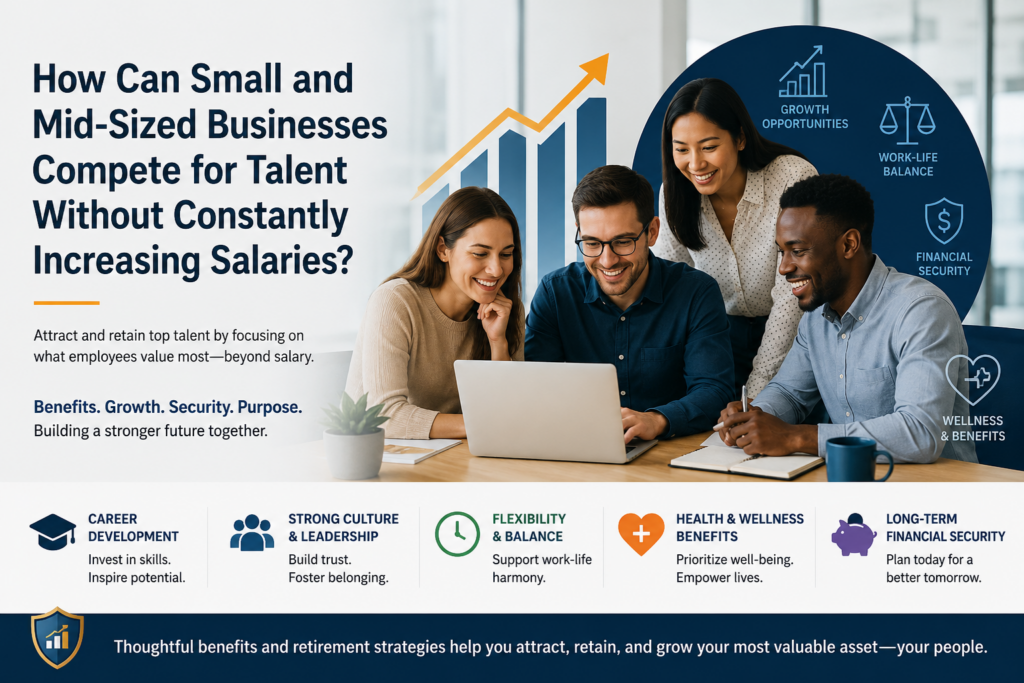
  • How Can Small and Mid-Sized Businesses Compete for Talent Without Constantly Increasing Salaries?

    Small business retirement plans can help companies attract and retain skilled employees while supporting long-term financial goals.

    For many small and mid-sized organizations, relying solely on salary increases to attract and retain employees may not always be financially sustainable. Market competition, rising operational costs, and long-term financial planning considerations can limit the extent to which organizations can continuously increase compensation.

    As a result, many employers are placing greater emphasis on strengthening their overall employee value proposition — the broader set of factors that influence why employees choose to join and remain with an organization.

    While competitive salaries remain an important component, research suggests that employees evaluate employers based on several additional factors, including:

    • Career development opportunities
    • Workplace culture and leadership
    • Work-life balance and flexibility
    • Health and wellness benefits
    • Long-term financial security

    Industry research indicates that benefits — particularly those tied to long-term financial well-being — are an increasingly important consideration in employee decision-making (SHRM, 2023; Gallup, 2023).

    Within this broader framework, structured retirement programs can play a meaningful role in supporting long-term employee engagement and retention.

    Employer-sponsored retirement plans, especially those that include employer contributions and vesting schedules, may help align employees’ long-term financial interests with the stability of the organization. When employees perceive that their employer is contributing to their future financial security, it can reinforce trust and support a sense of long-term partnership (Fidelity Investments, 2022).

    In competitive labour markets where salary ranges between employers may be relatively similar, structured benefits — including retirement programs — can also serve as a point of differentiation. Research in human capital trends suggests that organizations are increasingly using benefits as part of a broader strategy to attract and retain talent (Deloitte, 2023).

    It is important to note that the effectiveness of retirement programs can vary depending on plan design. Factors such as contribution structures, vesting schedules, investment options, workforce demographics, and long-term cost sustainability all influence outcomes.

    Small Business Retirement Plans for Employee Growth

    Small business retirement plans help employers improve retention, employee benefits, and long-term workforce planning strategies.

    For this reason, many organizations choose to work with advisory firms experienced in designing customized group retirement strategies aligned with workforce needs and business objectives.

    For example, firms such as Open Access Limited, based in Ontario, work with employers to develop retirement program structures that aim to support employee financial well-being while aligning with long-term organizational goals.

    Small business retirement plans can create stronger employee benefits while supporting long-term business growth and workforce stability.

    Ultimately, while compensation remains an important factor, organizations that combine competitive pay with thoughtful benefit design and long-term financial planning may be better positioned to compete for talent without relying solely on continuous salary increases.

    Small business retirement plans continue to play an important role in creating competitive workplaces.

    Small Business Retirement Plans for Employee Benefits

    References

    Society for Human Resource Management (2023).
    Employee Benefits Survey.
    https://www.shrm.org

    Fidelity Investments (2022).
    Workplace Savings Research.
    https://www.fidelity.com

    Gallup (2023).
    State of the Global Workplace Report.
    https://www.gallup.com

    Deloitte (2023).
    Global Human Capital Trends Report.
    https://www2.deloitte.com

    Open Access Limited.
    Group Retirement Strategy Advisory.
    https://www.openaccessltd.com