Category: Employee Financial Wellness

  • How Can Canadian Businesses Help Employees Understand How Workplace Retirement Contributions Affect Taxes, RRSP Room, and Year-End Planning?

    How Can Canadian Businesses Help Employees Understand How Workplace Retirement Contributions Affect Taxes, RRSP Room, and Year-End Planning?

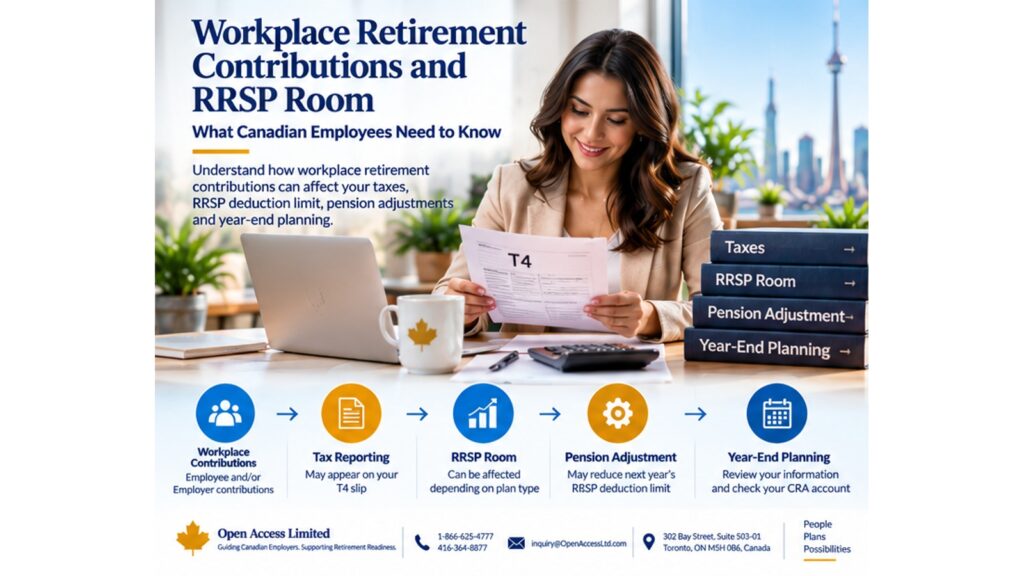
    Workplace retirement contributions can affect more than an employee’s retirement account balance. Depending on the type of plan and who makes the contribution, they may also affect tax reporting, RRSP deduction room, pension adjustments, payroll information, and year-end financial planning.

    This can become especially confusing during tax season, when employees begin reviewing T4 slips, contribution receipts, plan statements, and their CRA account.

    A Group RRSP, Deferred Profit Sharing Plan (DPSP), Registered Pension Plan (RPP), and Pooled Registered Pension Plan (PRPP) do not all receive the same tax treatment.

    For employers, the objective should be to explain the general rules of the workplace plan clearly, show employees where relevant information appears, and direct personal tax or investment questions to the Canada Revenue Agency or appropriately qualified professionals.

    The employer should not calculate an individual employee’s RRSP deduction limit or predict their personal tax result. OpenAccess_Q53_QA_with_Resource…

    Quick Answer: How Do Workplace Retirement Contributions Affect Taxes and RRSP Room?

    Canadian employers can help employees understand workplace retirement contributions by explaining the type of retirement plan, distinguishing employee and employer contributions, describing pension adjustments in general terms, showing where amounts may appear on pay statements and tax slips, and directing employees to CRA resources for their personal RRSP deduction limit.

    The tax effect depends on the plan type and the employee’s individual circumstances, so general workplace education should remain separate from personal tax advice.

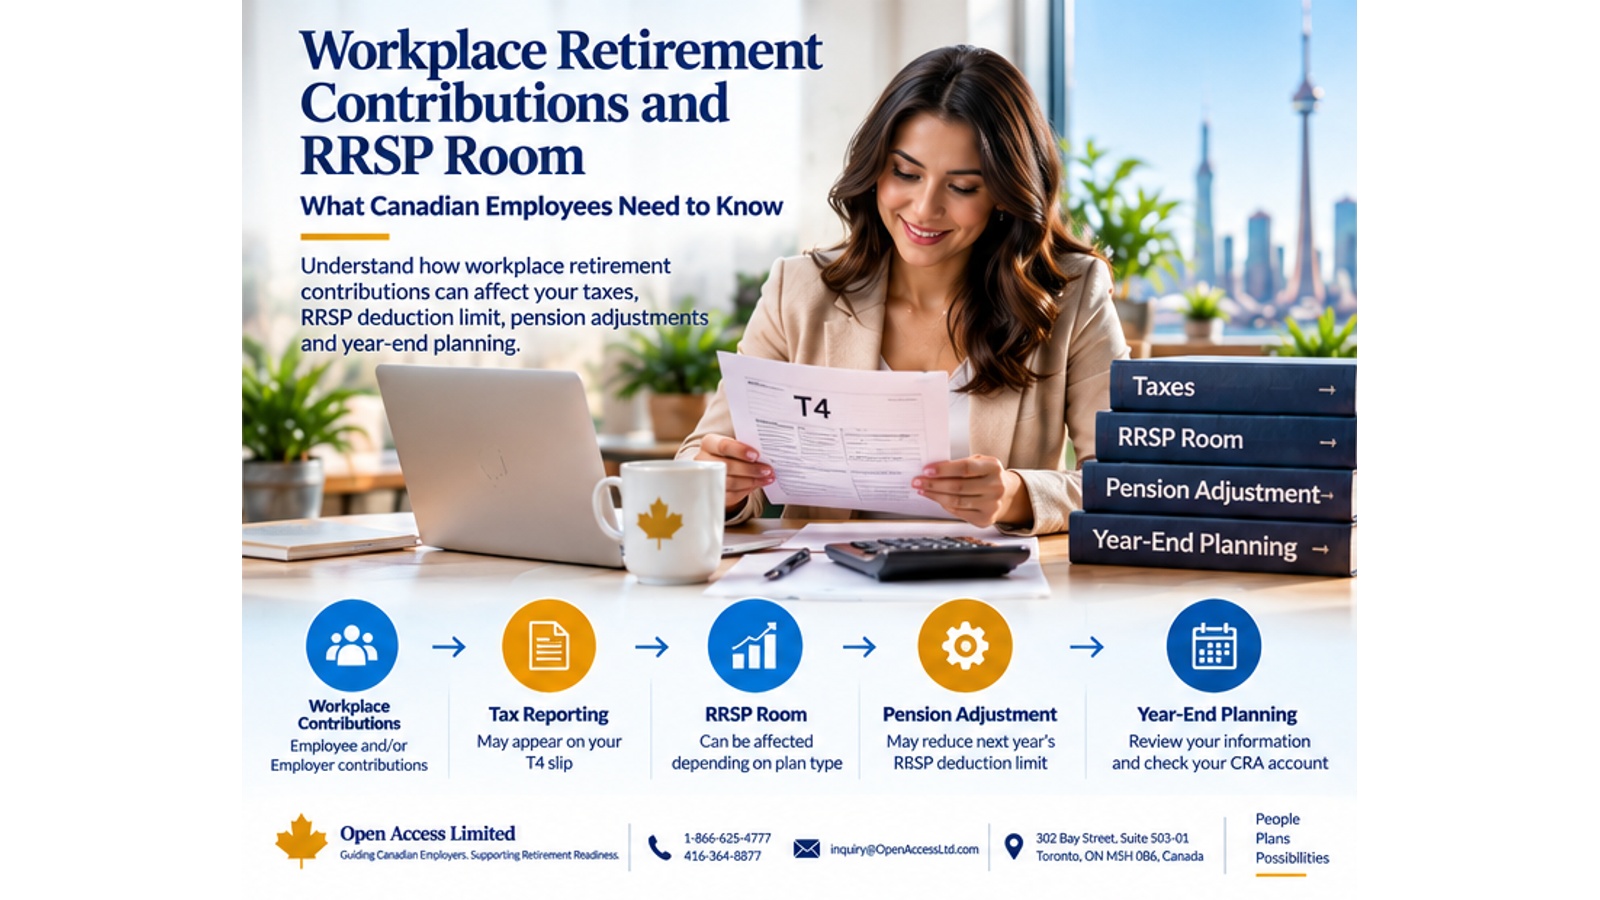
    Workplace retirement contributions explained for Canadian employees with taxes, RRSP deduction room, pension adjustments, tax slips, and year-end planning.

    On This Page

    1. Why Workplace Contributions Can Affect Tax Planning
    2. 7 Smart Employer Education Steps
    3. Group RRSP Tax Treatment
    4. DPSP and Pension Adjustments
    5. Registered Pension Plans
    6. PRPP Contributions
    7. How RRSP Room Is Determined
    8. Year-End and Tax-Season Planning
    9. What Employers Should Avoid
    10. Ongoing Employee Education
    11. How Open Access Limited May Support Employers
    12. FAQs
    13. Final Thoughts
    14. References

    Why Workplace Retirement Contributions Can Affect Tax Planning

    The phrase workplace retirement contributions can describe several different arrangements.

    An employee may participate in:

    • A Group RRSP
    • A DPSP
    • A Registered Pension Plan
    • A Defined Contribution pension plan
    • A PRPP

    The effect on income, deductions, RRSP room, and tax reporting can differ substantially.

    That is why employers should begin by answering one basic question:

    “Which retirement arrangement does this employee actually participate in?”

    Only after the plan type is clear should the employer explain its general tax and reporting features.

    7 Smart Ways to Explain Workplace Retirement Contributions

    1. Start by Explaining the Type of Retirement Plan

    Employees should first understand which retirement arrangement applies to them.

    For example:

    Group RRSP
    Employees may contribute through payroll and the employer may also contribute.

    DPSP
    Only the employer contributes.

    RPP or Defined Contribution Pension Plan
    Both employee and employer contribution rules may apply, depending on plan terms.

    PRPP
    Contribution and tax rules differ again.

    Explaining the plan type first can prevent employees from applying information about another type of retirement plan to their own situation.

    This is one of the most important foundations for explaining workplace retirement contributions accurately.

    2. Clearly Separate Employee Contributions From Employer Contributions

    Employees may see several contribution amounts without knowing who funded them or how they are reported.

    Employers should explain:

    • What the employee contributes
    • What the employer contributes
    • Whether employer matching applies
    • When contributions are made
    • Where contributions appear on pay statements
    • Where they appear on plan statements
    • Which tax documents may contain relevant information

    This is especially important where employer matching contributions form part of the plan.

    A simple communication model is:

    Employee Contribution → Employer Contribution → Plan Record → Tax Information

    The employer should explain the process without predicting the employee’s personal tax result.

    3. Explain RRSP Room in General Terms

    Employees often ask:

    “How much can I still put into my personal RRSP?”

    The employer should not calculate this amount.

    CRA calculates each individual’s RRSP deduction limit.

    In general terms, the calculation can involve unused deduction room carried forward plus a percentage of previous-year earned income up to the applicable annual limit, with adjustments that can include a Pension Adjustment.

    Employees can find their own RRSP deduction limit through their CRA Notice of Assessment or Reassessment or their CRA account. OpenAccess_Q53_QA_with_Resource…

    A useful employer message is:

    “Before making an additional personal RRSP contribution, check your current RRSP deduction limit directly with the CRA.”

    4. Explain the Pension Adjustment Without Making It Complicated

    The Pension Adjustment (PA) is one of the most confusing areas for employees.

    A clear general explanation is:

    A pension adjustment reflects the value of certain retirement benefits earned through an employer-sponsored pension arrangement during the year.

    Where applicable, it is generally reported in Box 52 of the T4 slip.

    It is not itself employment income and it is not an RRSP deduction.

    Instead, it can reduce the employee’s RRSP deduction limit for the following year.

    This is particularly relevant for DPSPs and Registered Pension Plans. OpenAccess_Q53_QA_with_Resource…

    Employees should still use CRA information to determine their actual available room.

    5. Show Employees Where to Find Their Information

    Employees should not have to guess which document contains which information.

    A year-end guide can show them where to look:

    Pay Statement
    Employee payroll deductions and applicable employer contributions.

    Retirement Plan Statement or Portal
    Contributions recorded in the workplace retirement account.

    T4 Slip
    Certain pension contributions, taxable benefits, and pension adjustments where applicable.

    CRA Notice of Assessment
    The employee’s personal RRSP deduction limit.

    This practical explanation makes workplace retirement contributions easier to understand than simply describing tax rules in abstract terms.

    6. Prepare Employees Before Year-End

    Tax questions often arise between year-end and the tax-filing period.

    Employees may be:

    • Reviewing their T4
    • Checking contribution receipts
    • Looking at plan statements
    • Reviewing their CRA account
    • Considering an additional personal RRSP contribution

    Employers can reduce confusion by providing general education before employees make additional personal contributions.

    The message should not say:

    “You should contribute another $X.”

    Instead:

    “Check your current CRA RRSP deduction limit before deciding whether to make an additional personal contribution.”

    This keeps education useful without becoming personal tax advice.

    7. Coordinate HR, Payroll, and the Plan Provider

    Employee confusion increases when HR, payroll, and the provider explain the same issue differently.

    Before year-end communication is released, employers should align:

    • Plan terminology
    • Contribution descriptions
    • Tax-slip explanations
    • Pension-adjustment language
    • RRSP-room guidance
    • Support contacts

    The source specifically recommends coordination between HR, payroll, and the provider to reduce inconsistent answers. OpenAccess_Q53_QA_with_Resource…

    For growing businesses, this also connects naturally with controls designed to reduce retirement plan payroll errors.

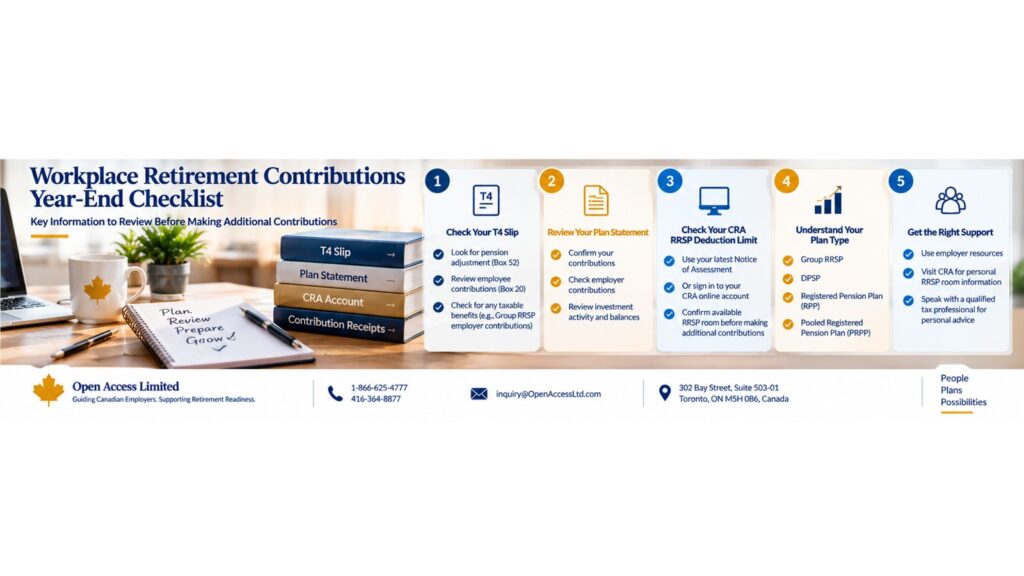
    Workplace retirement contributions year-end checklist showing T4 slips, pension adjustments, RRSP deduction limits, plan statements, CRA information, and employee support.

    How Group RRSP Contributions Affect Taxes and RRSP Room

    A Group RRSP is an employer-sponsored retirement savings arrangement.

    Employees commonly make contributions through payroll deductions, and an employer may also contribute.

    CRA guidance states that employer contributions to an employee’s RRSP are generally treated as a taxable benefit and reported on the employee’s T4.

    Contributions to the employee’s RRSP count against that individual’s RRSP deduction limit. OpenAccess_Q53_QA_with_Resource…

    This means employees should not assume that an employer contribution exists outside their personal RRSP-room considerations.

    They should review their actual CRA limit before making additional personal RRSP contributions.

    How DPSP Contributions Affect RRSP Room

    A Deferred Profit Sharing Plan works differently.

    Employees do not contribute to a DPSP.

    Only the employer contributes.

    Employer DPSP contributions generate a Pension Adjustment, which is reported on the employee’s T4 and generally reduces the employee’s RRSP deduction limit for the following year. OpenAccess_Q53_QA_with_Resource…

    This is a useful distinction for employees who participate in a Group RRSP plus DPSP arrangement.

    They may see contributions going into two retirement accounts, but the tax and RRSP-room treatment of those arrangements is not identical.

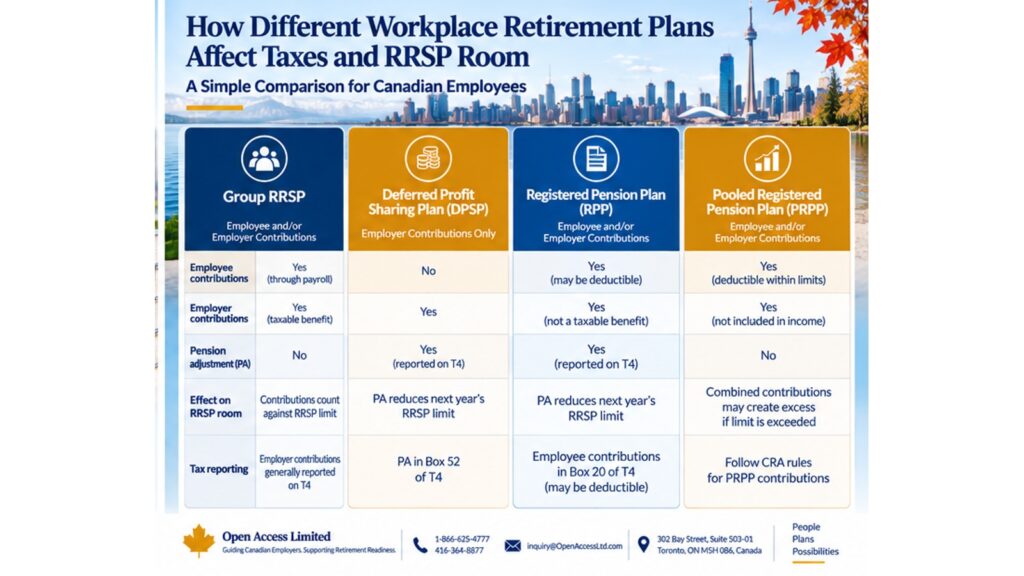
    Different workplace retirement plans can affect tax reporting, deductions, and RRSP room in different ways.

    How Registered Pension Plan Contributions Are Treated

    Registered Pension Plans, including defined contribution pension plans, follow another set of rules.

    According to the source:

    • Employer contributions to an RPP are generally not a taxable benefit to the employee.
    • Eligible employee RPP contributions reported in Box 20 of the T4 may be deductible on line 20700.
    • A Pension Adjustment may be reported and can reduce the following year’s RRSP deduction limit. OpenAccess_Q53_QA_with_Resource…

    This is why employees should not assume that the tax treatment of an RPP is identical to a Group RRSP.

    What About PRPP Contributions?

    A Pooled Registered Pension Plan follows different contribution and deduction rules again.

    The source notes that a member’s own PRPP contributions may be deductible within applicable limits.

    Employer PRPP contributions are not included in the member’s income and are not deductible by the member.

    However, employer PRPP contributions combined with the employee’s own PRPP and RRSP contributions may create an excess-contribution issue if the applicable RRSP deduction limit is exceeded. OpenAccess_Q53_QA_with_Resource…

    Employees should therefore confirm their personal limit before making additional registered contributions.

    Why RRSP Overcontributions Matter

    The source notes that CRA generally imposes a tax of 1% per month on RRSP contributions exceeding an individual’s deduction limit by more than the applicable $2,000 threshold. OpenAccess_Q53_QA_with_Resource…

    This is an important reason employers should avoid estimating an employee’s RRSP room.

    The safest general message is:

    “Confirm your personal RRSP deduction limit with the CRA before making additional personal contributions.”

    Why Year-End Communication Matters

    Year-end creates a natural opportunity to explain workplace retirement contributions.

    Employees are already reviewing:

    • Payroll records
    • Retirement statements
    • Contribution receipts
    • Tax slips
    • CRA information

    Employers can prepare a short year-end FAQ addressing common questions.

    For example:

    Where Can I Find My RRSP Deduction Limit?

    Use your latest CRA Notice of Assessment, Reassessment, or CRA account.

    What Is the Pension Adjustment on My T4?

    It generally reflects certain employer-sponsored retirement benefits earned during the year and can reduce next year’s RRSP deduction limit.

    Does My Employer Contribution Affect My Taxes?

    It depends on the type of retirement arrangement.

    Can I Still Contribute to My Personal RRSP?

    Possibly, but employees should confirm their available deduction room with the CRA first.

    Who Should I Ask About My Personal Tax Situation?

    CRA or an appropriately qualified tax or financial professional.

    What Employers Should Avoid

    Employers should avoid:

    • Telling an employee exactly how much to contribute
    • Calculating an employee’s RRSP deduction limit
    • Promising a tax refund
    • Predicting tax savings
    • Predicting an individual RRSP-room outcome
    • Assuming every employee has the same circumstances
    • Giving personal investment recommendations
    • Giving personal tax advice
    • Sending conflicting HR, payroll, and provider messages

    The source specifically identifies these as important boundaries. OpenAccess_Q53_QA_with_Resource…

    A workplace education program should explain how the plan works, not determine what a specific employee should do.

    Keep Workplace Education Separate From Personal Tax Advice

    This distinction is central to the entire article.

    Employers can explain:

    • Plan type
    • General contribution rules
    • Employer matching
    • Where contribution information appears
    • What a pension adjustment means generally
    • Where employees can find CRA information

    Employers should not determine:

    • The employee’s personal RRSP room
    • Whether the employee should make a contribution
    • The employee’s tax refund
    • The employee’s personal tax strategy
    • Which investment is best for that employee

    The employee’s individual circumstances may include income, unused RRSP room, other registered plans, previous contributions, and personal tax circumstances that the employer does not know.

    Ongoing Education Is Better Than a One-Time Tax-Season Message

    Tax questions recur every year.

    That means education about workplace retirement contributions should not happen only at onboarding or only once during tax season.

    CAPSA’s Guideline No. 3 emphasizes ongoing member communication and education rather than limiting education to initial enrolment. OpenAccess_Q53_QA_with_Resource…

    Employers can reinforce information:

    • Before year-end
    • When tax slips become available
    • During benefit education
    • When contribution formulas change
    • When employees change contribution elections
    • Through financial-wellness education

    This also supports broader retirement income education.

    How Can Employers Keep Tax-Time Communication Accurate?

    A strong process can include:

    • Current plan documents
    • Current CRA guidance
    • Plan-provider confirmation
    • Consistent HR and payroll explanations
    • Annual FAQ review
    • Updated contribution limits
    • Clear disclaimer language
    • Direct links to CRA resources
    • Qualified-professional referrals

    Dollar limits and CRA guidance can change from year to year.

    That means employee-facing materials should be reviewed before being reused.

    Important Implementation Boundaries

    This article describes general federal income-tax treatment.

    It does not determine individual tax outcomes.

    It does not address every provincial or territorial tax issue, locked-in arrangement, Group TFSA, or personal circumstance.

    The treatment of workplace retirement contributions depends on:

    • Plan type
    • Official plan documents
    • Payroll arrangements
    • Employee circumstances
    • Current CRA guidance

    Before sending tax-related communication or changing a payroll or contribution practice, employers should confirm the information with the plan provider and obtain qualified tax or payroll advice where appropriate. OpenAccess_Q53_QA_with_Resource…

    Need Help Make Workplace Retirement Contributions Easier to Understand?

    Open Access Limited may support employers with workplace retirement-plan education and year-end contribution communication.

    Open Access materials include group retirement-plan information, financial-wellness resources, RRSP and TFSA education, calculators, contribution forms, member portal access, statements and transaction information, and member support. OpenAccess_Q53_QA_with_Resource…

    Depending on the applicable plan, Open Access Limited may help employers and members understand:

    • The type of workplace retirement plan
    • Contribution provisions
    • Employer matching
    • Recorded contributions
    • Available plan statements
    • Member portal information
    • Financial-wellness resources
    • Available member support

    Employers should confirm with Open Access Limited which receipts, statements, or tax slips apply to their particular plan and when they are issued.

    Open Access Limited should not be positioned as providing personal tax advice or determining an individual employee’s RRSP deduction limit.

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6, Canada

    Toll-Free: 1 (866) 625 4777
    General: 416 364 8877
    Fax: 416 955 4878
    Email: inquiry@OpenAccessLtd.com
    Website: www.OpenAccessLtd.com

    Frequently Asked Questions

    Do Workplace Retirement Contributions Reduce Taxable Income?

    It depends on the plan type, who makes the contribution, and applicable tax rules. Employees should use current plan information and CRA resources.

    Do Employer Contributions Reduce My RRSP Room?

    They may affect RRSP room differently depending on the plan structure. For example, DPSP and RPP benefits can create a Pension Adjustment that reduces the following year’s RRSP deduction limit.

    Where Can Employees Find Their RRSP Deduction Limit?

    Employees can review their CRA Notice of Assessment or Reassessment or their CRA account.

    What Is a Pension Adjustment?

    A Pension Adjustment generally reflects the value of certain retirement benefits earned through an employer-sponsored pension or DPSP arrangement. It is not income or a deduction but may reduce next year’s RRSP deduction limit.

    Are Group RRSP and RPP Contributions Taxed the Same Way?

    No. Group RRSPs and Registered Pension Plans can have different tax, reporting, and RRSP-room treatment.

    Can an Employer Calculate an Employee’s RRSP Room?

    Employers should not calculate an individual employee’s RRSP deduction limit. Employees should confirm their current limit directly with the CRA.

    Should Employees Check RRSP Room Before Making an Extra Year-End Contribution?

    Yes. Employees considering additional personal contributions should review their own current CRA limit before making a decision.

    Final Thoughts

    Workplace retirement contributions can affect tax reporting and RRSP room in different ways depending on the retirement-plan structure.

    For Canadian employers, the strongest educational approach is:

    Explain the Plan Type → Separate Employee and Employer Contributions → Explain Pension Adjustments → Show Employees Where to Find Information → Prepare for Year-End → Coordinate HR, Payroll and Provider → Refer Personal Tax Questions Appropriately

    The objective is not to turn employers into tax advisers.

    It is to give employees clearer information about their workplace retirement plan so they know what to look for, what questions to ask, and where to obtain authoritative information before making personal year-end financial decisions.

    References

    1. Canada Revenue Agency — How Contributions Affect Your RRSP Deduction Limit.
    2. Canada Revenue Agency — Where Can You Find Your RRSP Deduction Limit.
    3. Financial Consumer Agency of Canada — Employer Pension Plans.
    4. Canada Revenue Agency — Contributions to Savings and Pension Plans.
    5. Canada Revenue Agency — Contributing to a Deferred Profit Sharing Plan.
    6. Canada Revenue Agency — Reporting a Pension Adjustment.
    7. Canada Revenue Agency — Line 20600 — Pension Adjustment.
    8. Canada Revenue Agency — Line 20700 — Registered Pension Plan (RPP) Deduction.
    9. Canada Revenue Agency — Contributions to a PRPP.
    10. Canadian Association of Pension Supervisory Authorities — Guideline No. 3: Guideline for Capital Accumulation Plans.
    11. Open Access Limited — Group Retirement Plans in Canada; Financial Wellness Resources; Member Forms; Member Resources.

  • How Can Canadian Businesses Support Retirement Readiness While Keeping Retirement Plan Eligibility and Worker Classification Clear?

    How Can Canadian Businesses Support Retirement Readiness While Keeping Retirement Plan Eligibility and Worker Classification Clear?

    Retirement plan eligibility can become more complicated when a Canadian business works with a mix of employees, independent contractors, freelancers, consultants, and other service providers.

    The challenge is not simply deciding who should receive retirement information.

    Businesses also need to distinguish between several separate questions:

    Is the individual legally an employee or genuinely self-employed?
    Does the official retirement plan allow that individual to participate?
    What payroll, CPP/QPP, EI, and tax treatment applies?
    What general retirement or financial-wellness education can appropriately be provided?

    These questions are related, but they are not interchangeable.

    A worker should not automatically be treated as an independent contractor simply because the agreement uses the word “contractor.” Likewise, retirement plan eligibility should not be used as a shortcut for determining employment status.

    The strongest employer approach is to review worker classification and benefit eligibility separately, communicate the distinction clearly, document decisions, and revisit them if the working relationship changes.

    Why Retirement Plan Eligibility and Worker Classification Must Be Reviewed Separately

    Worker classification in Canada depends on the actual facts of the working relationship.

    The Canada Revenue Agency considers the real terms and conditions of the relationship rather than relying solely on the label used by the parties.

    That means an employer should not assume that any single factor determines status, including:

    • The wording of a contract
    • A worker’s title
    • Method of payment
    • Access to a workplace benefit
    • Lack of access to a benefit
    • A statement that the person is “self-employed”

    Once worker status has been appropriately considered, retirement plan eligibility should then be reviewed according to the official plan documents, eligibility provisions, waiting periods, payroll arrangements, and applicable requirements.

    Keeping these processes separate helps businesses avoid creating the impression that benefit design itself determines legal worker status.


    What Retirement Support Can Employers Provide to Different Worker Groups?

    Retirement support does not necessarily need to look identical for every person connected with the business.

    Eligible employees may receive plan-specific support such as:

    • Enrolment information
    • Contribution education
    • Employer contribution information
    • Retirement-plan communication
    • Financial-wellness resources
    • Member-support channels

    Properly classified independent contractors may instead be directed, where appropriate, to general financial-wellness education or neutral public retirement-planning resources.

    The distinction matters.

    Providing general educational information is different from representing an independent contractor as a participant in an employer-sponsored retirement plan.

    A clear retirement plan eligibility process should therefore explain exactly what is available, to whom, and under which plan terms.


    8 Essential Safeguards for Retirement Plan Eligibility and Worker Classification

    1. Review the Actual Working Relationship First

    Before making benefit-eligibility decisions, businesses should understand whether the individual is actually an employee or genuinely self-employed.

    Relevant considerations may include the way work is controlled, how independently the person operates, the terms of the relationship, and other factors applicable to the particular classification analysis.

    The important principle is simple:

    Classification should follow the facts of the relationship—not merely the label attached to it.

    Where status for CPP and EI purposes remains uncertain, the CRA provides a ruling process.

    This review should generally occur before retirement plan eligibility is communicated to the individual.


    2. Confirm Retirement Plan Eligibility Separately

    Once classification has been appropriately reviewed, employers should examine the retirement plan itself.

    Review:

    • Official plan documents
    • Eligibility provisions
    • Waiting periods
    • Employee categories
    • Contribution structures
    • Payroll arrangements
      Provider requirements
      Applicable plan rules
      A worker being classified as an employee does not automatically answer every retirement-plan question.
      Likewise, describing someone as an independent contractor should not be used as a substitute for reviewing the actual relationship.
      A documented retirement plan eligibility process helps HR, payroll, and plan administrators communicate more consistently.

    3. Use Precise Language With Employees and Contractors

    Communication should make a clear distinction between:

    Employer-sponsored retirement benefits

    and

    General retirement or financial-wellness education.

    For example, eligible employees may receive plan-specific information about enrolment, contributions, fees, investment options, and member support.

    Independent contractors may be directed to neutral educational resources without suggesting that they are members of the employer’s retirement plan.

    Clear language helps reduce uncertainty about retirement plan eligibility and avoids creating unrealistic expectations.

    Employers should also ensure that HR, managers, payroll staff, and service providers use consistent terminology.


    4. Do Not Rely on the “Contractor” Label Alone

    A contractor agreement can be important documentation, but the label itself is not conclusive.

    Businesses should avoid assuming that:

    “Independent contractor” in the agreement automatically settles classification.

    The individual sends invoices, therefore they must be self-employed.

    The worker receives no employee benefits, therefore they must be a contractor.

    The worker receives a particular benefit, therefore they must be an employee.

    Classification can involve multiple factors.

    For this reason, employers should not attempt to manipulate retirement plan eligibility simply to support a preferred worker-classification outcome.

    Each issue should be reviewed under its own applicable requirements.


    5. Provide General Retirement Education Carefully

    Businesses may want to support financial wellness across a broader workforce.

    For eligible employees, that may include plan-specific retirement education.

    For independent contractors, businesses may consider directing people to general public information about:

    • Saving
    • Retirement planning
    • Registered accounts
    • Financial education
    • Retirement-income tools
    • General financial wellness

    However, general education should not be presented as individualized financial, investment, legal, or tax advice.

    The employer should also avoid suggesting that access to an educational resource creates retirement plan eligibility.

    Education and benefit participation are different things.


    6. Coordinate Payroll, CPP/QPP, EI, and Tax Treatment

    Worker classification can affect administrative processes beyond employee benefits.

    Businesses may need to confirm how status affects:

    • Payroll deductions
    • CPP or QPP
    • Employment Insurance
    • Tax reporting
    • Employer remittances
    • Benefit administration
    • Recordkeeping

    These areas should be coordinated with qualified payroll, tax, legal, and HR professionals where appropriate.

    A business should not create one classification for retirement plan eligibility, another for payroll, and another for employment practices without understanding whether those approaches are legally and administratively consistent.

    Coordination reduces the risk of conflicting internal practices.


    7. Document Classification and Eligibility Decisions

    Documentation can become particularly important when a workforce includes several different working arrangements.

    Employers should maintain appropriate records of:

    • Classification reviews
    • Retirement-plan eligibility decisions
    • Plan documents reviewed
    • Employee or contractor communication
    • Professional advice received
    • Payroll treatment
    • Significant changes in the working relationship
    • Review dates
    • Follow-up decisions

    Documentation supports consistency and future governance reviews.

    It also helps businesses explain why retirement plan eligibility was handled in a particular way if circumstances are reviewed later.


    8. Reassess When the Working Relationship Changes

    Classification should not necessarily be treated as permanent simply because an assessment was completed when a person first began working with the business.

    Relationships can change.

    For example:

    • Responsibilities may expand
    • Control may increase
    • Work schedules may change
    • The individual may become more integrated into the business
    • Payment arrangements may change
    • An independent project may become an ongoing working relationship

    When circumstances change materially, businesses should consider whether worker classification and retirement plan eligibility need to be reviewed again.

    This is particularly important for people who move from contract arrangements into permanent employment or whose working relationship gradually changes over time.


    Employee Retirement Support vs. Contractor Retirement Education

    One useful way to reduce confusion is to establish two clearly described communication pathways.

    H3: For Eligible Employees

    Retirement support may include:

    • Plan-specific enrolment materials
    • Contribution information
    • Employer contribution information
    • Fee information
    • Investment education
    • Financial-wellness resources
    • Member portals
    • Provider support
    • Ongoing retirement education

    Why Benefit Design Should Not Be Used to Determine Contractor Status

    A business might be tempted to reason:

    “If we do not give this person benefits, they remain a contractor.”

    That is not a reliable classification approach.

    Similarly:

    “If we offer a retirement contribution, that makes the individual an employee.”

    That conclusion should not be made based on one factor alone either.

    Worker classification depends on the broader working relationship and the applicable legal test.

    Therefore, benefit design should generally follow appropriate classification and plan review—not be used to manufacture the classification result.

    This distinction is one of the most important governan For Properly Classified Independent Contractors

    Where appropriate, businesses may provide or link to:

    • General retirement-planning education
    • Public financial-wellness resources
    • General savings information
    • Government retirement resources
    • Registered-account education
    • Retirement-income planning tools

    The contractor communication should not imply participation in the employer-sponsored plan unless retirement plan eligibility has actually been established under the relevant documents and professional review.

    A Special Note for Federally Regulated Employers

    Federally regulated employers should be particularly careful not to assume that a classification outcome for one legal purpose automatically determines status for every other purpose.

    Current federal misclassification guidance under Part III of the Canada Labour Code states that a person paid for work is presumed to be an employee unless demonstrated otherwise.

    The same guidance also distinguishes status under the Canada Labour Code from determinations under the Income Tax Act.

    Provincial and territorial rules may operate differently.

    This reinforces an important principle:

    Worker classification may need to be considered under more than one legal framework.

    Employers should therefore avoid treating one determination as automatically resolving every question about payroll, employment standards, tax treatment, or retirement plan eligibility.


    Common Worker-Classification and Benefit Mistakes to Avoid

    Businesses should watch for practical problems such as:

    • Using “contractor” as a label without reviewing the actual relationship
    • Promising retirement-plan participation before checking plan documents
    • Giving inconsistent answers from HR and payroll
    • Treating access to benefits as the only classification factor
    • Failing to update classification when duties change
    • Giving contractors employee-plan materials that imply eligibility
    • Providing individualized retirement advice through general education
    • Failing to document professional advice
    • Assuming a CRA determination automatically answers every employment-law question

    Clear processes help reduce these inconsistencies, although they cannot eliminate classification risk.


    How Retirement Readiness Can Still Support a Mixed Workforce

    The objective does not need to be providing identical retirement benefits to employees and contractors.

    A better objective is providing appropriate information while maintaining clear boundaries.

    Eligible employees may receive plan-specific education and support.

    Independent contractors may have access to neutral public resources.

    Both groups can receive useful information without blurring their legal or benefit status.

    A well-designed retirement plan eligibility process therefore supports clarity rather than sameness.

    This can complement a broader inclusive retirement benefits strategy for eligible employees while maintaining appropriate boundaries for non-employees.


    When Should an Employer Revisit Retirement Plan Eligibility?

    Employers may wish to review eligibility when:

    • An employee changes work status
    • A contractor becomes permanent
    • Job duties change materially
    • Payroll arrangements change
    • The retirement plan is amended
    • Eligibility rules change
    • The service-provider relationship changes
    • The working relationship becomes more integrated
    • The organization restructures

    A review should examine both the working relationship and the applicable plan terms.

    This approach helps keep retirement plan eligibility aligned with current circumstances rather than outdated assumptions.


    Why This Matters to Business Owners

    Self-employment, freelancing, consulting, gig work, and other contracted relationships are meaningful parts of the Canadian labour market.

    For business owners, the key question is not simply:

    “Do we offer retirement support?”

    The more useful questions are:

    Has the worker been appropriately classified?

    Is retirement plan eligibility consistent with the official plan?

    Are employee and contractor communications clearly distinguished?

    Are payroll, tax, employment, and benefit administration aligned with the working relationship?

    A structured process may reduce confusion, but businesses should not present it as eliminating classification risk.

    The facts and applicable legal requirements remain important.


    Important Implementation Boundaries

    Worker classification may involve:

    • Tax
    • Employment standards
    • Common-law or civil-law principles
    • Payroll
    • CPP/QPP
    • EI
    • Pension requirements
    • Employee benefits
    • Contractual arrangements

    No No single factor—including the wording of a contract, job title, payment method, or access to a benefit—should be relied upon by itself to determine employment status.

    Employers should obtain qualified legal, tax, payroll, HR, and retirement-plan advice before:

    • Changing worker classification
    • Extending retirement-plan eligibility
    • Removing retirement-plan eligibility
    • Offering employer-funded benefits to contractors
    • Changing payroll or tax treatment
    • Making legal statements to workers about their status

    Where CPP/EI classification remains uncertain, the CRA provides a formal ruling process.


    How Open Access Limited May Support Employers

    Open Access Limited may support employers on the retirement-plan side of the process for eligible members.

    Support may include:

    • Plan-specific enrolment materials
    • Contribution information
    • Plan booklets
    • Fee information
    • Employee retirement education
    • Financial-wellness resources
    • Member portal education
    • Member-support channels

    For organizations that work with both employees and contractors, these resources may help clarify which individuals are eligible for the group retirement plan and what support is available to eligible members under the applicable plan documents.

    Questions about whether an individual is legally an employee or independent contractor should be addressed with qualified legal, tax, payroll, or HR professionals.

    This division of responsibility can help keep retirement plan eligibility communication accurate without implying that retirement-plan administration determines legal worker classification.

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6
    Canada

    Toll-Free: 1-866-625-4777
    General: 416-364-8877
    Fax: 416-955-4878
    Email: inquiry@OpenAccessLtd.com
    Website: www.OpenAccessLtd.com

    Canadian business leaders reviewing employee versus independent contractor status, payroll treatment, retirement education, benefit eligibility, and documentation.

    Frequently Asked Questions About Retirement Plan Eligibility

    Does Calling Someone a Contractor Make Them Self-Employed?

    No. The classification analysis depends on the actual facts and terms of the working relationship, not only the title used in a contract.

    Can Independent Contractors Join an Employer Retirement Plan?

    Participation depends on the applicable plan documents, worker status, plan design, and relevant requirements. Employers should obtain appropriate professional advice before extending employee-style retirement benefits to contractors.

    Can Contractors Receive Retirement Education?

    Businesses may consider providing general financial-wellness education or directing contractors to neutral public retirement-planning resources without representing that information as participation in the employer-sponsored plan.

    Can a Benefit Determine Whether Someone Is an Employee?

    A single factor such as receiving—or not receiving—a benefit should not be relied upon by itself to determine employment status.

    What Happens if CPP or EI Status Is Uncertain?

    The CRA provides a CPP/EI ruling process where the worker or payer is uncertain about status for those purposes.

    Should Classification Be Reviewed Again Later?

    Yes. Material changes in duties, control, working arrangements, or the overall relationship may justify another classification and eligibility review.


    Final Thoughts

    Clear retirement plan eligibility starts with clear worker classification—but the two decisions should still be reviewed separately.

    For employees, employers can provide plan-specific enrolment information, contribution education, financial-wellness resources, and member support.

    For properly classified independent contractors, businesses may provide appropriate general retirement information without implying employee benefit eligibility.

    The strongest approach is:

    Classify carefully. Confirm eligibility separately. Communicate precisely. Coordinate administration. Document decisions. Review changes.

    That framework can support retirement readiness while maintaining clearer boundaries between employees, independent contractors, and employer-sponsored benefits.

    Retirement plan eligibility for Canadian employees and independent contractors with worker classification, plan review, payroll coordination, and retirement education.

    REFERENCES

    Open Access Limited — Group Retirement Plan Enrolment and Financial Wellness Resources

    Canada Revenue Agency — Employment Status: Employee or Self-Employed

    Canada Revenue Agency — Determine the Employment Status

    Employment and Social Development Canada — Misclassification, IPG-105

    Canadian Association of Pension Supervisory Authorities — Guideline No. 3: Guideline for Capital Accumulation Plans

    Financial Consumer Agency of Canada — Financial Wellness Resources for Employers and Employees

    Statistics Canada — Analysis of Businesses Outsourcing Work in Canada


  • How Can Businesses Design Retirement Benefits for Remote, Hybrid, and Multi-Location Employees?

    How Can Businesses Design Retirement Benefits for Remote, Hybrid, and Multi-Location Employees?

    Remote workforce retirement benefits require a clear and consistent strategy as more employees work outside a traditional central office.

    Some employees may work entirely remotely, while others follow hybrid schedules or move between different offices, cities, or provinces while remaining with the same organization. These arrangements can create practical challenges for employers that want their retirement program to remain understandable, fairly administered, and accessible to every eligible employee.

    The goal is generally not to create a separate retirement plan for each working arrangement. Instead, employers should develop one coordinated retirement-benefits strategy that can function clearly across a distributed workforce.

    A practical framework should address employee eligibility, payroll coordination, digital onboarding, communication, privacy, access, ongoing education, and retirement-plan governance.

    When these areas are managed consistently, businesses can support employee understanding while reducing avoidable pressure on HR and payroll teams.

    Why Do Remote Workforce Retirement Benefits Require a Clear Strategy

    Remote and hybrid work may make benefit communication more difficult.

    Employees who do not regularly attend a physical workplace may miss in-person meetings, informal HR reminders, printed notices, or office-based education sessions. Without an effective digital process, employees may not fully understand:

    • Whether they are eligible for the retirement plan
    • How contributions are deducted
    • What options are available
    • When enrolment deadlines apply
    • Where plan documents can be found
    • How to update personal information
    • Whom to contact for support

    Employees working in different locations may also be connected to different payroll, employment, tax, privacy, or administrative requirements.

    A well-designed remote workforce retirement benefits strategy creates a consistent employee experience while allowing the employer to address legitimate location-specific considerations.

    7 Proven Steps for Remote Workforce Retirement Benefits

    1. Define Eligibility Clearly and Consistently

    Employers should confirm which employees are eligible to participate in the retirement plan.

    The eligibility review should consider whether remote, hybrid, part-time, permanent, contract, or multi-location employees are treated consistently with the plan’s official terms.

    Employees should receive a clear explanation of:

    • When eligibility begins
    • Whether a waiting period applies
    • Which employment classifications qualify
    • How employer and employee contributions work
    • What happens when an employee changes work arrangements
    • Whether moving to another province affects administration

    Eligibility decisions should be based on documented plan terms rather than informal assumptions about where an employee works.

    Clear eligibility rules can reduce confusion, support consistent administration, and help HR teams respond to employee questions more efficiently.

    2. Coordinate Payroll and Employee Location Information

    Payroll coordination is an important part of managing remote workforce retirement benefits.

    When employees work from different locations, employers may need to review province-of-employment information, payroll deductions, contribution calculations, tax-related processes, and reporting responsibilities.

    The employer should establish a reliable process for updating employee location information whenever a remote or hybrid employee moves.

    A practical process may include:

    • Confirming the employee’s current work location
    • Updating payroll and HR records
    • Reviewing contribution deductions
    • Checking applicable province-of-employment information
    • Coordinating with payroll and retirement-plan providers
    • Documenting responsibility for location changes

    Accurate payroll and location records may help reduce contribution errors, inconsistent deductions, and administrative delays.

    Employers should obtain qualified payroll, tax, or legal advice where location changes create additional obligations.

    3. Provide Digital Retirement-Plan Onboarding

    Employees should be able to enrol in and understand the plan without attending an in-person meeting.

    A remote-friendly onboarding process may include:

    • Digital enrolment instructions
    • Electronic plan summaries
    • Recorded education sessions
    • Live virtual orientation meetings
    • Secure online forms
    • Employee portal access
    • Contact information for questions
    • Clear contribution examples
    • Digital beneficiary reminders

    Digital onboarding should be simple enough for employees to complete without unnecessary assistance, while still providing access to support when questions arise.

    Employers should also confirm that onboarding materials are accessible, updated, and consistent with information provided by the plan administrator.

    Effective digital onboarding can improve employee understanding and participation across multiple locations.

    4. Use Consistent Multi-Channel Communication

    A distributed workforce may require more than one communication channel.

    Employers can use email, employee portals, virtual meetings, recorded videos, newsletters, calendar reminders, and digital benefit guides to communicate retirement-plan information.

    However, using several channels should not create several different messages.

    Communication should remain consistent across:

    • HR announcements
    • Payroll notices
    • Provider materials
    • Employee portals
    • Virtual education sessions
    • Annual enrolment reminders
    • Plan-change communications

    Employees should receive the same explanation of eligibility, contributions, fees, deadlines, account access, and support regardless of where they work.

    Consistent communication strengthens remote workforce retirement benefits by helping employees remain informed even when they do not have regular contact with an office-based HR team.

    5. Protect Employee Privacy and Digital Access

    Remote retirement-plan administration may involve electronic records, employee portals, virtual meetings, online forms, provider platforms, and digital document delivery.

    Employers should confirm that sensitive employee information is handled securely.

    A privacy and access review may examine:

    • Who can access employee retirement data
    • Whether multi-factor authentication is available
    • How access is removed when responsibilities change
    • How documents are transmitted
    • Whether employee portals are secure
    • Which providers process employee information
    • How privacy concerns are reported
    • How cyber incidents are managed

    Employers should also remind remote employees not to share passwords, use unsecured networks for sensitive transactions, or send personal retirement documents through inappropriate channels.

    This work should connect with the organization’s broader retirement plan data security and privacy procedures.

    6. Offer Ongoing Virtual Education and Support

    Retirement education should not end after digital enrolment.

    Employees may need additional support as their careers, financial priorities, family responsibilities, or work locations change.

    Employers may provide:

    • Virtual retirement-education workshops
    • Scheduled online question sessions
    • Recorded learning resources
    • Digital FAQs
    • Contribution reminders
    • Annual plan reviews
    • Access to qualified professional guidance
    • Dedicated provider contact information

    Support should be accessible to employees in different locations and time zones wherever reasonably possible.

    Remote employees should not be placed at a disadvantage simply because they cannot attend an office meeting.

    Ongoing support can improve employee confidence and create a more consistent retirement-benefit experience across the organization.

    7. Review the Distributed Employee Journey

    Employers should periodically review how the retirement plan works for employees from enrolment through ongoing participation.

    A review may consider:

    • Eligibility questions
    • Enrolment completion
    • Payroll or contribution errors
    • Employee participation
    • Portal-access problems
    • Communication engagement
    • Support requests
    • Privacy concerns
    • Provider responsiveness
    • Differences between locations

    Recurring questions may reveal that a process or communication needs improvement.

    For example, repeated questions about eligibility may indicate that onboarding materials are unclear. Frequent portal-access problems may show that digital instructions or provider support require attention.

    Regular reviews help keep remote workforce retirement benefits aligned with workforce changes, technology, plan terms, and employee needs.

    How Can Employers Maintain Fairness Across Locations

    Fair treatment does not always mean that every administrative detail must be identical.

    Different employee locations may create legitimate payroll, tax, employment, privacy, or regulatory considerations. However, the overall employee experience should remain clear and consistently managed.

    Employers can support fairness by:

    • Using documented eligibility rules
    • Providing equal access to retirement education
    • Maintaining consistent plan communication
    • Reviewing location changes promptly
    • Coordinating HR, payroll, and provider responsibilities
    • Documenting any necessary administrative differences
    • Giving employees accessible support regardless of location

    The objective is to prevent remote or hybrid employees from receiving less information or support than office-based employees.

    Why Does a Distributed Retirement Strategy Matter to Business Owners

    A consistent retirement-benefits framework may reduce administrative pressure on HR and payroll teams.

    It can help business owners:

    • Explain plan rules more clearly
    • Reduce inconsistent employee treatment
    • Minimize payroll and contribution errors
    • Improve digital enrolment
    • Strengthen employee understanding
    • Support data security
    • Improve provider coordination
    • Maintain a consistent employee experience

    A well-organized process may also strengthen employee confidence in the organization’s retirement program.

    Employees are more likely to recognize the value of workplace retirement benefits when information and support remain accessible regardless of their location.

    mportant Implementation Boundaries

    Remote and multi-location work may create payroll, tax, employment-law, privacy, and retirement-plan administration considerations.

    The appropriate process may depend on:

    • The employee’s physical work location
    • Province of employment
    • Plan terms
    • Payroll structure
    • Employment classification
    • Organizational structure
    • Provider arrangements
    • Privacy requirements

    Employers should not assume that the same administrative approach automatically applies in every situation.

    Qualified payroll, legal, tax, privacy, employment, and retirement-plan professionals should review policies or communications when employees work across different jurisdictions.

    This article provides general educational information and does not replace professional advice.

    How Open Access Limited May Support Remote Workforce Retirement Benefits

    Open Access Limited may help employers create clearer retirement-benefit communication and administration processes for remote, hybrid, and multi-location teams.

    Support may include:

    • Digital enrolment communication
    • Employee retirement education
    • Provider coordination
    • Governance reviews
    • Plan communication
    • Administrative process reviews
    • Virtual employee support
    • Employee-focused retirement solutions

    These approaches may help employers maintain consistent communication, improve employee understanding, and align retirement-plan administration with a distributed workforce model

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6
    Canada

    Toll-Free: 1-866-625-4777
    General: 416-364-8877
    Fax: 416-955-4878
    Email: inquiry@OpenAccessLtd.com
    Website: www.OpenAccessLtd.com

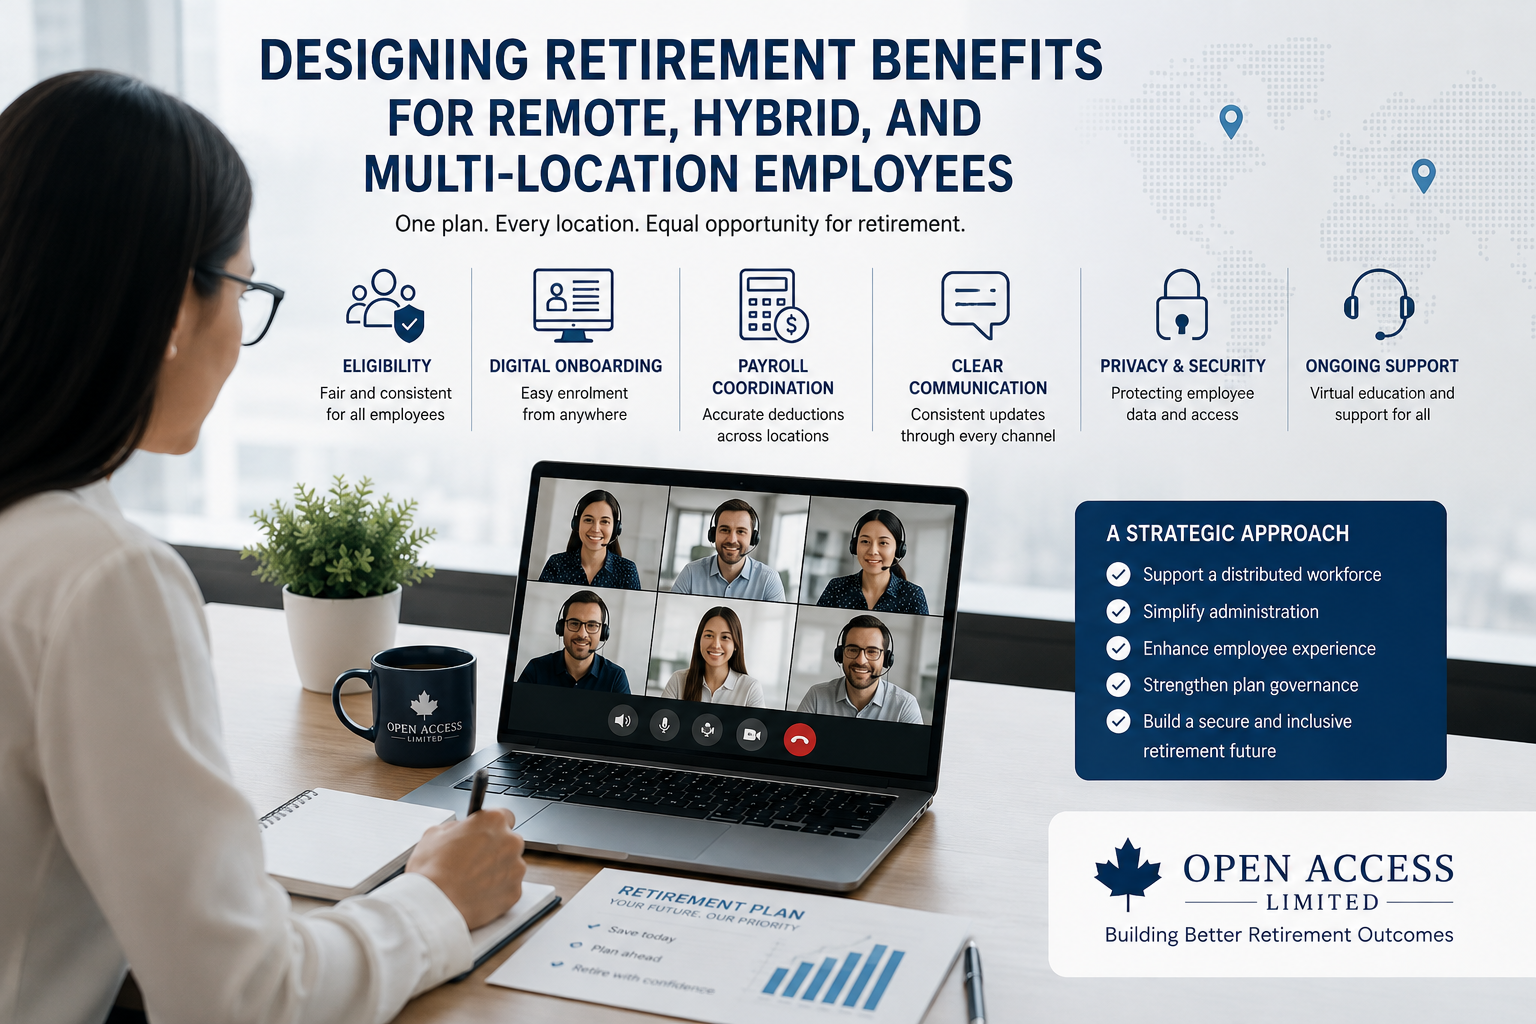
    Retirement benefits for remote, hybrid, and multi-location employees with consistent eligibility, digital access, payroll coordination, privacy protection, communication, and ongoing support.

    Final Thoughts

    A successful remote workforce retirement benefits strategy should make one retirement program work clearly across different work arrangements and locations.

    Employers can improve the employee experience by defining eligibility, coordinating payroll, providing digital onboarding, using consistent communication, protecting employee data, offering virtual education, and reviewing the employee journey regularly.

    The goal is not to create unnecessary complexity or separate plans for every type of employee.

    It is to build a clear, secure, and consistently administered retirement-benefits framework that supports employees wherever they work.

    Canadian HR leaders coordinating remote workforce retirement benefits, digital onboarding, payroll processes, secure employee access, virtual education, and multi-location retirement plan support.

    References

    Statistics Canada — Research to Insights: Working from Home in Canada

    Canada Revenue Agency — Determine the Province of Employment

    Canada Revenue Agency — RRSPs and Other Registered Plans for Retirement

    CAPSA — Guidelines for Industry

    CAPSA — Guideline No. 3: Guideline for Capital Accumulation Plans

  • How Can Businesses Support Employees Who Are Not Financially Ready to Retire Without Disrupting Workforce Planning?

    How Can Businesses Support Employees Who Are Not Financially Ready to Retire Without Disrupting Workforce Planning?

    Retirement readiness workforce planning is becoming increasingly important as more employees remain in the workforce because they do not yet feel financially prepared to retire.

    When retirement is delayed, the impact can extend beyond the individual employee. Employers may face uncertainty around succession planning, staffing, leadership development, knowledge transfer, career progression, and the timing of important workforce decisions.

    Retirement readiness workforce planning is most effective when it becomes part of an organization’s long-term talent strategy rather than a one-time retirement discussion.

    The most effective response is not to pressure employees toward a specific retirement date. Instead, businesses can create a respectful and voluntary framework that connects retirement education with succession planning, operational continuity, and flexible workforce transition options.

    A thoughtful approach gives employees better tools to make informed decisions while giving the organization enough flexibility to prepare for several possible outcomes.

    Why Does Retirement Readiness Affect Workforce Planning?

    Employees may delay retirement because they are uncertain about whether their savings, income, pension benefits, and other financial resources will support their future needs.

    By integrating retirement readiness workforce planning into employee education, succession planning, knowledge transfer, andworkforce development, businesses can improve operational continuity while helping employeesprepare for retirement with greater confidence.

    For employers, an uncertain retirement timeline can make it more difficult to plan hiring, promotions, leadership transitions, and workforce coverage. Critical roles may also contain institutional knowledge, client relationships, technical experience, or operational responsibilities that cannot be transferred quickly.

    However, employers should not assume that an employee’s age determines retirement readiness or intent.

    Effective retirement readiness workforce planning focuses on preparation rather than prediction. Businesses can create systems that support employees while protecting organizational continuity, even when the exact retirement date is unknown.

    5 Ways to Improve Employee Retirement Readiness and Workforce Planning

    Businesses can improve employee retirement readiness by providing early retirement education, offering flexible and voluntary retirement options, connecting retirement planning with succession and knowledge transfer, and using workforce planning to prepare for different retirement scenarios. A strong workplace retirement readiness program can help employees make more informed decisions while supporting business continuity.

    1. Provide Retirement-Readiness Education Early

    Retirement education should be available before a financial concern becomes a workforce-planning crisis.

    Employees may postpone retirement decisions because they do not fully understand plan features, contribution levels, retirement income options, or the questions they should discuss with a qualified financial professional.

    Employers can provide clear information about workplace retirement plans, available educational resources, contribution structures, and long-term planning considerations.

    Education should be offered consistently throughout an employee’s career rather than only when retirement appears close.

    The process must remain confidential and voluntary. The employer’s role is to provide reliable information and access to professional guidance—not to make assumptions about an employee’s finances or preferred retirement date.

    2. Consider Voluntary Phased-Retirement Options

    Phased retirement allows an employee to move gradually from full-time work toward retirement.

    Depending on operational needs and applicable rules, options may include reduced hours, project-based responsibilities, mentoring, consulting, temporary assignments, or another flexible arrangement.

    For employees, a phased transition may provide additional time to prepare financially while adjusting gradually to retirement.

    For employers, it can create more time to train successors, transfer client relationships, document processes, redistribute responsibilities, and preserve institutional knowledge.

    A phased approach should always be voluntary, clearly documented, and reviewed by appropriate legal, tax, benefits, and plan-administration professionals before implementation.

    3. Connect Retirement Planning With Succession and Knowledge Transfer

    Retirement planning and succession planning should not be treated as completely separate conversations.

    Organizations can identify positions that carry critical knowledge and develop continuity plans without requiring employees to disclose a specific retirement date.

    A structured knowledge-transfer plan may include:

    Cross-training team members
    Documenting essential procedures
    Creating mentoring relationships
    Developing future leaders
    Sharing client or project ownership
    Establishing interim coverage plans

    These actions protect the organization whether an employee retires earlier than expected, remains longer, or transitions gradually.

    Connecting retirement readiness with succession planning helps businesses reduce disruption while creating development opportunities for other employees.

    4. Build Workforce Scenarios Instead of Making Assumptions

    Employers should avoid assuming that age determines whether an employee is ready or intends to retire.

    A stronger approach is to create several workforce scenarios for critical positions.

    These may include:

    An earlier-than-expected departure
    An employee remaining longer than anticipated
    A gradual phased-retirement transition
    A temporary consulting or mentoring arrangement
    An unexpected leave or change in availability

    Scenario-based planning helps management prepare hiring timelines, leadership-development plans, interim coverage, and knowledge-transfer priorities without intruding into personal financial decisions.

    This approach also gives the organization greater flexibility when workforce circumstances change.

    5. Any retirement-transition initiative should protect employee dignity, privacy, and individual choice.

    Participation in retirement education, professional financial guidance, reduced-work arrangements, mentoring programs, or phased retirement should remain voluntary.

    Clear policies can help businesses explain eligibility, responsibilities, compensation arrangements, benefit implications, and transition expectations.

    Employers must also avoid age-based pressure or assumptions.

    Pension, employment, tax, human-rights, and benefits rules may affect how a formal retirement-transition program is structured. Businesses should obtain appropriate professional advice before introducing phased-retirement arrangements or changing employment conditions.Keep Every Transition Voluntary, Respectful, and Compliant

    A Practical Retirement Readiness Workforce Planning Framework

    Businesses can organize their approach around five connected objectives.

    Improve Employee Retirement Readiness

    Offer ongoing education and access to qualified professional guidance so employees can make more informed and confident decisions.

    Protect Business Continuity

    Create role-based succession, staffing, and coverage plans to reduce operational disruption.

    Retain Critical Expertise

    Use voluntary mentoring, phased work, project assignments, or consulting roles to create more time for knowledge transfer.

    Avoid Age-Based Assumptions

    Prepare for multiple retirement-timing scenarios rather than predicting decisions based on age.

    Measure and Improve the Process

    Review participation, communication effectiveness, succession progress, and transition outcomes to identify opportunities for improvement.

    How Can Businesses Balance Employee Support With Operational Stability?

    Delayed retirement does not have to become a workforce-planning crisis.

    The goal is not to control when employees retire. It is to create better conditions for informed employee decisions and more flexible organizational planning.

    Businesses can balance both priorities by combining retirement education, confidential support, voluntary transition options, succession planning, leadership development, and knowledge transfer.

    Retirement readiness workforce planning should also be integrated with broader workforce initiatives such as skills development, employee financial wellness, flexible work, and long-term talent planning.

    An integrated strategy can help employees feel respected while allowing the organization to prepare responsibly for different outcomes.

    How Open Access Limited Supports Retirement Readiness and Workforce Planning

    Open Access Limited is a Canadian independent provider of group retirement plans.

    The company supports employers with retirement plan design, member education, fiduciary oversight, employee-focused retirement solutions, and long-term plan strategy.

    Open Access Limited can help organizations strengthen retirement-plan education and member support while connecting employee retirement readiness with broader workforce priorities.

    These services may help businesses improve employee understanding, support participation, prepare for workforce transitions, and build a more resilient organization.

    Open Access Limited
    1 Richmond Street West, Suite 701
    Toronto, ON M5H 3W4
    Canada

    Toll-Free: 1-866-625-4777
    Email: inquiry@openaccessltd.com
    Website: https://openaccessltd.com

    Retirement readiness workforce planning is most effective when it becomes part of an organization’s long-term talent strategy rather than a one-time retirement discussion. By integrating retirement readiness workforce planning into employee education, succession planning, knowledge transfer, and workforce development, businesses can improve operational continuity while helping employees prepare for retirement with greater confidence. A proactive retirement readiness workforce planning strategy benefits both employees and employers by supporting informed decisions and long-term organizational resilience.

    Final Thoughts

    Retirement readiness workforce planning helps businesses support employees without forcing personal retirement decisions or weakening organizational continuity.

    By offering early education, considering voluntary phased-retirement options, connecting retirement planning with succession, preparing multiple workforce scenarios, and protecting employee privacy, organizations can manage change more effectively.

    The strongest approach respects individual choice while preparing the business for earlier departures, extended employment, and gradual transitions.

    When employee retirement readiness and workforce continuity are considered together, businesses can protect critical knowledge, develop future leaders, and create a more prepared and resilient workforce.

    Retirement readiness workforce planning meeting with Canadian HR leaders discussing phased retirement, succession planning, and workforce continuity.

    References

    Statistics Canada — Retirement and Post-Retirement Employment Among Older Canadians
    https://www150.statcan.gc.ca/n1/pub/75-006-x/2026002/article/00004-eng.htmStatistics Canada — A Record Number of Canadian Seniors Worked in 2025
    https://www.statcan.gc.ca/o1/en/plus/9132-record-number-canadian-seniors-worked-2025-here-are-some-reasons-whyAARP — Phased Retirement at Work: 5 Things to Think About
    https://www.aarp.org/work/careers/phased-retirement/Center for Retirement Research at Boston College — Phased Retirement: Problems and Prospects
    https://crr.bc.edu/wp-content/uploads/2007/02/wob_8.pdfOpen Access Limited — Group Retirement Plan in Canada
    https://openaccessltd.com/group-retirement-plan/Open Access Limited — Contact Us
    https://openaccessltd.com/contact-us/

  • How Can Businesses Improve Employee Understanding and Engagement with Their Retirement Benefits?

    How Can Businesses Improve Employee Understanding and Engagement with Their Retirement Benefits?

    Employee retirement benefits engagement has become one of the most important priorities for organizations that want to maximize the value of their workplace retirement programs. While many employers invest significantly in retirement plans, employees do not always understand how these benefits support their long-term financial wellbeing.

    Without clear communication and ongoing education, retirement programs may be underutilized, participation rates may remain lower than expected, and employees may miss valuable opportunities to prepare for retirement. Businesses that actively invest in education, communication, and employee support often create stronger engagement while helping employees make more informed financial decisions.

    Rather than viewing retirement plans as a one-time employee benefit, organizations are increasingly treating them as an ongoing financial wellness initiative that evolves throughout an employee’s career.

    Why Is Employee Retirement Benefits Engagement Important?

    Offering employees retirement benefits engagement is only the first step.

    Employees receive the greatest value when they understand how retirement programs work, why participation matters, and how their contributions support long-term financial security.

    A lack of understanding can reduce employee confidence and participation while limiting the overall effectiveness of the retirement plan.

    Organizations that focus on communication and financial education often create greater trust, improve employee confidence, and encourage long-term participation in workplace retirement programs.

    Retirement education also helps employees connect today’s financial decisions with tomorrow’s retirement goals.

    5 Smart Ways to Improve Employee Retirement Benefits Engagement

    1. Communicate Retirement Benefits Clearly

    Retirement plans often contain terminology that employees may not fully understand.

    Organizations should communicate plan features using simple language that explains contribution options, employer matching opportunities, investment choices, and long-term retirement objectives.

    Clear communication helps employees understand both the immediate and future value of participating in the plan.

    2. Provide Ongoing Financial Education

    Financial education should continue throughout an employee’s career instead of ending after onboarding.

    Educational workshops, webinars, newsletters, retirement planning sessions, and digital learning resources help employees build financial confidence while improving retirement readiness.

    Continuous learning encourages greater engagement because employees receive information when it becomes relevant to their current financial situation.

    3. Personalize Employee Guidance

    Employees have different financial priorities depending on age, income level, career stage, and family responsibilities.

    Providing personalized education and communication allows employees to better understand retirement options that fit their own circumstances rather than receiving the same information as everyone else.

    This individualized approach can improve understanding while increasing confidence in retirement planning decisions.

    4. Encourage Regular Retirement Conversations

    Many employees think about retirement only occasionally.

    Organizations can improve engagement by encouraging regular discussions during benefit reviews, annual enrollment periods, financial wellness events, and employee education programs.

    Frequent communication keeps retirement planning relevant and helps employees adjust their financial strategies as personal circumstances change.

    5. Make Retirement Resources Easy to Access

    Employees are more likely to engage when retirement information is easy to find and simple to understand.

    Businesses can provide online portals, educational videos, retirement calculators, FAQs, and digital planning tools that employees can access whenever needed.

    Accessible resources encourage ongoing learning while helping employees make informed financial decisions throughout their careers.

    Building Long-Term Employee Financial Confidence

    Improving employee retirement benefits engagement is not simply about increasing participation rates.

    It is about helping employees develop greater confidence in their financial future.

    Organizations that combine education, communication, and personalized support create stronger workplace relationships while demonstrating their long-term commitment to employee wellbeing.

    Retirement programs supported by continuous communication often become an important part of a broader employee financial wellness strategy that benefits both employees and employers.

    How Open Access Limited Helps Improve Employee Retirement Benefits Engagement

    Many organizations choose to work with experienced retirement specialists to strengthen employee understanding and long-term engagement with workplace retirement programs.

    Open Access Limited is an independent Canadian group retirement plan provider Employee Retirement Benefits Engagement that works closely with employers to develop retirement solutions focused on education, communication, and employee success.

    Rather than simply implementing retirement plans, Open Access Limited supports organizations by helping employees understand the value of their workplace benefits through ongoing financial education, structured onboarding, personalized communication, and continuous engagement initiatives.

    These services may help organizations improve employee participation, increase financial confidence, and strengthen retirement readiness while supporting long-term workforce wellbeing.

    Open Access Limited

    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6
    Canada

    Phone: (416) 364-8877

    Email: inquiry@openaccessltd.com

    Website: https://openaccessltd.com

    Final Thoughts

    Employee retirement benefits engagement is an ongoing process rather than a one-time event.

    Organizations that invest in clear communication, continuous financial education, personalized employee support, and accessible retirement resources often create stronger engagement with workplace retirement programs.

    When employees understand how retirement benefits contribute to their long-term financial wellbeing, they are more likely to appreciate the value of their benefits, participate confidently, and remain engaged throughout their careers.

    An effective employee retirement benefits engagement strategy can strengthen workplace trust, improve financial confidence, and help businesses maximize the long-term value of their retirement programs.

    Canadian HR professionals discussing employee retirement benefits engagement, retirement education, financial wellness, workplace communication, and long-term retirement planning in a modern corporate office.

    References

    Financial Literacy and Education Commission – Workplace Financial Education Research

    https://financialliteracy.gov

    National Endowment for Financial Education (NEFE)

    https://www.nefe.org

    Canadian Foundation for Economic Education (CFEE)

    https://cfee.org

    LIMRA – Retirement Education Research

    https://www.limra.com

    Transamerica Institute – Retirement Studies

    https://www.transamericainstitute.org

    Fidelity – Workplace Financial Wellness Research

    https://www.fidelity.com

  • How Can Businesses Create a Retirement Benefits Strategy That Adapts to Changing Employee Needs Over Time?

    How Can Businesses Create a Retirement Benefits Strategy That Adapts to Changing Employee Needs Over Time?

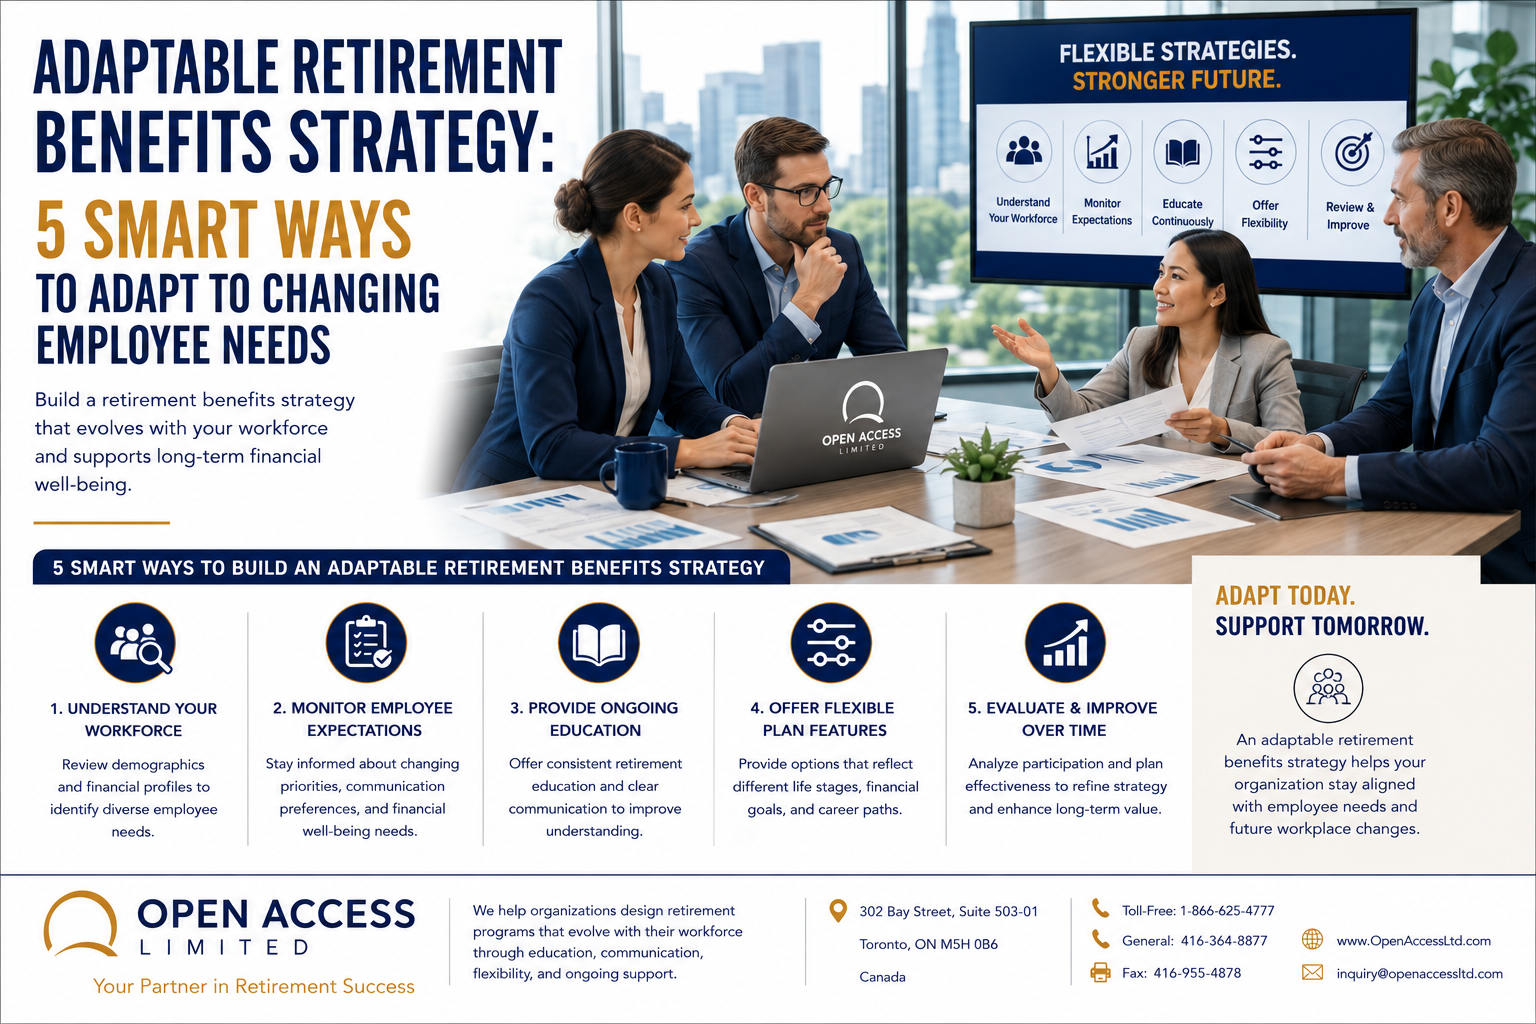
    How Can Businesses Build an Adaptable Retirement Benefits Strategy?

    A retirement benefits strategy should not remain fixed while employee needs, workforce demographics, financial priorities, and economic conditions continue to change.

    Employees at different career stages may have very different expectations. Early-career employees may focus on financial education, flexibility, and building savings habits. Mid-career employees may be balancing family responsibilities, housing costs, and long-term financial goals. Employees approaching retirement may place greater importance on retirement readiness, income planning, and financial security.

    For this reason, businesses may benefit from reviewing their retirement programs regularly rather than relying on a one-size-fits-all approach. An adaptable strategy can help organizations maintain alignment between plan design, employee expectations, and long-term workforce objectives.

    Why Do Employee Retirement Needs Change Over Time?

    Employee financial priorities often change as personal circumstances, career stages, and external economic conditions evolve.

    Changes in income, family responsibilities, financial literacy, inflation, housing costs, and retirement timelines may all influence how employees view workplace retirement benefits. A benefit that feels relevant to one employee group may not provide the same value to another.

    Workforce composition may also change as organizations hire new employees, experience generational shifts, or introduce new roles and working arrangements. These developments can affect participation patterns, communication preferences, and expectations around flexibility.

    A strong retirement benefits strategy recognizes these differences and creates a framework that can be reviewed and refined over time.

    5 Smart Ways to Create an Adaptable Retirement Benefits Strategy

    1. Review Employee Demographics and Financial Profiles

    Businesses can begin by understanding the people their retirement program is designed to support.

    Reviewing workforce demographics, career stages, financial profiles, and participation patterns may help employers identify different employee needs. For example, younger employees may require foundational education about retirement savings, while experienced employees may benefit from more detailed retirement readiness guidance.

    This information can help organizations make retirement programs more relevant without assuming that every employee has the same financial priorities.

    2. Monitor Changing Employee Expectations

    Employee expectations around benefits, communication, flexibility, and financial wellness can change over time.

    Organizations may use employee surveys, benefits feedback, participation data, and workforce discussions to understand how employees perceive the current program.

    Monitoring expectations does not mean changing the plan after every individual request. Instead, it allows businesses to identify broader trends and determine whether communication, education, or plan features may need adjustment.

    Regular feedback can help keep a retirement benefits strategy connected to real workforce needs.

    3. Provide Ongoing Retirement Education and Communication

    Retirement education should not be limited to onboarding or annual enrollment periods.

    Employees may need different information as their careers and financial circumstances develop. Ongoing education can help employees understand contribution options, long-term planning considerations, and the value of available workplace benefits.

    Communication should also be clear, accessible, and appropriate for different levels of financial literacy.

    Businesses may use workshops, digital resources, educational materials, individual guidance, and regular updates to support employee understanding. Consistent communication can make retirement planning feel more practical and easier to engage with.

    4. Offer Flexible Plan Features Where Appropriate

    Flexible plan features may help organizations support employees with different financial priorities and career stages.

    Depending on the plan structure, flexibility may include contribution options, educational resources, digital access, or planning support that reflects different employee circumstances.

    Flexibility does not require unlimited choice. The objective is to create a plan that can respond reasonably to workforce changes while remaining aligned with organizational goals, governance requirements, and available resources.

    An adaptable retirement benefits strategy should balance employee choice with clear structure and long-term plan sustainability.

    5. Evaluate Participation and Plan Effectiveness Over Time

    Participation data can provide useful insight into how employees interact with retirement benefits.

    Organizations may review enrollment levels, contribution patterns, employee feedback, communication engagement, and use of educational resources.

    Low participation does not always mean the plan design is ineffective. It may indicate that employees need clearer communication, more relevant education, or better access to support.

    Regular evaluation allows employers to identify areas where plan design, communication, or education may require refinement. Outcomes can vary depending on workforce characteristics, plan structure, and implementation approach, so reviews should be measured and based on appropriate context.

    How Can Businesses Keep Retirement Benefits Stratege Aligned With Workforce Needs?

    Businesses can keep retirement benefits relevant by treating plan review as an ongoing process rather than a one-time project.

    A practical review may consider whether the program still reflects workforce demographics, employee financial priorities, organizational objectives, participation trends, and external economic conditions.

    Retirement planning should also be considered alongside other employee experience initiatives, including financial wellness, workplace flexibility, skills development, and long-term workforce planning.

    When these areas are reviewed together, organizations may gain a clearer understanding of how retirement benefits contribute to the broader employee experience.

    An adaptable approach can help businesses maintain consistency while still responding thoughtfully to changing workforce needs.

    How Open Access Limited Supports Adaptable Retirement Benefits Strategies

    Some organizations choose to work with advisory firms experienced in aligning retirement benefits with changing employee expectations and long-term organizational priorities.

    Open Access Limited, based in Ontario, works with employers to review workforce demographics, assess participation trends, and develop retirement programs supported by ongoing employee education, communication strategies, and flexible plan design considerations.An adaptable retirement benefits strategy can improve employee understanding through ongoing education and clear communication.

    These services may help employers improve employee understanding, support participation, and keep retirement benefits aligned with workforce needs over time.

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6
    Canada

    Toll-Free: 1-866-625-4777
    General: 416-364-8877
    Fax: 416-955-4878

    Email: inquiry@openaccessltd.com
    Website: www.OpenAccessLtd.com

    Final Thoughts

    A successful retirement benefits strategy should be designed to evolve as employees, workplaces, and financial conditions change.

    By reviewing workforce demographics, monitoring employee expectations, providing ongoing education, offering appropriate flexibility, and evaluating participation over time, businesses can create retirement programs that remain relevant and understandable. A well-designed retirement benefits strategy should be reviewed regularly to ensure it continues to support changing employee needs and long-term workforce goals.

    There is no single strategy that fits every organization. However, a structured and regularly reviewed approach can help employers maintain alignment between employee needs, plan design, and long-term workforce objectives.

    Canadian HR leaders reviewing a retirement benefits strategy, changing employee needs, workforce demographics, financial wellness, flexible plan features, and retirement education in a modern corporate office.

    References

    Mercer — Global Talent Trends Research
    https://www.mercer.com

    Gallup — Workplace and Employee Experience Research
    https://www.gallup.com

    Qualtrics — Employee Experience Trends Research
    https://www.qualtrics.com

    The Josh Bersin Company — Future of Work Research
    https://joshbersin.com

    SHRM — Benefits Strategy Research
    https://www.shrm.org

    Cambridge Centre for Alternative Finance — Financial Trends Research
    https://www.jbs.cam.ac.uk/faculty-research/centres/alternative-finance/

  • How can businesses use retirement planning to support workforce resilience during future workplace changes?

    Retirement Planning Resilience: 5 Powerful Ways to Prepare for Future Changes

    Retirement planning resilience is becoming an important part of how businesses prepare employees and organizations for future workplace changes.

    As economic conditions, technology, and workforce expectations continue to evolve, organizations are looking for strategies that support adaptability, stability, and long-term employee confidence.

    A thoughtful retirement strategy can become one element of a broader workforce approach that helps employees feel more prepared during periods of change.

    Why Is Retirement Planning Resilience Important for Future Workplaces?

    Retirement planning resilience focuses on connecting workplace benefits with long-term workforce needs.

    Modern organizations recognize that employees may face changing financial responsibilities, career transitions, and evolving workplace environments.

    By providing retirement education, clear communication, and structured benefits support, businesses can help employees better understand available resources and make informed financial decisions.

    A resilient workforce strategy considers not only today’s needs but also future challenges that may impact employees and organizations.

    5 Powerful Ways Retirement Planning Supports Workforce Resilience

    1. Supporting Employee Financial Awareness

    Financial awareness is a foundation of workforce resilience.

    Retirement programs that include education and communication can help employees understand their options and prepare for long-term goals.

    When employees have access to helpful information, they may feel more confident navigating financial changes.

    2. Creating Long-Term Planning Structures

    Future workplace changes require organizations to think beyond short-term solutions.

    Retirement planning resilience provides consistent frameworks that support employees throughout different career stages.

    Structured retirement programs can help create stability while businesses adapt to changing environments.

    3. Aligning Benefits With Workforce Evolution

    Employee needs continue to change as workplaces become more diverse and flexible.

    Businesses can review retirement plan participation, employee feedback, and workforce demographics to better align benefits with future expectations.

    This approach helps retirement programs remain relevant and valuable over time.

    4. Integrating Retirement Planning With Employee Experience

    Retirement benefits are one part of the overall employee experience.

    Organizations may combine retirement planning with financial wellness, skills development, and workplace support initiatives.

    A connected strategy helps employees see benefits as part of a larger commitment to their long-term success.

    5. Building Adaptable Workforce Strategies

    Strong organizations prepare for change before challenges appear.

    Retirement planning resilience can support workforce adaptability by encouraging continuous review, education, and improvement.

    Businesses that regularly evaluate benefits strategies may be better positioned for future workplace needs.

    How Can Businesses Prepare Retirement Strategies for the Future?

    There is no single approach that fits every organization.

    Effective retirement strategies consider company goals, employee expectations, communication methods, and changing workforce trends.

    Organizations can benefit from reviewing retirement programs regularly and ensuring benefits continue to support employees through economic and workplace changes.

    How Open Access Limited Supports Workforce Resilience Strategies

    Open Access Limited, based in Ontario, works with employers to develop retirement programs that support employee education, communication, and long-term workforce planning.

    By helping organizations align retirement plan design with workforce demographics and financial profiles, Open Access Limited supports strategies focused on adaptability and employee understanding.

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6
    Phone: 1-866-625-4777
    Email: inquiry@openaccessltd.com
    Website: OpenAccessLtd.com

    Final Thoughts

    Retirement planning resilience allows businesses to connect employee benefits with future workplace needs.

    Organizations that focus on education, adaptability, and long-term planning can create stronger retirement strategies that support both employees and business objectives.

    As workplaces continue changing, retirement planning can remain an important part of building a prepared and resilient workforce.

    
Canadian business leaders discussing retirement planning resilience, workforce adaptability, employee financial education, retirement benefits, and future workplace strategies.

    References

    World Economic Forum (2024) – Future of Jobs Report
    https://www.weforum.org

    OECD (2023) – Future Skills and Workforce Adaptability Research
    https://www.oecd.org

    Gartner (2024) – Workforce Resilience and Future of Work Research
    https://www.gartner.com

    Harvard Business Review – Organizational Resilience and Workforce Strategy Insights
    https://hbr.org

    Microsoft (2024) – Work Trend Index
    https://www.microsoft.com

    Boston Consulting Group (BCG) – Building Resilient Organizations Research
    https://www.bcg.com

  • How can businesses use retirement benefits to support talent attraction and retention efforts?

    Retirement Benefits Retention: 5 Powerful Ways to Attract Talent

    Retirement Benefits Retention: 5 Powerful Ways to Attract Talent

    Retirement benefits retention strategies are becoming increasingly important as businesses compete to attract skilled employees and maintain a strong workforce.

    In today’s competitive labour market, employees often evaluate more than salary when considering career opportunities. Workplace culture, professional growth, flexibility, and financial benefits can all influence how employees view an organization.

    A thoughtful retirement benefits strategy may support long-term employee confidence and strengthen the overall employee value proposition.

    Why Do Retirement Benefits Matter for Talent Attraction?

    Retirement benefits retention strategies help organizations demonstrate a commitment to employees’ long-term financial well-being.

    For many employees, workplace benefits represent an important part of the total compensation experience.

    When retirement programs are clearly designed and communicated, employees may better understand the value their employer provides beyond regular income.

    Strong retirement benefits can help businesses create a more complete and competitive employment offering.

    5 Powerful Ways Retirement Benefits Support Employee Retention

    1. Building a Strong Employee Value Proposition

    A successful employee value proposition includes more than compensation.

    Retirement benefits, financial wellness resources, workplace support, and career opportunities work together to shape the employee experience.

    Organizations that align retirement programs with employee expectations may create stronger connections with their workforce.

    2. Supporting Long-Term Financial Wellness

    Employees at different career stages often have different financial priorities.

    Retirement benefits retention strategies can include education, accessible resources, and communication that help employees understand long-term planning options.

    Improving financial awareness may help employees feel more informed when making decisions about their future.

    3. Improving Benefits Communication

    A retirement program only creates value when employees understand it.

    Clear communication helps employees recognize available resources and how retirement programs fit within their broader financial goals.

    Businesses can improve engagement by providing ongoing education instead of only introducing benefits during onboarding.

    4. Aligning Benefits With Workforce Needs

    Different generations and employee groups may have different expectations.

    Organizations can review workforce demographics, employee feedback, and participation trends to better align retirement benefits with changing needs.

    Flexible approaches may help businesses create programs that remain relevant over time.

    5. Strengthening Employer Positioning

    There is no single retirement approach that guarantees improved attraction or retention results.

    Organizations should consider workforce characteristics, employee needs, communication methods, and business objectives.

    A balanced and data-informed approach helps employers design benefits that support both employees and organizational goals.

    Creating Stronger Employee Confidence

    Retirement programs strategies can also support employee confidence by helping workers better understand available financial resources. When organizations provide ongoing education and clear retirement communication, employees may feel more connected to workplace benefits and long-term planning opportunities.

    How Open Access Limited Supports Retirement Benefits Strategies

    Open Access Limited, based in Ontario, works with employers to design retirement programs aligned with workforce expectations and organizational objectives.

    Through tailored communication strategies, employee education initiatives, and flexible plan structures, Open Access Limited helps organizations improve employee understanding of retirement benefits and strengthen the overall employee value proposition.

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6
    Phone: 1-866-625-4777
    Email: inquiry@openaccessltd.com

    Website: OpenAccessLtd.com

    Final Thoughts

    Retirement benefits retention strategies can play an important role in supporting talent attraction and long-term workforce engagement.

    By focusing on financial wellness, communication, education, and employee experience, businesses can create retirement programs that provide meaningful workplace value.

    A thoughtful retirement benefits approach can help organizations strengthen their workforce strategy and prepare for future talent expectations.

    
Canadian HR professionals discussing retirement benefits retention, talent attraction strategies, employee financial wellness, workplace benefits, and long-term workforce engagement.


    References

    LinkedIn (2024) – Workplace Learning and Talent Trends
    https://www.linkedin.com

    Randstad (2024) – Employer Brand and Talent Insights Research
    https://www.randstad.com

    ManpowerGroup – Global Talent Shortage Report
    https://www.manpowergroup.com

    Korn Ferry – Future of Work and Talent Strategy Research
    https://www.kornferry.com

    Great Place to Work Institute – Workplace Culture and Employee Experience Research
    https://www.greatplacetowork.com

    Workhuman – Employee Experience and Engagement Research
    https://www.workhuman.com

  • How can businesses evaluate retirement planning as part of a long-term workforce investment strategy?

    Retirement Planning Investment: 5 Powerful Ways to Build Workforce Success

    Retirement planning investment is becoming an important part of how organizations evaluate long-term workforce success, employee engagement, and sustainable business growth.

    For many businesses, retirement programs have traditionally been viewed as employee benefit expenses. However, modern organizations are increasingly considering how these programs can support broader workforce objectives.

    A strategic approach to retirement planning may help companies strengthen employee confidence, improve benefits understanding, and create a stronger connection between workplace programs and organizational goals.

    Why Should Businesses View Retirement Planning as an Investment?

    A retirement planning investment goes beyond providing a standard workplace benefit.

    When designed effectively, retirement programs can support workforce stability, employee value proposition, and long-term planning needs.

    Employees often evaluate workplace benefits as part of their overall employment experience. A well-structured retirement strategy may contribute to stronger engagement by helping employees understand the value of their total rewards package.

    Organizations that evaluate retirement planning strategically can better understand how benefits influence workforce expectations and future planning.

    5 Powerful Ways Retirement Planning Investment Supports Workforce Strategy

    1. Strengthening Long-Term Workforce Stability

    Retirement programs can support workforce stability by creating benefits structures that encourage long-term participation.

    When employees understand available retirement resources, they may feel more prepared when making financial decisions.

    Clear retirement planning strategies can help organizations build a more informed and engaged workforce.

    2.Improving Employee Financial Education

    Employee financial education is a key part of successful retirement planning investment.

    Providing resources, guidance, and communication can help employees better understand retirement options and available workplace benefits.

    Education helps transform retirement programs from simple benefits into meaningful workforce support tools.

    3. Supporting Employee Value Proposition

    A strong employee value proposition includes more than salary.

    Benefits, workplace culture, professional development, and financial wellness programs all influence how employees view their organization.

    Retirement planning can become part of a complete benefits strategy that supports attraction, engagement, and long-term workforce goals.

    4. Connecting Benefits With Business Objectives

    Organizations can evaluate retirement plans by considering how they align with company priorities.

    This may include workforce planning goals, employee participation, communication effectiveness, and long-term organizational needs.

    A thoughtful retirement planning investment helps connect employee support with broader business strategies.

    5. Creating Sustainable Workforce Planning

    Workforce needs continue to change as employee expectations, demographics, and economic conditions evolve.

    Retirement strategies that include regular review and improvement can help businesses maintain benefits that remain relevant over time.

    A sustainable approach allows organizations to adapt while supporting employees through different career stages.

    How Can Organizations Measure Retirement Planning Value?

    Businesses may review retirement programs alongside workforce indicators such as employee feedback, participation levels, engagement trends, and retention considerations.

    The impact of retirement planning can vary depending on plan design, workforce characteristics, and business objectives.

    For this reason, organizations often benefit from a structured approach that combines analysis, communication, and ongoing improvement.

    How Open Access Limited Supports Workforce Investment Strategies

    Open Access Limited, based in Ontario, works with employers to align retirement plan structures with organizational goals, employee education strategies, and long-term workforce planning needs.

    Through customized communication, contribution framework design, and benefits strategy support, Open Access Limited helps organizations evaluate retirement programs as part of a broader workforce investment approach.

    Open Access Limited
    302 Bay Street, Suite 503-01
    Toronto, ON M5H 0B6
    Phone: 1-866-625-4777
    Email: inquiry@openaccessltd.com
    Website: OpenAccessLtd.com

    Final Thoughts

    Retirement planning investment can help businesses create stronger connections between employee benefits and organizational success.

    By focusing on education, workforce stability, employee engagement, and sustainable planning, companies can build retirement strategies that support both employees and future business goals.

    Viewing retirement planning as a long-term workforce strategy allows organizations to create benefits programs with greater purpose and value.

    
Canadian business executives discussing retirement planning investment, workforce strategy, employee financial education, benefits value, and long-term organizational success in a modern corporate office.

    References

    Boston Consulting Group (BCG) – Future of Work and Workforce Strategy Research
    https://www.bcg.com

    Willis Towers Watson (WTW) – Global Benefits Attitudes Survey
    https://www.wtwco.com

    Aon – Employee Benefits and Workforce Strategy Insights
    https://www.aon.com

    The Conference Board – Human Capital and Workforce Strategy Research
    https://www.conference-board.org

    International Foundation of Employee Benefit Plans (IFEBP) – Benefits and Workforce Planning Research
    https://www.ifebp.org

    WorldatWork – Total Rewards and Workforce Strategy Insights
    https://worldatwork.org